
From Bagholder to Multibagger, the DalalBytes book
Five pillars to judge a business, the psychology to hold it through a bear market, and the losers left in. Paperback, 139 pages.
Research Reports
Full-length investment research: five-pillar gradings and deep-dive reports, each with a verdict
Jump to the coverage index ↓ · Earnings Tracker: upcoming dates for the 25 owned holdings →
Sigma Solve: Investment Report
52/100 Neutral. A debt free IT services boutique: FY26 PAT of Rs 24 cr on sales of Rs 96 cr, operating margin of 30%, promoters at 73.21% with zero pledging, at 13.3x headline earnings. The caution is earnings quality and growth: Q1 FY27 other income of Rs 8.97 cr was 54% of profit before tax and is unexplained, core earnings put the stock at about 18 to 19x, and H1 FY27 sales grew 0.4%. FY2029 targets Rs 25 / Rs 48 / Rs 72.
Sigma Solve: Five-Pillar Analysis
Weak fit · 1 of 5 pass. Iron Fortress PASS, Moat FAIL, Sunrise PARTIAL, Leadership PARTIAL, Free Cash Flow PARTIAL. A debt free fortress (net worth Rs 77.07 cr, borrowings Rs 2.01 cr, zero pledging) against a moat of referrals and rented platform badges, flat sales, family leadership with SME grade disclosure, and cash flow mixed with treasury movements.
Enphase Energy: Investment Report
58/100 Selective Positive. The fortress on a trough: Q3 2026 revenue fell 28.5% to $293M after the Section 25D homeowner credit expired, with $85M of safe harbor inside the print, while cash and securities of $931.8M stand against one $575M convertible due 2028. The recovery path is batteries, guided from about 450 MWh in 2026 to 675 MWh in 2027. FY2029 targets $22 / $66 / $99.
Enphase Energy: Five-Pillar Analysis
Moderate fit · 2 of 5 pass. Moat PASS, Iron Fortress PASS, Sunrise PARTIAL, Leadership PARTIAL, Free Cash Flow PARTIAL. The walls pass and the weather does not: a 25-year microinverter warranty and net cash on one side, a US residential market expected to contract about 19% in 2026 and free cash flow down from $480M to $96M on the other. FY2029 targets $22 / $66 / $99.
Page Industries: Investment Report
67/100 Selective Positive. The rented crown: FY26 revenue of Rs 5,247 crore grew 6.3% with a 22.0% EBITDA margin and 52.5% ROE, borrowings excluding leases of about Rs 12 crore, against a Jockey licence documented to 2030 and Q1 FY27 PAT down 4.0%. FY2029 targets Rs 23,000 / Rs 39,200 / Rs 51,800.
Page Industries: Five-Pillar Analysis
Moderate fit · 2 of 5 pass. Moat PASS, Iron Fortress PASS, Sunrise PARTIAL, Leadership PARTIAL, Free Cash Flow PARTIAL. The build grades in the 80s and the trajectory in the 50s: 116,600-plus outlets and no lender risk, against 6.3% growth and a USD 1 billion promise missed by about 40%. FY2029 targets Rs 23,000 / Rs 39,200 / Rs 51,800.
NVIDIA: Investment Report
72/100 Positive. The toll booth at peak margin: Data Center revenue of $89.0B grew 117% in Q2 fiscal 2027, gross margin held 75.0% and is guided down toward 71%, and guarantees capped at $108.5B now stand behind customer campuses. The question is the quality of the peak. FY2029 targets $140 / $425 / $610.
NVIDIA: Five-Pillar Analysis
Strong fit · 3 of 5 pass. Sunrise PASS, Leadership PASS, Moat PASS, Iron Fortress PARTIAL, Free Cash Flow PARTIAL. The operating pillars grade at the top of the library, marked down for the ecosystem pledges: $366B of commitments and a receivables line up 64% in six months. FY2029 targets $140 / $425 / $610.
Alphabet: Investment Report
74/100 Positive. The strongest consumer franchise in technology meets the capex supercycle: Cloud revenue doubled to $30.7B in Q3 2026 on a $561B backlog, Search grew 12% through the AI transition, and the TPU became a product line with Anthropic committed through 2033. The caution is cash: free cash flow printed negative for two straight quarters and long-term debt nearly tripled to $125.1B in nine months. FY2029 targets $150 / $390 / $580.
Alphabet: Five-Pillar Analysis
2 of 5 pass, 3 partial. Sunrise PASS, Moat PASS, Leadership PARTIAL, Iron Fortress PARTIAL, Free Cash Flow PARTIAL. The operations grade near the top of the library, marked down only where the 2026 buildout touched the balance sheet and the cash flow statement: $265.1B of liquid assets against $125.1B of long-term debt and $924B of purchase commitments. FY2029 targets $150 / $390 / $580.
Amazon: Investment Report
74/100 Positive. The largest cloud re-accelerates: AWS revenue of $46.0B in Q3 2026 grew 39.3% on a $578B backlog with growth guided above 40% for 2027 and 2028, an Anthropic stake carried at $238.7B, and advertising at $76.1B trailing. The caution is the bill: trailing free cash flow of negative $42.4B and gross debt face value of $180.9B. FY2029 targets $125 / $305 / $455.
Amazon: Five-Pillar Analysis
Strong fit · 3 of 5 pass. Sunrise PASS, Leadership PASS, Moat PASS, Iron Fortress PARTIAL, Free Cash Flow PARTIAL. The operating pillars grade near the top of the library, marked down only for the debt-funded buildout: $180.9B of gross debt face value against $114.2B of cash and securities. FY2029 targets $125 / $305 / $455.
Microsoft: Investment Report
74/100 Positive. The fortress funds the build: Azure revenue of $33.2B grew 48% in its first dollar disclosure, commercial backlog stands at $677B, and Microsoft 365 Copilot passed 30 million paid seats. The caution is the cash line: capex near $170B in calendar 2026 has cut free cash flow three years in a row, and Maia silicon remains internal only. FY2029 targets $425 / $720 / $950.
Microsoft: Five-Pillar Analysis
Strong fit · 4 of 5 pass. Sunrise PASS, Leadership PASS, Moat PASS, Iron Fortress PASS, Free Cash Flow PARTIAL. The business grades at the top of the library, marked down only on the cash pillar, where free cash flow fell from $74.1B to $67.0B in two years under the build. FY2029 targets $425 / $720 / $950.
Broadcom: Investment Report
76/100 Positive. The design layer of the custom AI era: AI revenue of $16.7B in Q3 fiscal 2026 guided to $21.7B in Q4, fiscal 2028 AI guided to about $230B, VMware software compounding underneath at a 77% segment margin, and free cash flow of $26.9B in fiscal 2025. The caution is concentration: six XPU customers carry the guide, and gross debt stands at $59.4B. FY2029 targets $310 / $840 / $1170.
Broadcom: Five-Pillar Analysis
Strong fit · 4 of 5 pass. Sunrise PASS, Leadership PASS, Moat PASS, Free Cash Flow PASS, Iron Fortress PARTIAL. The business grades near the top of the library, marked down only for $59.4B of gross debt against $24B of cash after the VMware acquisition. FY2029 targets $310 / $840 / $1170.
Jenburkt Pharmaceuticals: Investment Report
65/100 Selective Positive. A debt free branded formulations business: FY26 PAT of Rs 34.74 cr on sales of Rs 169 cr, ROE of 18.84%, a dividend raised five straight years to Rs 20.70, promoters at 46.62% with zero pledging, at 11.5x earnings and a fresh 52 week low. The caution is Q1 FY27: sales flat, operating margin down to 17.0% from 25.2%, PAT down 24.4%, and no management explanation on record ahead of Q2 results on November 3, 2026. FY2029 targets Rs 710 / Rs 1,320 / Rs 1,820.
Jenburkt Pharmaceuticals: Five-Pillar Analysis
Weak to moderate fit · 1 of 5 pass. Sunrise PARTIAL, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PARTIAL. A debt free fortress (net worth Rs 197.04 cr, borrowings Rs 2.49 cr, cash Rs 53.11 cr, zero pledging) against four partials: a chronic therapy sunrise ridden at 8% growth, family leadership with no disclosure habit, a habit based brand moat, and free cash flow of roughly Rs 8 to 13 cr while a Rs 46.12 cr expansion is built.
IndiaMART InterMESH: Investment Report
71/100 Selective Positive. India's B2B toll booth: FY26 revenue of Rs 1,569 cr (up 13%), free cash flow of Rs 687 cr, cash and investments of Rs 3,234 cr against borrowings of Rs 20 cr, at 17.8x earnings after a 40% one year fall. The selective part is the funnel: paying suppliers down 2% to 217,000 in Q2 FY27, enquiries down 14%, active buyers down 7%, and all growth carried by ARPU up 10% to about Rs 72,000. FY2029 targets Rs 1,350 / Rs 2,350 / Rs 3,400.
IndiaMART InterMESH: Five-Pillar Analysis
Moderate-to-good fit · 3 of 5 pass. Sunrise PARTIAL, Leadership PARTIAL, Moat PASS, Iron Fortress PASS, Free Cash Flow PASS. About 60% of online B2B classifieds, a Rs 2,029 cr deferred revenue book, and about 139% five year cash conversion, against Silver churn near 40% and an enquiry layer falling under AI search. Score 71/100, Selective Positive.
Netflix: Investment Report
72/100 Positive. Q3 2026 revenue rose 11.8% at a 34.6% operating margin, buybacks set a record $4.8B quarter, and the $2.8B Warner Bros. termination fee sits in the results. The ads guide was cut to $2.7B and growth has slowed for three straight quarters. FY2029 targets $46 / $85 / $118.
Netflix: Five-Pillar Analysis
Good fit · 4 of 5 pass. Sunrise, Moat, Iron Fortress, and Free Cash Flow all pass on filed evidence. Leadership grades partial after the October 2026 advertising guide cut and the content chief's departure. Score 72/100, Positive.
Intel: Investment Report
47/100 Negative. Q3 2026 revenue rose 21% and data center revenue 78%, foundry losses narrowed for three straight quarters, and the balance sheet was rebuilt with $38B of other people's equity. The $92.07 price paid for the finished recovery, and the Q4 guide cut the stock by about a quarter after hours. FY2029 targets $24 / $72 / $143.
Intel: Five-Pillar Analysis
Weak fit · 1 of 5 pass. Sunrise PASS on the AI server build out. Leadership, Moat, and Iron Fortress all grade partial. Free Cash Flow FAIL on three straight negative filed years, a balance sheet rebuilt by issuance, and an x86 moat narrowing to AMD and Arm at both ends.
Bloom Energy: Investment Report
54/100 Neutral. Revenue up 138% in Q3 2026, guidance raised three times in one year, backlog near $20B, and a stock that pays today for 2029 delivery. One counterparty drove about 73% of Q2 revenue, free cash flow was negative in a record quarter, and a class action tests past supply chain statements. FY2029 targets $47 / $133 / $275.
Bloom Energy: Five-Pillar Analysis
Mixed fit · 1 of 5 pass. Sunrise PASS on the power shortage. Leadership, Moat, Iron Fortress, and Free Cash Flow all grade partial. Cash of $2,486.7M roughly matches $2,473.5M of recourse debt, and trailing free cash flow leans on one giant collection quarter.
Arm Holdings: Investment Report
54/100 Neutral. The toll road of the AI era: fiscal 2026 revenue of $4.92B, royalties of $2.61B, data center royalties doubling again, and a first own chip with customer demand above $2B. The price already pays for the fiscal 2031 plan: 243 times trailing GAAP earnings, SoftBank at about 86% with a $25B margin loan against the shares, and a Qualcomm royalty ruling still open in Delaware. FY2029 targets $91 / $207 / $319.
Arm Holdings: Five-Pillar Analysis
Moderate fit · 3 of 5 pass. Sunrise PASS, Moat PASS, Iron Fortress PASS, Leadership PARTIAL, Free Cash Flow PARTIAL. An elite royalty business on a fortress balance sheet, graded down for SoftBank control of about 86% and stock pay above $1B a year with no buyback.
Sterling Tools: Investment Report
56/100 Neutral. India's second largest fastener maker: FY26 standalone PAT of Rs 64.20 cr on income up 11.4%, a record standalone quarter in Q2 FY27, promoters at 64.86% with zero pledging, at 1.39x book. The neutral part is the EV pivot: Ola Electric insourced MCUs and removed about Rs 280 cr of revenue, consolidated PAT halved to Rs 29 cr in FY26 and fell to Rs 2.97 cr in Q2 FY27, and borrowings rose 38% since March 2026 against a capex plan raised to about Rs 135 cr. FY2029 targets Rs 120 / Rs 285 / Rs 510.
Sterling Tools: Five-Pillar Analysis
Weak to moderate fit · 1 of 5 pass. Sunrise PARTIAL, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PARTIAL. A net debt free fastener parent (net worth Rs 526 cr, interest cover near 9x) against four rebuild linked partials: an EV timeline pushed out by years, a 94% single customer concentration that broke, licensed technology in every growth line, and FY26 free cash flow of Rs 5 cr.
Asian Paints: Investment Report
65/100 Selective Positive. India's paint fortress: FY26 revenue of Rs 35,584 cr (up 4.95%), PAT after minority of Rs 4,325 cr (up 17.9%), record free cash flow of Rs 5,604 cr and an IND AAA fortress, at 45.3x earnings. The selective part is the siege and the quarter: Q2 FY27 PBDIT margin of 15.6% on about 25% material inflation, decorative share down from about 59% to about 52% on Elara estimates, and Birla Opus at 1,332 MLPA of capacity. FY2029 targets Rs 1,450 / Rs 2,600 / Rs 3,800.
Asian Paints: Five-Pillar Analysis
Moderate fit · 2 of 5 pass. Sunrise PARTIAL, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. Both money pillars pass (a decade of net cash, about Rs 15,070 cr of free cash flow over five years at about 72% conversion) against a slow demand sunrise, share defence, and a moat being crossed at a measurable rate.
Oracle Corporation: Investment Report
62/100 Selective Positive. The backlog is real: RPO at $664B, cloud infrastructure revenue up 121% in Q1 FY2027, and a database moat that now sells inside all three rival clouds. The balance sheet pays for it: borrowings of $125.3B, free cash flow negative $23.7B in FY2026, and a BBB- rating one notch above junk after the July 2026 cut. Management capped new funding at $20B more on October 28, 2026. FY2029 targets $102 / $230 / $330.
Oracle Corporation: Five-Pillar Analysis
Weak-to-moderate fit · 2 of 5 pass. Sunrise PASS, Moat PASS, Leadership PARTIAL, Iron Fortress FAIL, Free Cash Flow FAIL. A pass-grade database moat in a sunrise market, funded by a balance sheet that sits one notch above junk in the middle of the largest build in company history.
Associated Alcohols and Breweries: Investment Report
64/100 Selective Positive. The Kedia family's integrated MP distiller: FY26 revenue of Rs 1,019.40 cr (down 5.3%), PAT up 8.7% to Rs 88.48 cr, proprietary IMFL up 58% in Q1 FY27 to a record Rs 79.2 cr, borrowings down to Rs 69 cr, and promoters at 62.35% with zero pledging, at 13.1x earnings. The selective part is policy: the ethanol segment lost Rs 8.37 cr in Q1 FY27, the cash conversion cycle stretched to 110 days, and the state sets tenders, prices and allocations. FY2029 targets Rs 440 / Rs 900 / Rs 1,480.
Associated Alcohols and Breweries: Five-Pillar Analysis
Weak to moderate fit · 1 of 5 pass. Sunrise PARTIAL, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PARTIAL. A light debt fortress (net worth Rs 695 cr, interest cover above 20x, CRISIL A- / Positive) against four conversion linked partials: premium demand over 23% of revenue, a state controlled moat, and FY26 free cash flow of about zero.
Robinhood Markets: Investment Report
66/100 Selective Positive. The Financial SuperApp is built: 14 business lines above $100M in annualized revenue, $396B of platform assets, $71B of trailing net deposits, and a 57% adjusted EBITDA margin in Q3 2026. The selective part is the price and the perimeter: at $94.56 the stock pays 31x FY2027 consensus while 21 states litigate the event-contract line that grew more than 6x in a year. FY2029 targets $46 / $110 / $158.
Robinhood Markets: Five-Pillar Analysis
Moderate-to-good fit · 3 of 5 pass. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PARTIAL. The widest top of funnel in US retail finance, a net-cash corporate core, and a delivery record that beat its own guides, against $13.8K of assets per account and a cash statement that is float arithmetic.
Kennametal India: Investment Report
63/100 Selective Positive. India's only listed pure carbide tooling company: FY26 revenue of Rs 1,511 cr (up 29.1%), PAT of Rs 196 cr, zero debt and net worth of Rs 854 cr, on a roughly tenfold tungsten rise. The selective part is the quality of that profit: an estimated Rs 33 of EPS of Rs 89.18 is price-timing gain, free cash flow was negative Rs 35 cr, and inventory hit 280 days at peak prices. FY2029 targets Rs 2,050 / Rs 3,700 / Rs 6,100.
Kennametal India: Five-Pillar Analysis
Weak-to-moderate fit · 1 of 5 pass. Sunrise PARTIAL, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PARTIAL. A fortress balance sheet (interest of Rs 0.03 cr, IND AA- / Stable) against category-rate growth, a parent-owned moat, and five-year cash conversion of just 36% of PAT.
NDR Auto Components: Investment Report
62/100 Selective Positive. The Relan group's Tier 2 seat frame and trim maker: FY26 revenue of Rs 822.54 cr (up 15.4%), consolidated PAT of Rs 62.09 cr, operating margin up five straight years to 11%, zero bank debt, and promoters at 73.36% with zero pledging, at about 24x earnings. The selective part is concentration and the promise: about 70% of end revenue traces to Maruti Suzuki, FY26 free cash flow was negative Rs 36 cr, and the Rs 3,000 cr FY30 target needs 38% compound growth against a flat Rs 650 cr order book. FY2029 targets Rs 400 / Rs 800 / Rs 1,175.
NDR Auto Components: Five-Pillar Analysis
Weak to moderate fit · 1 of 5 pass. Sunrise PARTIAL, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PARTIAL. A zero-debt fortress (net worth Rs 358 cr, interest cover 31.73x, minus 1 day cash conversion) against four partials with one root: about 70% of end revenue runs through Maruti Suzuki.
Ingersoll Rand (India): Investment Report
68/100 Selective Positive. The highest-return listed compressor maker in India: FY26 ROE of 42.1%, ROCE of 56.3%, PAT of Rs 256 cr, zero debt and free cash flow positive five years running, with Sanand ramping and Q1 FY27 revenue up 20.3%. The selective part is the slope and the price: FY26 revenue grew 4.2% with PAT down 4.3%, the parent takes about 92% of profit out as dividends, and the stock trades at 44 to 46x earnings, roughly double peers on sales. FY2029 targets Rs 2,575 / Rs 4,600 / Rs 6,850.
Ingersoll Rand (India): Five-Pillar Analysis
Moderate fit · 2 of 5 pass. Sunrise PARTIAL, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. Both money pillars pass (debt of about Rs 9 cr, free cash flow of about Rs 772 cr over five years), against 4% growth years, no published guidance or order book, and a centrifugal moat whose brands belong to the 75% parent.
Saksoft: Investment Report
66/100 Selective Positive. A 27-year-old digital engineering firm that crossed Rs 1,000 cr of revenue in FY26 (up 14.1%) with PAT up 22.5% to Rs 133 cr, free cash flow of Rs 167 cr above reported profit, net cash of about Rs 207 to 250 cr, and promoters at 66.72% with zero pledging, at 12.6x earnings. The selective part is the slope: Q1 FY27 revenue was flat at Rs 249 cr, and the USD 500 million FY30 target needs about 33% compound growth under a CEO who started on October 12, 2026. FY2029 targets Rs 95 / Rs 185 / Rs 260.
Saksoft: Five-Pillar Analysis
Moderate fit · 2 of 5 pass. Sunrise PARTIAL, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. A net cash fortress and a cash engine that beats reported profit three years running, against mid-market demand that defers first, a two-week-old CEO succession, and a relationship moat with no pricing power.
Polycab India: Investment Report
73/100 Selective Positive. India's wires and cables champion: FY26 revenue of Rs 28,884 cr (up 29%), PAT of Rs 2,708 cr, organised share up 3 to 4 points in one year to 30 to 31%, H1 FY27 revenue up 46%, and net cash of Rs 4,520 cr. The selective part is the arithmetic around it: growth flattered by copper while Q1 FY27 volumes grew in single digits, material costs at 76.4% of sales, UltraTech in production since September 2026, and a full 36x multiple at Rs 7,662. FY2029 targets Rs 5,900 / Rs 11,300 / Rs 14,800.
Polycab India: Five-Pillar Analysis
Moderate-to-good fit · 3 of 5 pass. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PARTIAL. A structural electrification sunrise and a team that beat its Rs 20,000 cr target by 44%, against a specification moat now contested by UltraTech and Adani, and cash conversion that leaks into inventory in fast-growth years.
Systematix Corporate Services: Investment Report
54/100 Neutral. A 41-year-old merchant banker in a record primary market (FY26 IPO fundraising of Rs 1.8 lakh cr), with operating revenue flat at Rs 146 cr, PAT down from Rs 53 cr to Rs 14 cr, losses in Q4 FY26 and Q1 FY27, and negative cash flow two years running. The counterweight is the fortress: net worth of about Rs 314 cr, borrowings of Rs 19 cr, promoters at 70.58% with nil pledging, priced at 3.3x book. FY2029 targets Rs 38 / Rs 78 / Rs 125.
Systematix Corporate Services: Five-Pillar Analysis
Weak-to-moderate fit · 2 of 5 pass. Sunrise PASS, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow FAIL. A record market and a fortress balance sheet, against flat revenue in a record fee pool, peak-cycle capital in loss-making builds, and operating cash flow negative in both FY25 and FY26.
Info Edge (India): Investment Report
68/100 Selective Positive. Two businesses in one share: Naukri's classifieds machine (standalone FY26 revenue of Rs 3,052 cr at a 41% operating margin, free cash flow of Rs 1,098 cr) and India's best venture book (Eternal and PB Fintech stakes plus cash at roughly 64% of the market cap). The selective part is the speed and the price: billings growth normalised to low teens, Shiksha billings down about 25% in H1 FY27 on AI search changes, and a full multiple on the operating core. FY2029 targets Rs 780 / Rs 1,450 / Rs 1,950.
Info Edge (India): Five-Pillar Analysis
Good fit · 4 of 5 pass. Sunrise PARTIAL, Leadership PASS, Moat PASS, Iron Fortress PASS, Free Cash Flow PASS. A 118 million resume moat, borrowings of Rs 259 cr against Rs 42,299 cr of investments, and five straight years of rising standalone free cash flow, against a demand sunrise that AI is repainting.
Jindal Drilling and Industries: Investment Report
62/100 Selective Positive. India's incumbent jack-up contractor: six rigs, FY26 revenue of Rs 997 cr, a Rs 1,310 cr order book, net cash of Rs 183 cr and promoters at 66.78% with nil pledging, priced at 0.81x book. The selective part is the structure: ONGC is effectively the only customer, reported FY26 PAT of Rs 211 cr includes a Rs 100.43 cr litigation receipt (underlying PAT estimated near Rs 150 cr), and three rigs come off hire in H2 FY27 for Rs 270 cr to Rs 330 cr of refurbishment. FY2029 targets Rs 320 / Rs 650 / Rs 1,040.
Jindal Drilling and Industries: Five-Pillar Analysis
Weak-to-moderate fit · 1 of 5 pass. Sunrise PARTIAL, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PARTIAL. A fortress balance sheet (net cash Rs 183 cr, CRISIL A+/Stable) around a single-customer, tender-priced fleet with no pricing power and lumpy, litigation-assisted cash flow.
Tesla: The Options Are the Company
58/100 Neutral. A $1.53T market cap priced on robotaxi and Optimus, against a flat car business at 18.1% auto margin ex-credits, about $36B of net cash, and a promise scorecard dominated by misses. FY2029 targets $120 / $330 / $620.
Tesla: Five-Pillar Analysis
Moderate fit: 2 pass, 3 partial. Sunrise and Iron Fortress pass on real, early markets and about $36B of net cash. Leadership, Moat, and Free Cash Flow are partial: the timeline record, share pressure from BYD and Waymo, and a 0.4% free cash flow yield.
Bosch Ltd: Investment Report
67/100 Selective Positive. India's defining auto technology supplier: FY26 revenue of Rs 20,035 cr (up 10.8%), adjusted PAT of about Rs 2,347 cr, borrowings of Rs 7 cr against about Rs 8,700 cr of cash and investments, and two 2026 joint ventures buying the electric future. The selective part is the price: about 56x adjusted earnings for a 13.2% EBITDA margin, reported profit flattered by a Rs 556 cr divestment gain, and the group's software arm outside the listed company. FY2029 targets Rs 38,100 / Rs 55,200 / Rs 75,800.
Bosch Ltd: Five-Pillar Analysis
Moderate-to-good fit · 3 of 5 pass. Sunrise PARTIAL, Leadership PASS, Moat PASS, Iron Fortress PASS, Free Cash Flow PARTIAL. Top-tier leadership delivery, design-in moat and fortress balance sheet, against a powertrain swap in progress and free cash flow that pauses for the transition investment cycle.
Boston Scientific: The Engine Under the Wreckage
67/100 Selective Positive. A category-creating cash engine halved in ten months: $20.07B of FY2025 sales and $3.66B of free cash flow at 80% conversion, against two guidance cuts, a cyberattack that forced guidance withdrawal, a halved FARAPULSE share, a stalling Watchman, and the $14.5B Penumbra deal. FY2029 targets $41 / $65 / $87.
Boston Scientific: Five-Pillar Analysis
Moderate-to-good fit: 2 pass, 3 partial. Sunrise and Free Cash Flow pass on category growth and 80% cash conversion. Leadership, Moat, and Iron Fortress are partial: the 2026 guidance record, two contested category crowns, and Penumbra leverage.
SoFi Technologies: The Bank Engine Is Real
68/100 Selective Positive. A national bank with $45.5B of deposits, 15.8M members, eleven straight GAAP-profitable quarters, and cross-buy at 51%, halved on a credit dispute, a lost platform client, and two dilutive raises. FY2029 targets $11 / $28 / $46.
SoFi Technologies: Five-Pillar Analysis
Moderate-to-good fit: 2 pass, 3 partial. Sunrise and Leadership pass on verified delivery. Moat, Iron Fortress, and Free Cash Flow are partial: the funding is bought at promo rates, the loan book is marked procyclically, and growth still reaches for equity.
Butterfly Network: The Chip Is Real, the Annuity Is Not
52/100 Neutral. Record Q2 2026 revenue of $32.6M at a 71% gross margin, but Core grew 2% and a third of the quarter was Embedded licensing, primarily Midjourney. At 17x trailing sales the pivot is priced before it is proven. FY2029 targets $3 / $7 / $14.
Butterfly Network: Five-Pillar Analysis
Weak-to-moderate fit: 1 pass, 3 partial, 1 fail. Sunrise passes on two expanding categories. Free Cash Flow fails on the record. Leadership, Moat, and Iron Fortress are partial: a better operating regime inside an unproven cash model.
Ksolves India: Investment Report
61/100 Selective Positive. A founder-led IT services firm with elite cash economics: FY26 revenue of Rs 162.7 cr, free cash flow of Rs 29 cr, a 76% payout and a 4.47% yield, promoter holding 58.92% with zero pledging. The selective part is the stall: PAT has been flat at Rs 34.3 cr for three years as margin reset from 43% to 30%, and FY27 guidance was cut to flat to plus 5% after two top-10 clients ramped down. FY2029 targets Rs 155 / Rs 305 / Rs 515.
Ksolves India: Five-Pillar Analysis
Weak-to-moderate fit · 1 of 5 pass. Sunrise PARTIAL, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PARTIAL, Free Cash Flow PASS. Elite cash generation against choppy midmarket demand, a hard guidance cut, a credentials moat without lock-in, and a balance sheet kept thin by the payout policy.
Abbott India: Investment Report
74/100 Selective Positive. India's number two pharma company: power brands led by Thyronorm, FY26 revenue of Rs 6,929 cr, PAT of Rs 1,552 cr, ROCE of about 45% and a dividend payout of about 90%. The selective part is slowing growth (Q1 FY27 revenue up 4.3%), a largest brand block that is Novo Nordisk property marketed under arrangement in a GLP-1 disrupted therapy, and a full 35.5x multiple near the 52-week low. FY2029 targets Rs 27,600 / Rs 36,900 / Rs 47,900.
Abbott India: Five-Pillar Analysis
Good fit · 4 of 5 pass. Sunrise PARTIAL, Leadership PASS, Moat PASS, Iron Fortress PASS, Free Cash Flow PASS. Top-tier leadership delivery, brand moat, balance sheet and cash conversion, against steady rather than fast demand growth and a GLP-1 headwind in diabetes care.
Jagsonpal Pharmaceuticals: Investment Report
62/100 Selective Positive. A 48-year-old women's health franchise rebuilt by private equity: operating PAT compounded at about 24% since FY22 to Rs 44.6 cr, free cash flow of Rs 61.4 cr in FY26, about Rs 191 cr of cash and no effective debt. The selective part is the growth label: revenue compounded at about 7%, the top 10 brands are about 58% of revenue, and the case now rests on integrating Yash Pharma, Aequitas and the Group Pharma wellness portfolio. FY2029 targets Rs 150 / Rs 290 / Rs 450.
Jagsonpal Pharmaceuticals: Five-Pillar Analysis
Moderate fit · 3 of 5 pass. Sunrise PASS, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. A fortress balance sheet and an elite cash conversion record, against a four-year PE-era leadership record with three integrations running and a prescriber-habit moat that counterfeiters already tested.
Vinati Organics: Investment Report
70/100 Selective Positive. The world's largest maker of ATBS and IBB at about 65% global share in each: FY26 consolidated revenue of Rs 2,227 cr, PAT of Rs 444 cr, borrowings of about nil and operating cash flow of Rs 558 cr. The selective part is the three-year stall (sales compounded at 3%), a Veeral Organics ramp that cut consolidated PAT Rs 44 cr below standalone, and a stock at its 52-week low after a 34% one-year fall. FY2029 targets Rs 1,090 / Rs 1,685 / Rs 2,390.
Vinati Organics: Five-Pillar Analysis
Good-to-moderate fit · 3 of 5 pass. Sunrise PARTIAL, Leadership PASS, Moat PASS, Iron Fortress PASS, Free Cash Flow PARTIAL. A 65% share niche monopoly, a completed father-to-daughter succession and a debt-free balance sheet, against a slow three-year growth record and free cash flow that turned negative in three of the last five years on expansion capex.
Control Print: Investment Report
63/100 Selective Positive. India's only home-grown coding and marking maker: 23,000+ printers installed, consumables above 60% of revenue, FY26 standalone PAT of Rs 80.3 cr and Rs 7 cr of borrowings against Rs 453 cr of net worth. The selective part is the gap to the group line: European subsidiaries cut consolidated FY26 PAT to Rs 43.6 cr, the group tax rate hit 40%, and Q1 FY27 growth slowed to 3.8%. FY2029 targets Rs 445 / Rs 850 / Rs 1,390.
Control Print: Five-Pillar Analysis
Moderate fit · 3 of 5 pass. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PARTIAL. A mandated-demand annuity, a stable 52.99% promoter holding with zero pledging and a fortress balance sheet, against a narrow moat versus three multinationals and operating cash flow flat at Rs 50 cr for three years.
MapmyIndia (C.E. Info Systems): Investment Report
68/100 Selective Positive. India's field-verified map monopoly: FY26 revenue of Rs 474.1 cr, an order book of Rs 1,754 cr at 3.7x revenue, Rs 685 cr of cash against Rs 7 cr of borrowings, and free cash flow positive every year. The selective part is the stall and the perimeter: FY26 revenue grew 2.3% with PAT down 9%, debtor days hit 136, Google cut India map API prices by up to 70%, and the 2024 consumer hive-off episode still prices a governance discount. FY2029 targets Rs 865 / Rs 1,600 / Rs 2,580.
MapmyIndia (C.E. Info Systems): Five-Pillar Analysis
Moderate fit · 3 of 5 pass. Sunrise PASS, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. A policy-routed sunrise, a fortress balance sheet and a five-year cash record, against a leadership grade held back by the promoter-venture pattern and a moat that is deep in cars and government but shallow on API price.
SentinelOne: The Cheapest Platform Standing
62/100 Selective Positive. The cheapest of the Gartner endpoint Leaders at ~6.1x forward sales (CrowdStrike ~32x), with ARR of $1.218B (+22%), non-GAAP operating margin inflected to +10%, AI security ARR tripling, and ~$1.9B of pro forma cash after the October 2026 convertible. The debits: deceleration, ~30% of revenue in stock comp, and a nearly new executive team. FY2029 targets $18 / $34 / $52.
SentinelOne: Five-Pillar Analysis
Moderate fit: 1 pass, 4 partial. Sunrise passes (AI expands the attack surface and the budget). Leadership, Moat, Iron Fortress, and Free Cash Flow are all partial for one shared reason: every structural element is mid-construction, the platform sub-scale, the fortress financed rather than earned, and the founder now leads a nearly new team.
Unicommerce eSolutions: Investment Report
61/100 Selective Positive. India's e-commerce middleware leader: about 1 bn order items annualised, FY26 revenue of Rs 204 cr, PAT of Rs 20.5 cr, free cash flow of Rs 45 cr, and Rs 92.6 cr of cash against about Rs 9 cr of borrowings. The selective part is the core inside the headline: Uniware grew about 13%, Shipway's courier mix cut consolidated gross margin from 69.4% to 54.2%, and FII and DII holdings are down to 0.02% and 2.38%. FY2029 targets Rs 45 / Rs 115 / Rs 210.
Unicommerce eSolutions: Five-Pillar Analysis
Moderate fit · 3 of 5 pass. Sunrise PASS, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. A structural niche, a fortress balance sheet and a real cash machine, against a buildable workflow moat, promoter dilution to 36.01%, and a near-total institutional exit from the register.
Solar Industries India: Investment Report
67/100 Selective Positive. India's explosives leader turned defence prime: FY26 revenue of Rs 9,838 cr, PAT of Rs 1,737 cr at a 28% operating margin, Q1 FY27 revenue up 70% with PAT up 89%, and an order book of Rs 21,350 cr. The selective part is the stack of prices paid: about 91x trailing earnings, negative FY26 free cash flow of Rs 1,072 cr, and a Rs 12,951 cr all-cash Omnia acquisition pending. FY2029 targets Rs 12,500 / Rs 23,500 / Rs 33,000.
Solar Industries India: Five-Pillar Analysis
Moderate fit · 2 of 5 pass. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PARTIAL, Free Cash Flow PARTIAL. A contracted defence sunrise and a 30-year leadership record, against a permissioned moat and two financial pillars spent on growth and the Omnia acquisition in the same year.
Hims & Hers: The Compounding King Goes Legit
64/100 Selective Positive. The GLP-1 war ended in the March 2026 Novo settlement: branded Ozempic and Wegovy at parity prices, the patent suit dismissed, and the bill arriving as a gross margin reset (74% to 64%), GAAP losses, and a July 2026 FTC suit over data sharing. Against that, 2.89M subscribers, revenue per subscriber up 21%, guidance raised twice, and ZAVA plus Eucalyptus taking international to 17% of revenue. FY2029 targets $12 / $48 / $100.
Hims & Hers: Five-Pillar Analysis
One pass, four partials. Sunrise passes (demand and policy both expand the market). Leadership is partial: elite creation and settlement craft against the $49 pill escalation, the FTC culture bill, and ~$191M of insider selling. Moat is partial: owned in the long tail, rented from Novo at the head. Iron Fortress and Free Cash Flow are partial.
TeraWulf: Power, Paper, and the Anthropic Bet
66/100 Selective Positive. Roughly 839 MW under long-term leases (Fluidstack under a ~$3.2B Google backstop, Core42, and Anthropic's direct 20-year, ~$19B lease) against 102 MW delivered, negative adjusted EBITDA, and $5.7B of debt on $147M of book equity. After a 61% drawdown the equity trades near replacement cost for its contracted MW, below Morgan Stanley's $17.50 bear case. FY2029 targets $6 / $18 / $32.
TeraWulf: Five-Pillar Analysis
One pass, two partials, two fails. Sunrise passes (powered land is the AI build-out's bottleneck). Leadership and Moat are partial. Iron Fortress fails on $5.7B of face debt against $147M of equity, and Free Cash Flow fails until delivered MW turns operating cash positive. The pillars grade the present; the verdict prices the contracts.
Kronox Lab Sciences: Investment Report
57/100 Neutral. The high purity fine chemicals maker at elite margins: FY26 revenue of Rs 101 cr, PAT of Rs 27.66 cr at a 34% operating margin, borrowings of Rs 1.61 cr, and free cash flow positive every year since FY20. The neutral part is everything around the plant: revenue compounded at 2% over three years, the founders sold 64.26% control to Indo Borax at Rs 103.22 per share in September 2026, and the stock has re-rated about 42% since. FY2029 targets Rs 115 / Rs 240 / Rs 395.
Kronox Lab Sciences: Five-Pillar Analysis
Partial fit · 2 of 5 pass. Sunrise PARTIAL, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. A fortress balance sheet and a cash machine attached to a slow growth niche, mid-transition: the two hardest pillars to fake pass cleanly, and the three that decide the next five years are open questions under new ownership.
Pidilite Industries: Investment Report
73/100 Selective Positive. The Fevicol franchise at full stretch: close to 70% share in white glue, FY26 revenue of Rs 14,601 cr, PAT of Rs 2,471 cr, free cash flow of Rs 2,239 cr, borrowings of Rs 417 cr, and a Q1 FY27 quarter with sales up 21.3% on 11.3% volume growth. The selective part is the price: about 57x trailing earnings, an imported VAM cost base, and paint majors attacking waterproofing. FY2029 targets Rs 1,250 / Rs 1,860 / Rs 2,375.
Pidilite Industries: Five-Pillar Analysis
Good fit · 4 of 5 pass. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. A fortress franchise whose single partial pillar sits exactly where the growth is: waterproofing and the pioneer categories the paint majors have chosen to contest.
Kothari Petrochemicals: Investment Report
64/100 Selective Positive. India's largest PIB maker: 48,000 MTPA, FY26 revenue of Rs 591 cr, PAT of Rs 72 cr, borrowings of about Rs 2 cr, and promoter holding of 72.22% with zero pledging, at about 9.8x earnings. The selective part is the perimeter: revenue flat for three years, a feedstock rating watch, and a pending merger with loss-making Kothari Sugars at one share for every five, with a vote on November 13, 2026. FY2029 targets Rs 85 / Rs 170 / Rs 275.
Kothari Petrochemicals: Five-Pillar Analysis
Partial fit · 2 of 5 pass. Sunrise PARTIAL, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. A debt-free, cash-converting PIB monopoly whose three partials are slow industry growth, feedstock dependence, and a leadership proposing to merge in a loss-making sugar business.
Bajaj Auto: Investment Report
74/100 Selective Positive. India's premium two-wheeler cash machine: record FY26 volumes above 5 million units, standalone PAT of Rs 9,825 cr, free cash flow above Rs 8,000 cr, and a dividend plus buyback equal to 100% of standalone PAT, alongside outright control of KTM. The selective part is the turnaround that came with KTM: consolidated borrowings of Rs 22,713 cr and a soft domestic September. FY2029 targets Rs 9,200 / Rs 12,900 / Rs 17,000.
Bajaj Auto: Five-Pillar Analysis
Moderate fit · 3 of 5 pass. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PARTIAL, Free Cash Flow PASS. A well-led cash compounder overweight premiumisation, electrification and exports, whose two partial pillars are the same story told twice: the KTM acquisition.
Qualcomm: Investment Report
75/100 Positive. Will the edge pay like the cloud did? HUMAIN 200MW, an Amazon custom silicon deal with warrants, auto at a $7B run rate, and the cheapest AI-adjacent multiple in large-cap semis, against a fiscal 2027 Apple air pocket. FY2029 targets $140 / $290 / $430.
Qualcomm: Five-Pillar Analysis
Four pass, one partial. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. A fortress cash machine whose moat has one named ceiling: Apple.
Frontier Springs: Investment Report
67/100 Selective Positive. The railway spring maker at full stretch: revenue tripled in three years to Rs 322 cr, PAT Rs 61 cr, a Rs 370 cr order book and debt to equity of 0.06, at about 27x earnings. The selective part is concentration: about 90% of production serves Indian Railways on fixed-price tenders, and FY26 operating cash flow was Rs 31 cr against PAT of Rs 61 cr. FY2029 targets Rs 970 / Rs 1,920 / Rs 2,890.
Frontier Springs: Five-Pillar Analysis
Moderate fit · 3 of 5 pass. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PARTIAL. A 45-year approval franchise in a structural railway sunrise, whose moat protects its vendor-list seat but not its margin, and whose growth finances itself out of working capital.
CAMS: Investment Report
76/100 Selective Positive. India's largest mutual fund registrar: 67.2% share of about Rs 56 lakh crore of serviced assets, mid-40s operating margins, FY26 free cash flow of about Rs 444 cr, and no promoter. The selective part is the FY26 stall (revenue +6.6%, PAT +1.6%) and 35x earnings, though that is a discount to KFin at about 41 to 44x. FY2029 targets Rs 560 / Rs 875 / Rs 1,225.
CAMS: Five-Pillar Analysis
Good fit · 4 of 5 pass. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. The folio base is close to immovable, but the moat protects volume, not price: yields compress 2.5 to 3.0% a year and regulators and AMCs hold the pricing pen.
Klarna Group: Investment Report
68/100 Selective Positive. Down 65% from its $40 IPO, Klarna trades at 1.3x guided sales against Affirm at 6.4x, with 120M consumers, $13B of deposits, transaction margin dollars up 42%, and a US bank charter pending. 2029 targets $11 / $42 / $78.
Klarna Group: Five-Pillar Analysis
One pass, three partial, one fail. Sunrise PASS, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PARTIAL, Free Cash Flow FAIL. Fortress-grade funding and a sunrise industry, priced as if the failing pillar were permanent.
Expleo Solutions: Investment Report
68/100 Selective Positive. The Indian arm of the Expleo Group: a debt-free BFSI tester with Rs 1,108 cr FY26 revenue, about Rs 353 cr net cash, and a Rs 110 per share dividend, at about 9.8x trailing earnings. The selective part is control: a 71.05% promoter and a live vote on Rs 2,800 cr a year of group lending. FY2029 targets Rs 740 / Rs 1,310 / Rs 2,060.
Expleo Solutions: Five-Pillar Analysis
Partial fit · 2 of 5 pass. Sunrise PARTIAL, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. A cash-generative, debt-free niche operator whose grades are capped by AI pressure on testing and a parent that decides what its cash is for.
Crisil: Investment Report
77/100 Selective Positive. India's first rating agency and an S&P Global company: about 30% operating margins, Rs 61 per share of dividends for calendar 2025, and H1 2026 revenue up 28.8% to Rs 2,133 cr. The selective part is price: about 36.6x trailing earnings versus ICRA at about 21x and CARE at about 26x. FY2029 targets Rs 3,480 / Rs 5,870 / Rs 8,700.
Crisil: Five-Pillar Analysis
Good fit · 4 of 5 pass. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. The moat is wide in domestic ratings (SEBI-regulated, 39 years of default data) and contestable in global analytics, where GenAI is the live test.
Gandhi Special Tubes: Investment Report
70/100 Selective Positive. The niche tube maker with a treasury: 40 years of precision steel tubes at 44% operating margins, zero debt, and a management that returned more cash than it earned in FY26 (Rs 15 dividend plus a Rs 78 cr buyback). The selective part: revenue compounded at only ~9% over five years, FY26 capex was Rs 2.2 cr, and the cash conversion cycle stretched to 341 days. FY2029 targets Rs 620 / Rs 1,100 / Rs 1,620.
Gandhi Special Tubes: Five-Pillar Analysis
Moderate fit · 3 of 5 pass. Sunrise PARTIAL, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. An honestly run precision niche with a fortress balance sheet and real cash generation, whose durability edge is proven but narrow and whose demand backdrop is cyclical. Moat upgrades on visible volume growth or debottlenecking capex.
Metro Brands: Investment Report
72/100 Selective Positive. India's 30%-margin footwear retailer: 1,041 stores across 222 cities, zero borrowings, 20%+ ROE, and a 70-year family name. The caveats: 1.6% same-store growth, falling revenue per sq ft, Q1 FY27 PAT down 3.6% on 14.7% revenue growth, ~25% of revenue on the licensed Crocs brand, and a 59.7x trailing P/E. FY2029 targets Rs 615 / Rs 1,100 / Rs 1,640.
Metro Brands: Five-Pillar Analysis
Good fit · 4 of 5 pass. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. A superbly run retailer in a structurally growing category whose durability edge is still being built: 1.6% same-store growth and ~25% Crocs concentration are the open questions. Back the rollout, demand the SSSG number every quarter.
Wealth First: Investment Report
71/100 Selective Positive. Ahmedabad's trail-commission compounder: 97% recurring revenue, 65-80% operating margins, zero debt, 74% promoter holding with zero pledging, Rs 13,647 cr AUA. The prop-trading noise is being wound to zero. Caveats: a related-party acquisition to verify, 33rd in MF distribution, thin float. FY2029 targets Rs 750 / Rs 1,650 / Rs 2,600.
Wealth First: Five-Pillar Analysis
Good fit · 4 of 5 pass. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. A well-led annuity in India's retail financialization whose moat is cultural and real but not yet structural. The WFAPL related-party deal is the monitored line item.
CDSL: Investment Report
75/100 Positive. India's retail market plumbing: 18.6 crore demat accounts, a two-thirds recurring annuity, zero debt, and a 58% dividend payout. FY26 was the reset year (PAT -14%, transaction flat five quarters); Q1 FY27 growth came back at 15.4%. But SEBI can rewrite tariffs again and NSDL is now listed and pushing retail. FY2029 targets Rs 1,120 / Rs 1,750 / Rs 2,350.
CDSL: Five-Pillar Analysis
Five of five pass. Sunrise PASS, Leadership PASS, Moat PASS, Iron Fortress PASS, Free Cash Flow PASS. A regulated toll road on India's retail financialization whose moat is legal and whose main risk is the regulator's pen. The 2022 cyber lapse is the owned leadership deduction.
Ondas Holdings
Selective Positive, with an integration watch · 62/100. The demand wave is real and the assets are genuine. The company is not yet one company. 2029 base target $12.00.
Ondas Holdings
Partial fit · 1 pass, 3 partial, 1 fail. Sunrise passes; management, moat, and fortress stay partial, and free cash flow fails until the acquisitions integrate.
Nautilus Biotechnology
Speculative Positive, with a funding watch · 62/100. Single-molecule proteoforms with digital counting and no direct competitor, against a two-year cash clock and a $125M ATM overhang. 2029 base target $3.50.
Nautilus Biotechnology
Partial fit · 2 pass, 2 partial, 1 fail. Sunrise and management pass; moat and fortress stay partial, and free cash flow fails until the platform commercializes.
Nitta Gelatin India: Investment Report
68/100 Selective Positive. A 50-year Indo-Japanese JV: pharma-grade gelatin credentials, a doubling collagen peptide bet, zero debt, and 74.5% promoter holding with no pledging ever. The catch: 20-24% margins sit far above CRISIL's 12-15% long-term band, so the stock is priced for peak-cycle margins. 2029 targets Rs 670 / Rs 1,750 / Rs 2,600.
Nitta Gelatin India: Five-Pillar Analysis
Three pass, two partial. Sunrise PARTIAL, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. A well-run niche franchise whose growth story (collagen peptides) is still being built and whose core industry is cyclical rather than structural.
Nebius Group
Positive, with a funding watch · 70/100. The fastest-scaling independent AI cloud on earth, sold out with pricing power, priced as if the $20-25B annual build funds itself flawlessly. 2029 base target $460.00.
Nebius Group
Partial fit · 2 pass, 2 partial, 1 fail. Sunrise and leadership pass; moat and fortress stay partial, and free cash flow fails until the build converts to cash.
BSE Ltd: Investment Report
76/100 Selective Positive. Asia's oldest exchange reborn as a derivatives machine: 68% operating margins, 46% ROE, premium-turnover share from near zero to about 27% since 2023. At 48x earnings with SEBI controlling the volume dial, back the business but be selective on the price. 2029 targets Rs 2,250 / Rs 3,950 / Rs 5,980.
BSE Ltd: Five-Pillar Analysis
Four of five pass. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. A superbly run toll booth whose durability edge belongs mostly to NSE and whose growth dial sits partly in the regulator's hands.
TajGVK Hotels & Resorts: Investment Report
68/100 Selective Positive. Seven Taj and Vivanta hotels, a net debt-free balance sheet, the Bengaluru expansion, and the one-fifth-of-the-company promoter pledge. FY26 was the best standalone year in company history, but the headline 4.8x P/E is an accounting artifact; the real multiple is 17-20x. 2029 targets Rs 260 / Rs 470 / Rs 650.
TajGVK Hotels & Resorts: Five-Pillar Analysis
Two pass, three partial. Sunrise PASS, Leadership PARTIAL, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PARTIAL. A good operating business in a structural sunrise whose compounder case is capped by the promoter pledge, a one-city moat, and a cash cycle mid-investment.
HDFC Asset Management Company: Investment Report
80/100 Positive. India's most profitable AMC since FY13, 80%+ operating margins, ~19% cost-to-income, zero debt, the most equity-skewed book among the giants, and the HDFC Bank channel at only 28%. Trading 21% below its high at 34x earnings, a discount to lesser peers. FY2029 targets Rs 1,850 / Rs 3,050 / Rs 4,400.
HDFC Asset Management Company: Five-Pillar Analysis
Four pass, one partial. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. The highest-quality franchise in Indian asset management, whose moat is the strongest in its industry and still being built.
EIH Associated Hotels: Investment Report
70/100 Selective Positive. Seven owned Oberoi/Trident hotels, zero debt, Rs 307.5 cr of surplus cash, and 31% margins at 20.6x earnings. FY26 was a down year and ~22% of revenue flows back to the promoter-operator; the FY27-28 catalyst stack must end the trough. 2029 targets Rs 235 / Rs 410 / Rs 635.
EIH Associated Hotels: Five-Pillar Analysis
Four pass, one partial. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. The moat is asset quality rather than scale, and independence is leased to the promoter-operator.
Benares Hotels: Investment Report
68/100 Selective Positive. Taj Ganges and Taj Nadesar Palace, a debt-free IHCL subsidiary with 42-44% operating margins, and the 100-room tower that must earn its keep. Q1 FY27 revenue up 31-35% on the new inventory, but PAT up only ~9%. 2029 targets Rs 7,400 / Rs 11,700 / Rs 17,300.
Benares Hotels: Five-Pillar Analysis
Four pass, one partial. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. The moat is one city wide, and the parent is adding competing supply there.
Cerebras Systems: Investment Report
68/100 Selective Positive. The largest AI chips on earth and the fastest measured inference, with a $25.4B contracted backlog anchored by OpenAI's $20B-plus agreement. But 86% of 2025 revenue came from two UAE-linked entities, the lockup expires November 10, 2026, and the stock trades at about 50x forward sales. 2029 targets $95 / $290 / $570.
Cerebras Systems: Five-Pillar Analysis
Two pass, two partial, one fail. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PARTIAL, Free Cash Flow FAIL. A genuine technology breakthrough in a structural sunrise that has not yet earned the right to be called a compounder.
Nippon Life India Asset Management: Investment Report
78/100 Positive. India's 4th-largest MF house and the fastest-growing top-10 AMC, with 66% operating margins, zero debt, a 90% dividend payout, and record 8.89% market share. But SEBI's 2026 TER cuts and ETF yield dilution are the live tests. FY2029 targets Rs 770 / Rs 1,325 / Rs 1,880.
Nippon Life India Asset Management: Five-Pillar Analysis
Four of five pass. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. A fortress-grade cash compounder in a structural industry, whose durability edge is thinner than its economics suggest.
Akamai Joins the Golden Trio
NVIDIA's Open Agent Safety Platform pairs OpenShell with Akamai Guardicore on BlueField-4 DPUs. NVIDIA, Palantir, and Akamai now co-build the agent-containment stack, and Akamai is the only member you can still buy cheap. Two layers: the simple version and the technical version.
Honasa Consumer: Investment Report
75/100 Positive. Mamaearth's parent, India's largest listed D2C beauty house, with two Rs 1,000 crore brands built in a decade, a survived Project Neev distribution crisis, zero debt, and the cheapest valuation among growth-priced peers. But Mamaearth is still 58% of revenue and HUL just bought Minimalist, the most direct rival. FY2029 targets Rs 310 / Rs 565 / Rs 890.
Honasa Consumer: Five-Pillar Analysis
Four of five pass. Sunrise PASS, Leadership PASS, Moat PARTIAL, Iron Fortress PASS, Free Cash Flow PASS. A well-led company in a strong industry with a fortress balance sheet, whose durability edge (the moat) is still being built. The HUL-Minimalist assault is the exam Honasa has not taken yet.
Bending Spoons: The Acquisition Machine
The layer the numbers can’t show: Ferrari’s ‘luck finds fit, skill operates it’ doctrine, every major deal from Evernote to Miro with terms and stated rationale, the Brightcove enterprise-video play, and the eight questions the strategy’s success hinges on.
Dutch Bros
Positive, with a competition watch · 74/100. A best-in-class operator with record unit economics, derated 48% while the business kept beating. 2029 base target $68.00.
Dutch Bros
Good fit · 4 of 5 pass. Sunrise, leadership, fortress, and FCF pass; the moat stays partial until transaction growth proves durable against 7 Brew.
Toast
Positive, on the location machine · 76/100. The best-integrated restaurant tech platform in America, compounding locations at 22%+, priced as if the compounding stops. 2029 base target $52.00.
Toast
Strong fit · 4 of 5 pass. Sunrise, leadership, moat, and fortress pass; FCF stays partial until the hardware drag clears.
Bending Spoons
Selective Positive · 65/100. The most interesting capital allocator to list in years, priced as if the compounding already happened. 2028 base target $31.00.
Bending Spoons
Partial fit · 3 of 5 pass. Leadership, execution moat, and cash flow pass; sunrise and fortress stay partial under the debt load.
Shakti Pumps: Investment Report
67/100 Selective Positive. India's largest listed solar-pump maker, riding the PM-KUSUM subsidy wave with in-house motors and four integrated plants. But 77% of revenue depends on government tenders, margins swung 840 bps in a year, and a Rs 1,700 crore solar-cell bet is unproven. At its 52-week low, the valuation has reset: FY2029 targets Rs 300 / Rs 1,000 / Rs 2,150.
Shakti Pumps: Five-Pillar Analysis
2 fails, 3 partials: not a compounder. Moat FAIL (L1 tenders, no pricing power) and Free Cash Flow FAIL (negative in 4 of 5 years). A well-run cyclical riding a policy window, not a buy-and-hold compounder. Treat as a tender-cycle position with a 12-18 month catalyst horizon.
Kirloskar Pneumatic: Investment Report
78/100 Positive. India's closest thing to a pure-play compressor champion: leader in CNG compression, record Rs 2,000 cr order inflow in FY26, net debt free, CRISIL AA. At 34.6x earnings it trades well below Elgi and Ingersoll-Rand. FY2029 targets Rs 528 / Rs 930 / Rs 1,296.
Kirloskar Pneumatic: Five-Pillar Analysis
3 PASS, 2 PARTIAL, 0 FAIL. Sunrise, balance sheet, and cash flow all pass on evidence. Leadership and moat are partial: a new MD six months into a family succession, and a moat deep in niches but narrow overall. A qualified fit: buy and verify, not buy and forget.
Havells India: Investment Report
74/100 Selective Positive. Two companies in one ticker: India's finest electrical-goods franchise and Lloyd, the AC business that lost Rs 203 crore in FY26. At Rs 1,040, down 30% from its high, the market has stopped paying the old 50x multiple. The franchise is excellent; the price is merely fair. FY2029 targets Rs 1,050 / Rs 1,730 / Rs 2,420.
Havells India: Five-Pillar Analysis
2 PASS, 3 PARTIAL: selective fit. Leadership and the iron-fortress balance sheet pass; sunrise, moat breadth, and cash conversion grade partial, entirely because of Lloyd and the investment cycle. Own the electricals thesis, demand Lloyd as a free option.
PubMatic
Positive · 76/100. The AI-native SSP at an inflection, priced like a turnaround. Founder-led, zero debt, FCF compounding; 2029 base target $39.00.
PubMatic
Good fit · 4 of 5 pass. Leadership, fortress, and FCF pass; sunrise and moat stay partial until double-digit growth proves durable.
Sprout Social
Selective Positive · 68/100. Near-breakeven SaaS at 1x sales, with the SBC wart shrinking. 2029 base target $23.00.
Sprout Social
Partial fit · 3 of 5 pass. Leadership, fortress, and FCF pass; sunrise and moat stay partial until Trellis drives ARPU.
Advanced Micro Devices
Selective Positive. FY2029 targets: bear $250 · base $690 · bull $970. Score 72/100.
Advanced Micro Devices
Three pass, two partial. Sunrise, Leadership and Iron Fortress pass; Moat improved on Helios conversion while Free Cash Flow weakened on the inventory build.
Meta Platforms
Positive, with a capex watch. FY2029 targets: bear $600 · base $1,150 · bull $1,550. Score 80/100.
Meta Platforms
Strong fit: 4 of 5 pillars pass. The audience, the ad flywheel, the leadership, and the fortress are genuine; the capex cycle owns the fifth.
Cisco Systems
Positive, with a margin watch. FY2029 targets: bear $80 · base $135 · bull $170. Score 70/100.
Cisco Systems
Solid fit: 3 of 5 pillars pass. The AI cycle is real, the cash is real; the moat and the fortress are the open questions.
CAVA Group
Positive. Chipotle-class unit economics at one-tenth the unit count, but a 92x multiple prices perfection. 12-month targets: bear $30 · base $85 · bull $120. Score 74/100.
CAVA Group: Five-Pillar Analysis
Moderate fit · 3 of 5 pillars pass. Sunrise PASS · Leadership PASS · Moat PARTIAL · Iron fortress PASS · Free cash flow PARTIAL.
Akamai x NVIDIA: The AI Grid Deep Dive
Six layers of NVIDIA's reference design, Akamai's first global-scale implementation, the NOC moat, and the $11.6B Anthropic economics. Genuine full-stack architecture; the open questions are deployment scale and diversification.
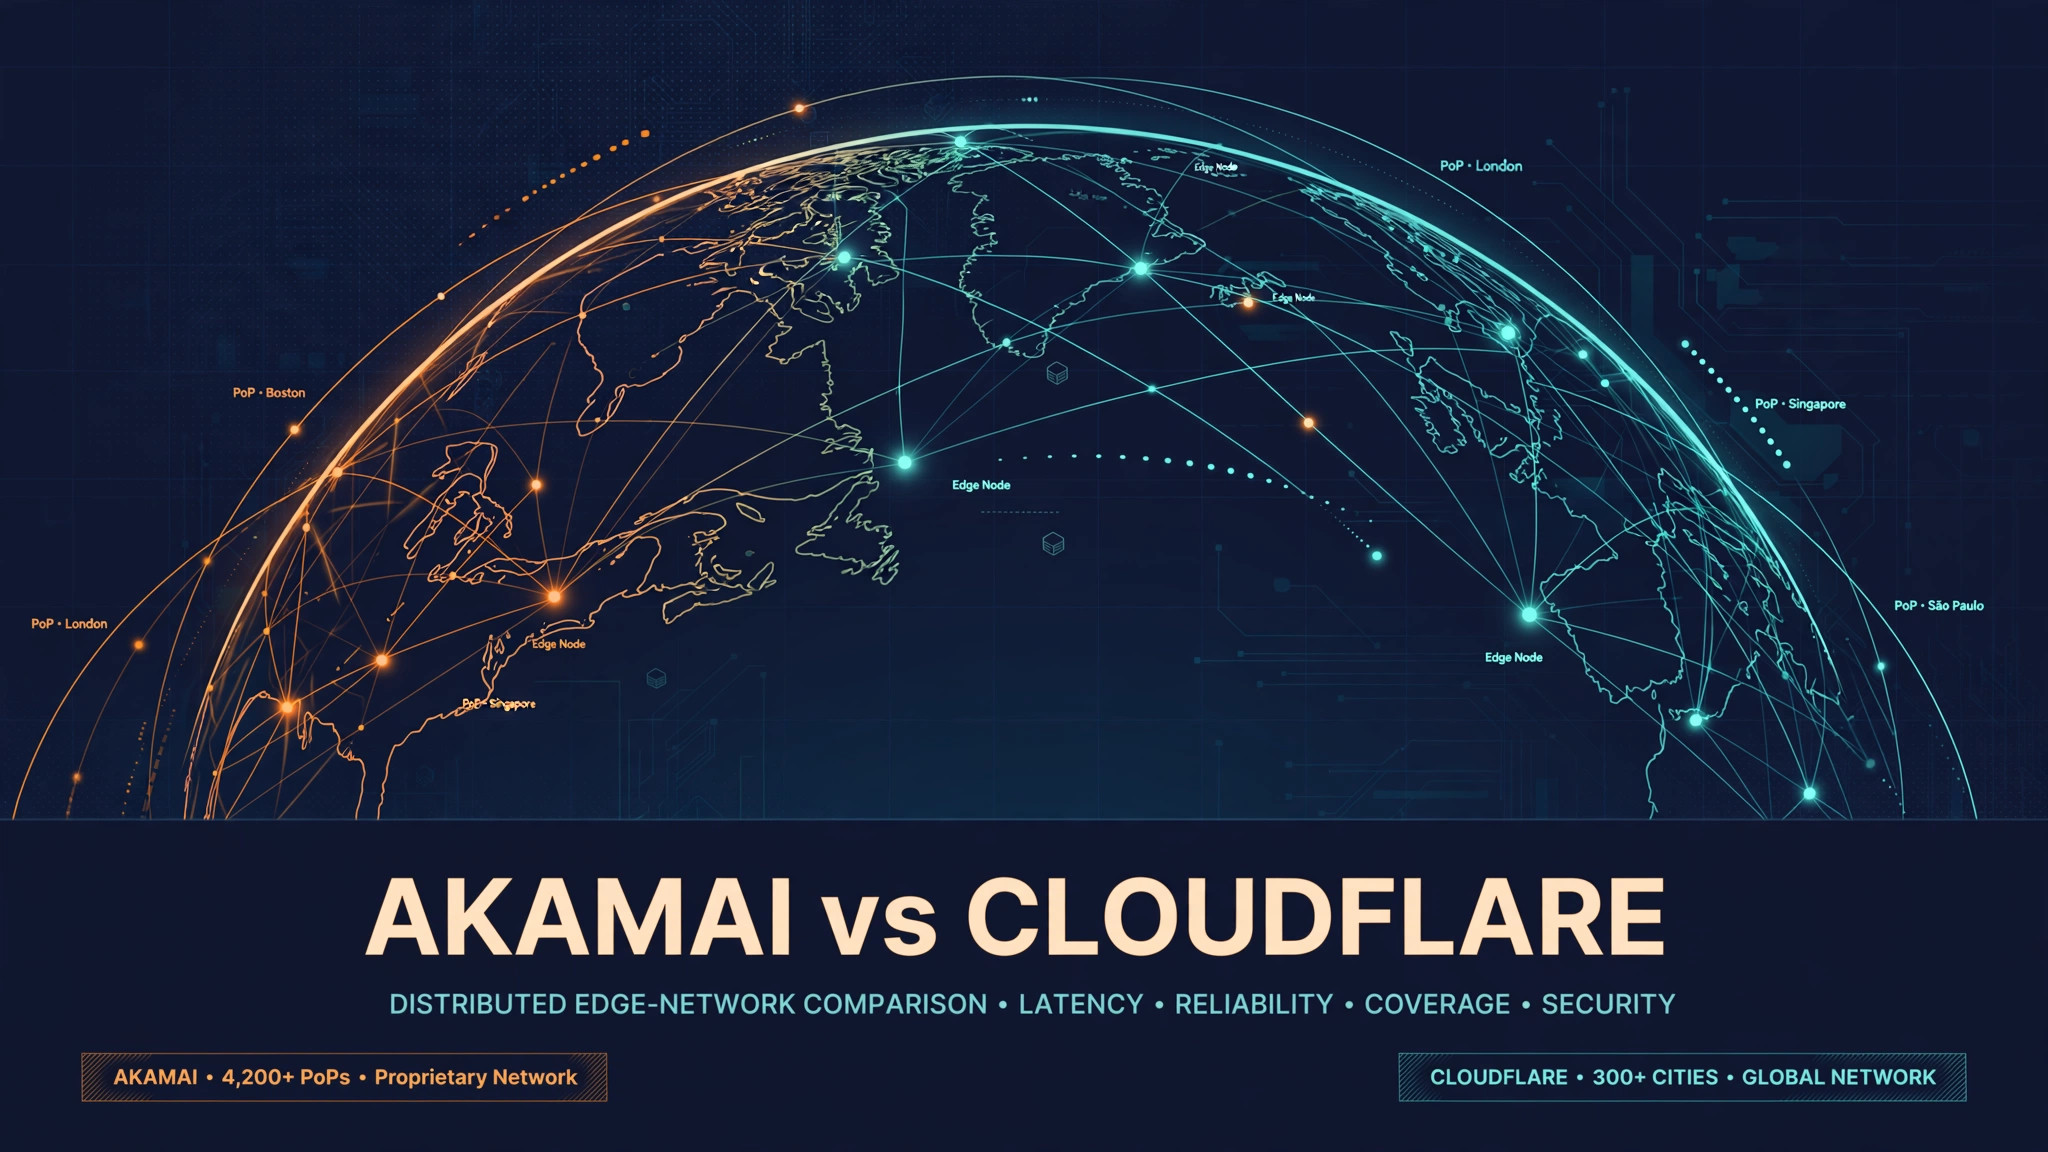
Akamai vs Cloudflare: Two Edges, One Scorecard
Ten dimensions, ten points each. Cloudflare takes growth and platform; Akamai takes profits, balance sheet, and price. Final: Akamai 78, Cloudflare 76.
Akamai: The Stewardship Report
Same cycle, different game. $14.4B of contracted backlog, 18.5% fewer shares than a decade ago, converts at 0% to 1.125%, and a buildout funded from operating cash flow, not dilution.
Akamai Technologies
Positive. The first inference cloud: 3 of 5 pillars pass; the $11.6B Anthropic deal validates distributed inference. 2028 scenarios: bear $95 · base $150-165 · bull $200+. Score 75/100.
Reliance Industries
Positive. A long-term compounder trading at its 52-week low. FY2029 targets: bear Rs 1,000 · base Rs 1,900 · bull Rs 2,800. Score 80/100.
Reliance Industries: Five-Pillar Analysis
Strong fit · 4 of 5 pillars pass. Sunrise PASS · Leadership PASS · Moat PASS · Iron fortress PASS · Free cash flow PARTIAL.
BlackBerry Q2 FY27 Earnings
Thesis intact and strengthening · 5 pass, 1 partial. Fifth consecutive triple beat; revenue $163.3M up 26%; guidance raised; Uber selects QNX for next-generation vehicles.
Unity Software
Positive. The turnaround is working; the price assumes the leverage story. FY2029 targets: bear $14 · base $57 · bull $93. Score 75/100.
Unity Software
Strong fit · 4 of 5 pillars pass. The engine is fixed, the ads business is compounding, and cash is real. Only the moat is partial.
Applied Digital
Positive, high-risk. Contracted AI growth on a levered balance sheet. 2029 base target $41.50. About $36B of 15-year take-or-pay leases against roughly $5B of debt.
Applied Digital
Partial fit · 1 pass, 2 partial, 2 fail. A sunrise backlog on a levered, cash-burning build. Sunrise passes; the balance sheet and free cash flow do not.
BlackBerry
Positive. Early-cycle turnaround, real moat. 2029 base target $13.50. QNX is the certified safety layer for physical AI, endorsed by NVIDIA on its own keynote stage.
BlackBerry
Strong engine fit · 5 of 5 pass. Sunrise, moat, fortress, cash flow, and leadership all qualify. A proven operator with an under-promise/over-deliver record.
Ola Electric
High-risk EV turnaround, below investment-grade quality. 2029 base target Rs 70 on the cell-integration option.
Ola Electric
Not a five-pillar fit · 1 pass, 1 partial, 3 fail. Sunrise sector and a real factory; failed leadership, fortress, and cash flow.
Grab Holdings
Selective Buy, evidence-gated · 74/100. A real profitable-growth platform, now carrying a harder capital-allocation and credit-underwriting test.
Grab Holdings
4 of 5 pillars pass. Platform, leadership, moat, and balance sheet qualify. Cash-flow quality still needs proof.
NXP Semiconductors
Attractive business recovery, incomplete technical confirmation. 2029 base target $420 on the edge-intelligence thesis.
NXP Semiconductors
Partial fit · 3 of 5 pass. Strong business; leadership too new and debt too high for a full engine fit.
PayPal
3 pass, 2 partial. A strong machine waiting for a new growth road.
Coverage Index
Every report on the site, grouped by ticker.
| Ticker | Company | Market | Report | Verdict | Published |
|---|---|---|---|---|---|
| AMD | Advanced Micro Devices | US | Investment Report | Selective Positive · 72/100 | Nov 4, 2026 |
| AMD | Advanced Micro Devices | US | Five-Pillar Analysis | Three pass, two partial · 72/100 | Nov 4, 2026 |
| AKAM | Akamai Technologies | US | AI Grid Deep Dive | Technical deep dive | Sep 26, 2026 |
| AKAM | Akamai Technologies | US | vs Cloudflare Comparison | Cloudflare takes growth; Akamai takes profit | Sep 25, 2026 |
| AKAM | Akamai Technologies | US | Stewardship Report | Same cycle, different game | Sep 25, 2026 |
| AKAM | Akamai Technologies | US | Five-Pillar Analysis | Positive · 3 of 5 pass | Sep 24, 2026 |
| APLD | Applied Digital | US | Investment Report | Positive, high-risk | Sep 23, 2026 |
| APLD | Applied Digital | US | Five-Pillar Analysis | Partial fit · 1 pass, 2 partial, 2 fail | Sep 23, 2026 |
| ARM | Arm Holdings | US | Investment Report | Neutral · 54/100 | Oct 29, 2026 |
| ARM | Arm Holdings | US | Five-Pillar Analysis | Moderate fit · 3 of 5 pass | Oct 29, 2026 |
| BB | BlackBerry | US | Q2 FY27 Earnings Report | Thesis intact · 5 pass, 1 partial | Sep 24, 2026 |
| BB | BlackBerry | US | Investment Report | Positive · base target $13.50 | Sep 23, 2026 |
| BB | BlackBerry | US | Five-Pillar Analysis | Strong engine fit · 5 of 5 pass | Sep 23, 2026 |
| BE | Bloom Energy | US | Investment Report | Neutral · 54/100 | Oct 29, 2026 |
| BE | Bloom Energy | US | Five-Pillar Analysis | Mixed fit · 1 of 5 pass | Oct 29, 2026 |
| CAVA | CAVA Group | US | Investment Report | Positive · 74/100 | Sep 27, 2026 |
| CAVA | CAVA Group | US | Five-Pillar Analysis | Moderate fit · 3 of 5 pass | Sep 27, 2026 |
| CBRS | Cerebras Systems | US | Investment Report | Selective Positive · 68/100 | Oct 5, 2026 |
| CBRS | Cerebras Systems | US | Five-Pillar Analysis | Partial fit · 2 pass, 2 partial, 1 fail | Oct 5, 2026 |
| CSCO | Cisco Systems | US | Investment Report | Positive, with a margin watch · 70/100 | Sep 27, 2026 |
| CSCO | Cisco Systems | US | Five-Pillar Analysis | Solid fit · 3 of 5 pass | Sep 27, 2026 |
| BFLY | Butterfly Network | US | Investment Report | Neutral · 52/100 | Oct 21, 2026 |
| BFLY | Butterfly Network | US | Five-Pillar Analysis | Weak-to-moderate fit · 1 pass, 3 partial, 1 fail | Oct 21, 2026 |
| BROS | Dutch Bros | US | Investment Report | Positive, with a competition watch · 74/100 | Oct 2, 2026 |
| BROS | Dutch Bros | US | Five-Pillar Analysis | Good fit · 4 of 5 pass | Oct 2, 2026 |
| BSP | Bending Spoons | US | Investment Report | Selective Positive · 65/100 | Oct 2, 2026 |
| BSP | Bending Spoons | US | Five-Pillar Analysis | Partial fit · 3 of 5 pass | Oct 2, 2026 |
| BSP | Bending Spoons | US | Acquisition Machine Deep Dive | Founder voices, every deal, the connecting strategy | Oct 2, 2026 |
| GRAB | Grab Holdings | US | Investment Report | Selective Buy · 74/100 | Sep 23, 2026 |
| GRAB | Grab Holdings | US | Five-Pillar Analysis | 4 of 5 pillars pass | Sep 23, 2026 |
| ENPH | Enphase Energy | US | Investment Report | Selective Positive · 58/100 | Nov 4, 2026 |
| ENPH | Enphase Energy | US | Five-Pillar Analysis | Moderate fit · 2 pass, 3 partial | Nov 4, 2026 |
| ABBOTINDIA | Abbott India | India | Investment Report | Selective Positive · 74/100 | Oct 21, 2026 |
| ABBOTINDIA | Abbott India | India | Five-Pillar Analysis | Good fit · 4 of 5 pass | Oct 21, 2026 |
| ASALCBR | Associated Alcohols and Breweries | India | Investment Report | Selective Positive · 64/100 | Oct 28, 2026 |
| ASALCBR | Associated Alcohols and Breweries | India | Five-Pillar Analysis | Weak to moderate fit · 1 of 5 pass | Oct 28, 2026 |
| ASIANPAINT | Asian Paints | India | Investment Report | Selective Positive · 65/100 | Oct 29, 2026 |
| ASIANPAINT | Asian Paints | India | Five-Pillar Analysis | Moderate fit · 2 of 5 pass | Oct 29, 2026 |
| BAJAJ-AUTO | Bajaj Auto | India | Investment Report | Selective Positive · 74/100 | Oct 14, 2026 |
| BAJAJ-AUTO | Bajaj Auto | India | Five-Pillar Analysis | Moderate fit · 3 of 5 pass | Oct 14, 2026 |
| BENARAS | Benares Hotels | India | Investment Report | Selective Positive · 68/100 | Oct 5, 2026 |
| BENARAS | Benares Hotels | India | Five-Pillar Analysis | Good fit · 4 of 5 pass | Oct 5, 2026 |
| BOSCHLTD | Bosch Ltd | India | Investment Report | Selective Positive · 67/100 | Oct 22, 2026 |
| BOSCHLTD | Bosch Ltd | India | Five-Pillar Analysis | Moderate-to-good fit · 3 of 5 pass | Oct 22, 2026 |
| BSE | BSE Ltd | India | Investment Report | Selective Positive · 76/100 | Oct 7, 2026 |
| BSE | BSE Ltd | India | Five-Pillar Analysis | Moderate fit · 4 of 5 pass | Oct 7, 2026 |
| CAMS | Computer Age Management Services | India | Investment Report | Selective Positive · 76/100 | Oct 13, 2026 |
| CAMS | Computer Age Management Services | India | Five-Pillar Analysis | Good fit · 4 of 5 pass | Oct 13, 2026 |
| CDSL | Central Depository Services (India) | India | Investment Report | Positive · 75/100 | Oct 8, 2026 |
| CDSL | Central Depository Services (India) | India | Five-Pillar Analysis | Good fit · 5 of 5 pass | Oct 8, 2026 |
| CONTROLPR | Control Print | India | Investment Report | Selective Positive · 63/100 | Oct 19, 2026 |
| CONTROLPR | Control Print | India | Five-Pillar Analysis | Moderate fit · 3 of 5 pass | Oct 19, 2026 |
| CRISIL | Crisil | India | Investment Report | Selective Positive · 77/100 | Oct 12, 2026 |
| CRISIL | Crisil | India | Five-Pillar Analysis | Good fit · 4 of 5 pass | Oct 12, 2026 |
| EIHAHOTELS | EIH Associated Hotels | India | Investment Report | Selective Positive · 70/100 | Oct 5, 2026 |
| EIHAHOTELS | EIH Associated Hotels | India | Five-Pillar Analysis | Good fit · 4 of 5 pass | Oct 5, 2026 |
| EXPLEOSOL | Expleo Solutions | India | Investment Report | Selective Positive · 68/100 | Oct 12, 2026 |
| EXPLEOSOL | Expleo Solutions | India | Five-Pillar Analysis | Partial fit · 2 of 5 pass | Oct 12, 2026 |
| FRONTSP | Frontier Springs | India | Investment Report | Selective Positive · 67/100 | Oct 13, 2026 |
| FRONTSP | Frontier Springs | India | Five-Pillar Analysis | Moderate fit · 3 of 5 pass | Oct 13, 2026 |
| GANDHITUBE | Gandhi Special Tubes | India | Investment Report | Selective Positive · 70/100 | Oct 9, 2026 |
| GANDHITUBE | Gandhi Special Tubes | India | Five-Pillar Analysis | Moderate fit · 3 of 5 pass | Oct 9, 2026 |
| HAVELLS | Havells India | India | Investment Report | Selective Positive · 74/100 | Oct 2, 2026 |
| HAVELLS | Havells India | India | Five-Pillar Analysis | Partial fit · 2 of 5 pass | Oct 2, 2026 |
| HDFCAMC | HDFC Asset Management Company | India | Investment Report | Positive · 80/100 | Oct 6, 2026 |
| HDFCAMC | HDFC Asset Management Company | India | Five-Pillar Analysis | Good fit · 4 of 5 pass | Oct 6, 2026 |
| HIMS | Hims & Hers Health | US | Investment Report | Selective Positive · 64/100 | Oct 15, 2026 |
| HIMS | Hims & Hers Health | US | Five-Pillar Analysis | Weak-to-moderate fit · 1 pass, 4 partial | Oct 15, 2026 |
| HOOD | Robinhood Markets | US | Investment Report | Selective Positive · 66/100 | Oct 28, 2026 |
| HOOD | Robinhood Markets | US | Five-Pillar Analysis | Moderate-to-good fit · 3 of 5 pass | Oct 28, 2026 |
| INDIAMART | IndiaMART InterMESH | India | Investment Report | Selective Positive · 71/100 | Oct 30, 2026 |
| INDIAMART | IndiaMART InterMESH | India | Five-Pillar Analysis | Moderate-to-good fit · 3 of 5 pass | Oct 30, 2026 |
| INGERRAND | Ingersoll Rand (India) | India | Investment Report | Selective Positive · 68/100 | Oct 27, 2026 |
| INGERRAND | Ingersoll Rand (India) | India | Five-Pillar Analysis | Moderate fit · 2 of 5 pass | Oct 27, 2026 |
| INTC | Intel | US | Investment Report | Negative · 47/100 | Oct 30, 2026 |
| INTC | Intel | US | Five-Pillar Analysis | Weak fit · 1 of 5 pass | Oct 30, 2026 |
| JAGSNPHARM | Jagsonpal Pharmaceuticals | India | Investment Report | Selective Positive · 62/100 | Oct 20, 2026 |
| JAGSNPHARM | Jagsonpal Pharmaceuticals | India | Five-Pillar Analysis | Moderate fit · 3 of 5 pass | Oct 20, 2026 |
| JENBURPH | Jenburkt Pharmaceuticals | India | Investment Report | Selective Positive · 65/100 | Oct 30, 2026 |
| JENBURPH | Jenburkt Pharmaceuticals | India | Five-Pillar Analysis | Weak to moderate fit · 1 of 5 pass | Oct 30, 2026 |
| JINDRILL | Jindal Drilling and Industries | India | Investment Report | Selective Positive · 62/100 | Oct 22, 2026 |
| JINDRILL | Jindal Drilling and Industries | India | Five-Pillar Analysis | Weak-to-moderate fit · 1 of 5 pass | Oct 22, 2026 |
| KENNAMET | Kennametal India | India | Investment Report | Selective Positive · 63/100 | Oct 28, 2026 |
| KENNAMET | Kennametal India | India | Five-Pillar Analysis | Weak-to-moderate fit · 1 of 5 pass | Oct 28, 2026 |
| KIRLPNU | Kirloskar Pneumatic Company | India | Investment Report | Positive · 78/100 | Oct 2, 2026 |
| KIRLPNU | Kirloskar Pneumatic Company | India | Five-Pillar Analysis | Good fit · 3 of 5 pass | Oct 2, 2026 |
| KOTHARIPET | Kothari Petrochemicals | India | Investment Report | Selective Positive · 64/100 | Oct 14, 2026 |
| KOTHARIPET | Kothari Petrochemicals | India | Five-Pillar Analysis | Partial fit · 2 of 5 pass | Oct 14, 2026 |
| KRONOX | Kronox Lab Sciences | India | Investment Report | Neutral · 57/100 | Oct 15, 2026 |
| KRONOX | Kronox Lab Sciences | India | Five-Pillar Analysis | Partial fit · 2 of 5 pass | Oct 15, 2026 |
| KSOLVES | Ksolves India | India | Investment Report | Selective Positive · 61/100 | Oct 21, 2026 |
| KSOLVES | Ksolves India | India | Five-Pillar Analysis | Weak-to-moderate fit · 1 of 5 pass | Oct 21, 2026 |
| HONASA | Honasa Consumer | India | Investment Report | Positive · 75/100 | Oct 3, 2026 |
| HONASA | Honasa Consumer | India | Five-Pillar Analysis | Good fit · 4 of 5 pass | Oct 3, 2026 |
| NAM-INDIA | Nippon Life India Asset Management | India | Investment Report | Positive · 78/100 | Oct 5, 2026 |
| NAM-INDIA | Nippon Life India Asset Management | India | Five-Pillar Analysis | Good fit · 4 of 5 pass | Oct 5, 2026 |
| NAUKRI | Info Edge (India) | India | Investment Report | Selective Positive · 68/100 | Oct 23, 2026 |
| NAUKRI | Info Edge (India) | India | Five-Pillar Analysis | Good fit · 4 of 5 pass | Oct 23, 2026 |
| KLAR | Klarna Group | US | Investment Report | Selective Positive · 68/100 | Oct 12, 2026 |
| KLAR | Klarna Group | US | Five-Pillar Analysis | Partial fit · 1 pass, 3 partial, 1 fail | Oct 12, 2026 |
| META | Meta Platforms | US | Investment Report | Positive, with a capex watch · 80/100 | Sep 28, 2026 |
| META | Meta Platforms | US | Five-Pillar Analysis | Strong fit · 4 of 5 pass | Sep 28, 2026 |
| NAUT | Nautilus Biotechnology | US | Investment Report | Speculative Positive, with a funding watch · 62/100 | Oct 7, 2026 |
| NAUT | Nautilus Biotechnology | US | Five-Pillar Analysis | Partial fit · 2 pass, 2 partial, 1 fail | Oct 7, 2026 |
| NBIS | Nebius Group | US | Investment Report | Positive, with a funding watch · 70/100 | Oct 7, 2026 |
| NBIS | Nebius Group | US | Five-Pillar Analysis | Partial fit · 2 pass, 2 partial, 1 fail | Oct 7, 2026 |
| NDRAUTO | NDR Auto Components | India | Investment Report | Selective Positive · 62/100 | Oct 27, 2026 |
| NDRAUTO | NDR Auto Components | India | Five-Pillar Analysis | Weak to moderate fit · 1 of 5 pass | Oct 27, 2026 |
| NFLX | Netflix | US | Investment Report | Positive · 72/100 | Oct 30, 2026 |
| NFLX | Netflix | US | Five-Pillar Analysis | Good fit · 4 of 5 pass | Oct 30, 2026 |
| NXPI | NXP Semiconductors | US | Investment Report | Attractive recovery, unconfirmed technically | Sep 22, 2026 |
| ONDS | Ondas Holdings | US | Investment Report | Selective Positive, with an integration watch · 62/100 | Oct 7, 2026 |
| ONDS | Ondas Holdings | US | Five-Pillar Analysis | Partial fit · 1 pass, 3 partial, 1 fail | Oct 7, 2026 |
| NXPI | NXP Semiconductors | US | Five-Pillar Analysis | Partial fit · 3 of 5 pass | Sep 22, 2026 |
| MAPMYINDIA | C.E. Info Systems (MapmyIndia) | India | Investment Report | Selective Positive · 68/100 | Oct 19, 2026 |
| MAPMYINDIA | C.E. Info Systems (MapmyIndia) | India | Five-Pillar Analysis | Moderate fit · 3 of 5 pass | Oct 19, 2026 |
| METROBRAND | Metro Brands | India | Investment Report | Selective Positive · 72/100 | Oct 9, 2026 |
| METROBRAND | Metro Brands | India | Five-Pillar Analysis | Good fit · 4 of 5 pass | Oct 9, 2026 |
| NITTAGELA | Nitta Gelatin India | India | Investment Report | Selective Positive · 68/100 | Oct 7, 2026 |
| NITTAGELA | Nitta Gelatin India | India | Five-Pillar Analysis | Partial fit · 3 of 5 pass | Oct 7, 2026 |
| OLAELEC | Ola Electric | India | Investment Report | High-risk EV turnaround | Sep 23, 2026 |
| OLAELEC | Ola Electric | India | Five-Pillar Analysis | Not a fit · 1 pass, 1 partial, 3 fail | Sep 23, 2026 |
| ORCL | Oracle Corporation | US | Investment Report | Selective Positive · 62/100 | Oct 28, 2026 |
| ORCL | Oracle Corporation | US | Five-Pillar Analysis | Weak-to-moderate fit · 2 of 5 pass | Oct 28, 2026 |
| PYPL | PayPal | US | Five-Pillar Analysis | 3 pass, 2 partial | Sep 22, 2026 |
| POLYCAB | Polycab India | India | Investment Report | Selective Positive · 73/100 | Oct 26, 2026 |
| POLYCAB | Polycab India | India | Five-Pillar Analysis | Moderate-to-good fit · 3 of 5 pass | Oct 26, 2026 |
| PAGEIND | Page Industries | India | Investment Report | Selective Positive · 67/100 | Nov 3, 2026 |
| PAGEIND | Page Industries | India | Five-Pillar Analysis | Moderate fit · 2 of 5 pass | Nov 3, 2026 |
| PIDILITIND | Pidilite Industries | India | Investment Report | Selective Positive · 73/100 | Oct 15, 2026 |
| PIDILITIND | Pidilite Industries | India | Five-Pillar Analysis | Good fit · 4 of 5 pass | Oct 15, 2026 |
| PUBM | PubMatic | US | Investment Report | Positive · 76/100 | Oct 1, 2026 |
| PUBM | PubMatic | US | Five-Pillar Analysis | Good fit · 4 of 5 pass | Oct 1, 2026 |
| QCOM | Qualcomm | US | Investment Report | Positive · 75/100 | Oct 14, 2026 |
| QCOM | Qualcomm | US | Five-Pillar Analysis | Strong fit · 4 pass, 1 partial | Oct 14, 2026 |
| RELIANCE | Reliance Industries | India | Investment Report | Positive · 80/100 | Sep 24, 2026 |
| RELIANCE | Reliance Industries | India | Five-Pillar Analysis | Strong fit · 4 of 5 pass | Sep 24, 2026 |
| SAKSOFT | Saksoft | India | Investment Report | Selective Positive · 66/100 | Oct 26, 2026 |
| SAKSOFT | Saksoft | India | Five-Pillar Analysis | Moderate fit · 2 of 5 pass | Oct 26, 2026 |
| SHAKTIPUMP | Shakti Pumps (India) | India | Investment Report | Selective Positive · 67/100 | Oct 2, 2026 |
| SHAKTIPUMP | Shakti Pumps (India) | India | Five-Pillar Analysis | Not a fit · 2 fail, 3 partial | Oct 2, 2026 |
| SIGMA | Sigma Solve | India | Investment Report | Neutral · 52/100 | Nov 5, 2026 |
| SIGMA | Sigma Solve | India | Five-Pillar Analysis | Weak fit · 1 of 5 pass | Nov 5, 2026 |
| SOLARINDS | Solar Industries India | India | Investment Report | Selective Positive · 67/100 | Oct 16, 2026 |
| SOLARINDS | Solar Industries India | India | Five-Pillar Analysis | Moderate fit · 2 of 5 pass | Oct 16, 2026 |
| STERTOOLS | Sterling Tools | India | Investment Report | Neutral · 56/100 | Oct 29, 2026 |
| STERTOOLS | Sterling Tools | India | Five-Pillar Analysis | Weak to moderate fit · 1 of 5 pass | Oct 29, 2026 |
| SYSTMTXC | Systematix Corporate Services | India | Investment Report | Neutral · 54/100 | Oct 23, 2026 |
| SYSTMTXC | Systematix Corporate Services | India | Five-Pillar Analysis | Weak-to-moderate fit · 2 of 5 pass | Oct 23, 2026 |
| TAJGVK | TajGVK Hotels & Resorts | India | Investment Report | Selective Positive · 68/100 | Oct 6, 2026 |
| TAJGVK | TajGVK Hotels & Resorts | India | Five-Pillar Analysis | Partial fit · 2 pass, 3 partial | Oct 6, 2026 |
| WEALTH | Wealth First Portfolio Managers | India | Investment Report | Selective Positive · 71/100 | Oct 8, 2026 |
| WEALTH | Wealth First Portfolio Managers | India | Five-Pillar Analysis | Good fit · 4 of 5 pass | Oct 8, 2026 |
| S | SentinelOne | US | Investment Report | Selective Positive · 62/100 | Oct 17, 2026 |
| S | SentinelOne | US | Five-Pillar Analysis | Moderate fit · 1 pass, 4 partial | Oct 17, 2026 |
| TSLA | Tesla | US | Investment Report | Neutral · 58/100 | Oct 22, 2026 |
| TSLA | Tesla | US | Five-Pillar Analysis | Moderate fit · 2 pass, 3 partial | Oct 22, 2026 |
| BSX | Boston Scientific | US | Investment Report | Selective Positive · 67/100 | Oct 21, 2026 |
| BSX | Boston Scientific | US | Five-Pillar Analysis | Moderate-to-good fit · 2 pass, 3 partial | Oct 21, 2026 |
| SOFI | SoFi Technologies | US | Investment Report | Selective Positive · 68/100 | Oct 21, 2026 |
| SOFI | SoFi Technologies | US | Five-Pillar Analysis | Moderate-to-good fit · 2 of 5 pass | Oct 21, 2026 |
| SPT | Sprout Social | US | Investment Report | Selective Positive · 68/100 | Oct 1, 2026 |
| SPT | Sprout Social | US | Five-Pillar Analysis | Partial fit · 3 of 5 pass | Oct 1, 2026 |
| TOST | Toast | US | Investment Report | Positive, on the location machine · 76/100 | Oct 2, 2026 |
| TOST | Toast | US | Five-Pillar Analysis | Strong fit · 4 of 5 pass | Oct 2, 2026 |
| U | Unity Software | US | Investment Report | Positive · 75/100 | Sep 24, 2026 |
| U | Unity Software | US | Five-Pillar Analysis | Strong fit · 4 of 5 pass | Sep 24, 2026 |
| UNIECOM | Unicommerce eSolutions | India | Investment Report | Selective Positive · 61/100 | Oct 16, 2026 |
| UNIECOM | Unicommerce eSolutions | India | Five-Pillar Analysis | Moderate fit · 3 of 5 pass | Oct 16, 2026 |
| VINATIORGA | Vinati Organics | India | Investment Report | Selective Positive · 70/100 | Oct 20, 2026 |
| VINATIORGA | Vinati Organics | India | Five-Pillar Analysis | Good-to-moderate fit · 3 of 5 pass | Oct 20, 2026 |
| WULF | TeraWulf | US | Investment Report | Selective Positive · 66/100 | Oct 15, 2026 |
| WULF | TeraWulf | US | Five-Pillar Analysis | Weak fit · 1 pass, 2 partial, 2 fail | Oct 15, 2026 |