Frequently asked questions
Is Ksolves India a buy at current prices?
DalalBytes rates Ksolves India Selective Positive at 61/100, a valuation and yield call rather than a compounder call. The founder-led IT services firm generated free cash flow of Rs 29 crore in FY26 and pays a 4.47% dividend yield at Rs 246.19, trading at 15.7x trailing earnings about 4% above its 52-week low. The selective part: PAT has been flat at Rs 34.3 crore for three fiscal years after operating margin reset from about 43% to about 30%, and FY27 guidance was cut after two top-10 clients ramped down.
What are Ksolves India's FY2029 price targets?
DalalBytes' FY2029 targets for Ksolves India are bear Rs 155, base Rs 305, and bull Rs 515, from a Rs 246.19 reference price. Bear: 4% revenue CAGR, 18.0% PAT margin, 11x exit. Base: 10% CAGR, 21.0% margin, 16x exit, EPS about Rs 19.2. Bull: 16% CAGR, 24.0% margin, 20x exit. FY2029 is the year ending March 2029.
Why did Ksolves cut its FY27 guidance?
In Q1 FY27, Ksolves cut FY27 revenue growth guidance from about 18 to 20% to flat to plus 4 or 5% after two large clients, both in its top 10, scaled down engagements late in the June 2026 quarter. The top 5 clients are about 40% of revenue and the top 10 about 53%, so two clients moving is enough to change the year. Management attributed the ramp-downs to client cost priorities and geopolitical uncertainty, guided EBITDA margin of 25 to 30%, and expected softness for two to three quarters.
What is the verdict on Ksolves?
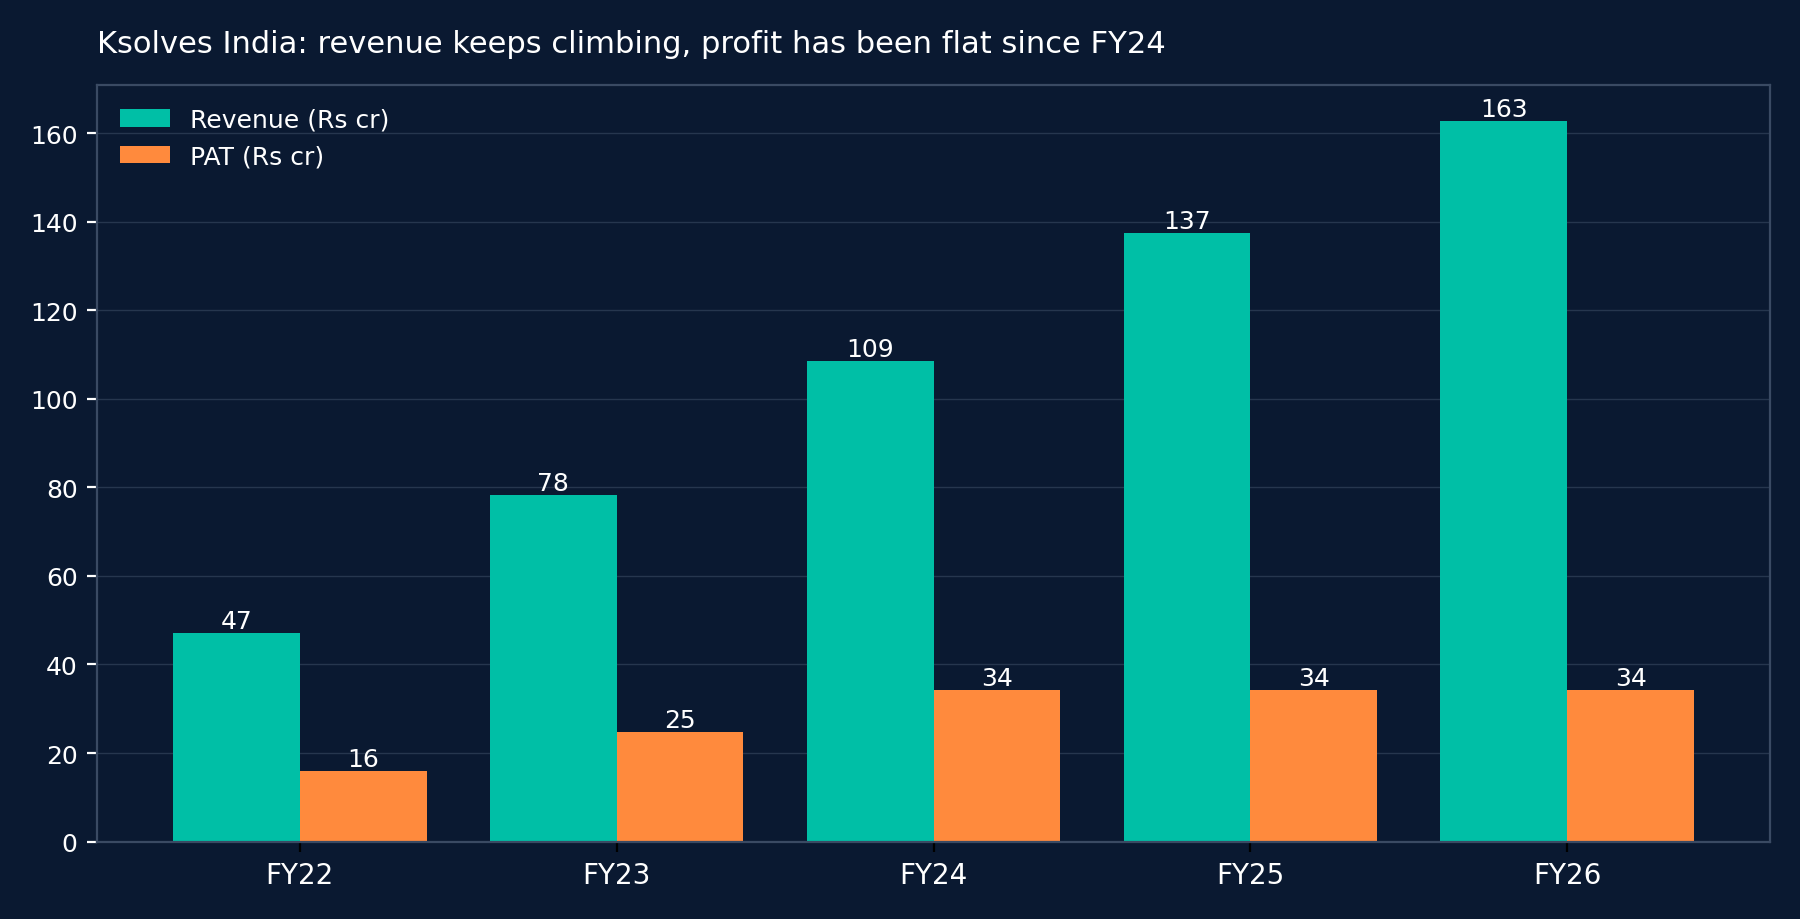
The economics are elite, the growth engine has stalled, and the price knows it. Revenue compounded at about 36% from FY22 to Rs 162.7 crore in FY26, but PAT was Rs 34.2 crore in FY24, Rs 34.3 crore in FY25 and Rs 34.3 crore in FY26, because operating margin reset from about 43% to about 30% as the company hired, paid ESOPs, spent on branding and events, and absorbed a failed product detour. Q1 FY27 showed both sides: guidance cut after two top-10 clients ramped down, and EBITDA margin recovering to 30.3% with PAT up 43.3% to Rs 9.21 crore. A USD 0.5 million agentic AI order from Demerara Bank (September 2026) is early proof the AI-first pivot can win paid work. At 15.7x trailing earnings with a 4.47% yield, the rating is Selective Positive at 61/100.
How did Ksolves start, and who owns it now?
Ratan Srivastava started the business in 2012 in Indirapuram as Kartik Solutions; the company was incorporated on July 17, 2014 and renamed Ksolves India. It listed on NSE Emerge in June 2020 at Rs 100 a share (raising Rs 4.02 crore), issued two bonuses in 2021, migrated to the main boards in September 2022, and split its shares in February 2025 to a Rs 5 face value. The promoter group (Ratan Kumar Srivastava, his wife Deepali Verma and family) held 58.92% in June 2026 with pledging at 0.00%: the holding stepped down from 68.01% in March 2021 to 58.94% by March 2023 and has been flat since.
What does Ksolves sell?
IT services in three balanced niches plus an AI wrapper. The latest disclosed mix (9M FY25) is Odoo 21.6%, Salesforce 21.4%, Big Data 20.9%, Open Source 18.4%, AI and ML 12.3%, Mobile 3.6% and QA 1.8% of revenue. Services were 98.3% of Q1 FY27 revenue; products (Data Flow Manager, Dashboard Ninja and about 70 Odoo apps) are 1.7% and being deprioritised under a services-only strategy. Geography is the hidden concentration: North America was 58.1% of FY26 revenue and 63% in Q1 FY27, India about a fifth, with more than 80% of revenue from repeat customers across about 200 clients. Delivery runs from Noida, Pune and Indore with about 600 professionals at roughly USD 25 to 49 an hour.
What happened to growth and guidance in 2026?
The Q1 FY27 reset is the most informative event in the file. Guidance given earlier in FY27 pointed to 18 to 20% revenue growth; after the June 2026 quarter (revenue up 10.0% YoY but down 3.7% sequentially to Rs 41.44 crore), management revised FY27 growth to flat to plus 4 or 5%, held an EBITDA margin band of 25 to 30%, and flagged softness for two to three quarters. Two top-10 clients caused it. The counter-evidence since: margin recovery to 30.3%, senior sales hires in North America, and the Demerara Bank agentic AI order of about USD 0.5 million over 7 months, a fixed-scope implementation for an existing client, filed on September 28, 2026 with no promoter interest and no related-party element.
What do the financials show?
Revenue of Rs 47.1 crore in FY22 rising to Rs 162.7 crore in FY26, with operating profit of Rs 20.1 crore rising to Rs 48.3 crore as margin fell from 42.8% to 29.7%, and PAT of Rs 15.9 crore rising to Rs 34.3 crore and then stopping: FY24, FY25 and FY26 all print Rs 34 crore. Free cash flow held a Rs 20 to 31 crore band for four years (Rs 29 crore in FY26, about 85% of PAT) on near-zero capex, with CFO to EBITDA conversion of 87 to 95%. The watch items are debtor days, back up to 70 in FY26 from 54 in FY24, and a balance sheet kept deliberately thin by payouts: net worth of about Rs 30 crore and cash of about Rs 7 crore at March 2026 (Rs 17 crore at June 2026 on company call reporting) against borrowings of Rs 6 crore.
Who runs Ksolves, and is governance clean?
Ratan Srivastava is founder, Chairman and Managing Director; Deepali Verma is Whole-time Director (she stepped down as CFO in February 2021 and professional CFO Umang Soni has run finance since March 2021); Manish Gurnani is CTO; four independent directors sit on the board. Positives are verifiable: zero pledging, no equity raises since the Rs 4 crore IPO, small disclosed ESOPs (2.5% pool), regular calls and presentations, a prompt guidance cut with a specific cause, and CRISIL BBB/Stable reaffirmed in December 2025 as reported in results coverage. Watch items: a family top table, marketing claims that run ahead of audited figures (an 89% global revenue line versus about 82% overseas revenue in Q1 FY27 disclosures), and an institutional register that has emptied out, with FII holding down from 1.87% in March 2024 to 0.01% in June 2026.
What is Ksolves worth?
At Rs 246.19: market cap about Rs 584 crore, 15.7x trailing EPS of Rs 15.65, 17.0x FY26 EPS of Rs 14.47, about 3.6x FY26 sales, EV to EBITDA estimated at about 11 to 12x, and a 4.47% dividend yield. Kellton Tech trades near 6.9x on seven times the revenue at thin margins, Saksoft near 14x, Happiest Minds near 22x and Persistent near 47 to 51x as the ceiling. Ksolves carries the highest margins in its set and the smallest scale, which is the whole argument in one line. FY2029 scenarios from FY26 revenue of Rs 163 crore: bear Rs 155 (4% CAGR, 18.0% margin, 11x), base Rs 305 (10% CAGR, 21.0% margin, 16x, EPS about Rs 19.2), bull Rs 515 (16% CAGR, 24.0% margin, 20x).
What are the key risks?
Concentration first, and it is realised, not theoretical: the top 5 clients are about 40% of revenue and the top 10 about 53%, and two of them cut guided FY27 growth by 13 to 15 points in one quarter. Then AI deflation (the wave Ksolves sells also compresses billable hours), margin drift below the guided band, North America at 58 to 63% of revenue with the forex and policy exposure that brings, founder key-man risk, and liquidity: about 22,650 shares traded on October 21, 2026, about Rs 56 lakh of value. Nearest-term: Q2 FY27 results on October 23, 2026, with a second interim dividend decision at the same board meeting.
© 2026 DalalBytes Research · For educational purposes only. Not investment advice.