
Frequently asked questions
Is Sigma Solve a buy at current prices?
DalalBytes rates Sigma Solve Neutral at 52/100. At Rs 40.77 the stock trades at 13.3x trailing earnings, but trailing profit includes Rs 8.97 cr of unexplained other income in one quarter. Excluding other income, core earnings are about Rs 2.2 a share and the multiple is about 18 to 19x, the top of its peer band.
What are Sigma Solve FY2029 price targets?
DalalBytes FY2029 targets for Sigma Solve are bear Rs 25, base Rs 48 and bull Rs 72, from a Rs 40.77 reference price. Bear: 2% sales CAGR to Rs 101 cr, PAT of Rs 19 cr, EPS of Rs 1.85 at 13.5x. Base: 11% CAGR to Rs 131 cr, PAT of Rs 28 cr, EPS of Rs 2.72 at 17.5x. Bull: 19% CAGR to Rs 161 cr, PAT of Rs 37 cr, EPS of Rs 3.60 at 20x.
What was the Rs 8.97 crore other income in Sigma Solve Q1 FY27?
In the June 2026 quarter, consolidated other income of Rs 8.97 cr exceeded operating profit of Rs 7.74 cr and made up 54% of profit before tax. About Rs 8.3 cr of it arose inside the US subsidiary or on consolidation, since standalone other income was only about Rs 0.68 cr. The company has not explained the item in any public summary, and it carries no exceptional label.
What is the verdict on Sigma Solve?
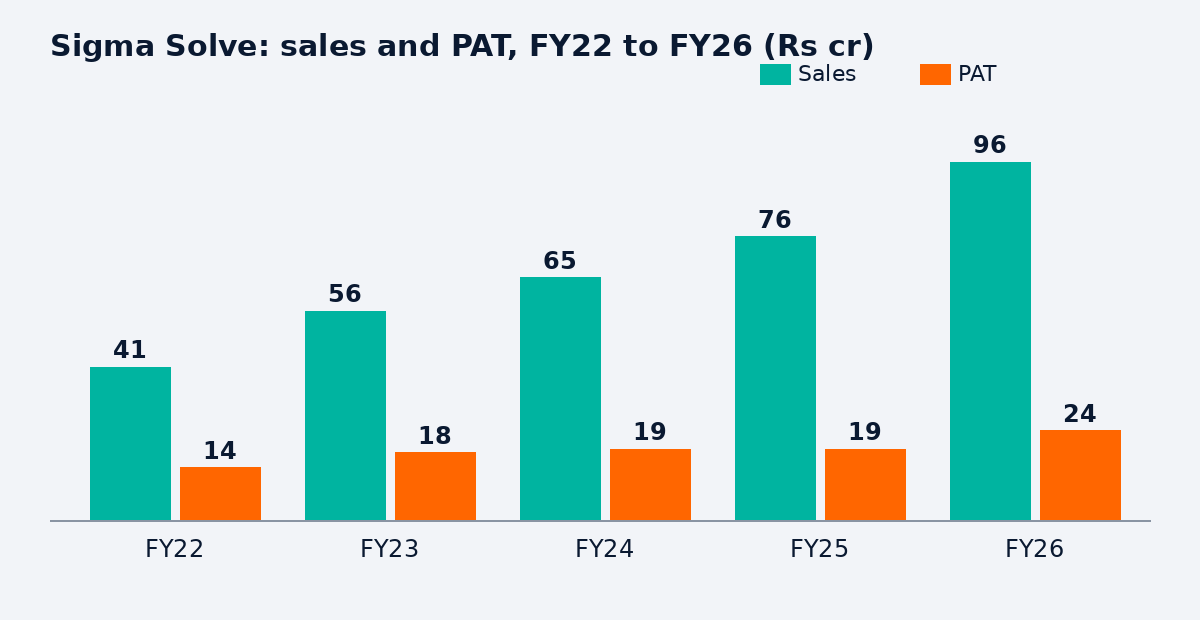
Sigma Solve is a genuinely profitable small IT services boutique. Consolidated sales rose from Rs 41 cr in FY22 to Rs 96 cr in FY26, operating margin held between 30% and 41%, borrowings are Rs 2.01 cr against net worth of Rs 77.07 cr, and promoters hold 73.21% with zero pledging. The problem is the trailing profit: Q1 FY27 other income of Rs 8.97 cr was 54% of profit before tax and is unexplained. On core EPS of about Rs 2.2 the stock trades at about 18 to 19x, the top of its peer band, with H1 FY27 sales up just 0.4%. Neutral.
How did Sigma Solve start, and who owns it now?
The US business came first in commercial terms: Sigma Solve Inc was floated in Florida by Biren Zaverchand, the promoters' son-in-law, and Prerak Parikh, the promoters' son. Prakash Parikh incorporated the Indian company in Ahmedabad in 2010 substantially as its delivery arm. The company listed on NSE Emerge in October 2020 at Rs 45, raising Rs 4.95 cr, and migrated to the mainboards on June 9, 2023. Prakash Parikh holds 20.80%, Kalpana Parikh 20.78%, and Pujan and Biren Zaverchand 15.81% each, within a promoter holding of 73.21% that has not moved in years, with pledging at zero.
What does the business actually do?
Sigma Solve sells IT services by the hour and by the project: custom enterprise applications and mobile apps, web and e-commerce development across Shopify Plus, nopCommerce and Magento, cloud work on AWS and Azure, data engineering and analytics, and Dynamics 365 and Salesforce implementations, plus design, digital marketing and testing. Its current positioning leads with AI: document AI, knowledge copilots and agentic workflow accelerators. A small plugin catalogue is sold from its own store and is immaterial. Delivery sits in Ahmedabad and in a Pune centre opened in September 2025, behind US front end offices in Sunrise, Florida and Atlanta.
Where does the revenue come from?
The company reports one segment and discloses no geography or client split. The structure supplies the split it withholds: standalone sales of the Indian parent were Rs 38.52 cr in FY26 against consolidated sales of Rs 95.62 cr, so about 60% of group revenue is booked by the US subsidiary. The company states that over 80% of revenue comes from referrals and partner introductions, and claims 378 plus clients and 1,260 plus projects delivered.
What do the financials show?
Sales went Rs 41 cr, Rs 56 cr, Rs 65 cr, Rs 76 cr, Rs 96 cr across FY22 to FY26, with operating margin of 37%, 41%, 35%, 34% and 30%, and PAT of Rs 14 cr, Rs 18 cr, Rs 19 cr, Rs 19 cr and Rs 24 cr. Margin compressed four straight years as employee cost rose faster than revenue. Then growth stopped: quarterly sales drifted from Rs 25.59 cr in September 2025 to Rs 23.03 cr and Rs 23.41 cr in FY27, and H1 FY27 sales of Rs 46.44 cr grew 0.4% year on year. The newest margin print is the bright spot, 36.4% operating margin in Q2 FY27, filed November 3, 2026.
What happened in the June 2026 quarter?
Other income of Rs 8.97 cr exceeded the entire operating profit of Rs 7.74 cr and made up 54% of profit before tax of Rs 16.48 cr. PAT rose 143% year on year to Rs 12.58 cr on sales up 11.5%. The same line was negative Rs 0.79 cr the quarter before and Rs 0.89 cr the quarter after. Standalone other income was only about Rs 0.68 cr, so roughly Rs 8.3 cr arose inside the US subsidiary or on consolidation. No public summary explains it and it carries no exceptional item label. Consolidated investments jumped from Rs 17 cr at March 2025 to Rs 39 cr at March 2026, which makes a fair value or sale gain the leading hypothesis, not an established fact.
How strong is the balance sheet and cash flow?
Net worth is Rs 77.07 cr at March 2026, borrowings Rs 2.01 cr, and investments Rs 39 cr, about half of net worth. Operating cash flow has been positive every year from FY21 to FY26 and reached Rs 30 cr in FY26, though that figure includes other income and the investing line swings with the treasury book, from minus Rs 31 cr in FY23 to plus Rs 36 cr in FY24. Debtor days blew out to 100 in FY25 before improving to 70 in FY26, implying receivables of roughly Rs 18 cr billed to US small and mid sized clients.
What is Sigma Solve worth versus peers?
At Rs 40.77: P/E 13.3x trailing on EPS of Rs 3.05, about 18 to 19x on core EPS of about Rs 2.2, P/B 5.4x on book value of Rs 7.50, yield 1.23%. The closest peer, Ksolves India, trades at Rs 211 and 13.9x with a market cap of Rs 501 cr, FY26 sales of Rs 163 cr, ROE of 137% and a 5.22% yield, and its Q2 FY27 revenue also fell. Saksoft trades at 13.4x on ten times the sales, and Kellton Tech at 6.9x on thirteen times the sales at an 11% margin. On core earnings Sigma Solve is the most expensive name in its own peer table. FY2029 scenarios: bear Rs 25, base Rs 48, bull Rs 72.
What are the key risks?
First, earnings quality: an unexplained line larger than operating profit sits inside trailing earnings, and if the investments book falls, the same line runs in reverse. Second, the growth pause meets AI exposure: the service mix of staff augmentation, web and app builds and testing is exactly what AI coding tools compress, and the AI response is unquantified. Third, undisclosed concentration: about 60% of revenue booked in the US, referral led sales, no client or contract disclosure, and debtor days that reached 100 once already. Fourth, the tape: a free float of about Rs 112 cr, average daily traded value of about Rs 71 lakh, institutions at 0.04% and a price 37% below its 52 week high.
© 2026 DalalBytes Research · For educational purposes only. Not investment advice.