
What is the five-pillar scorecard?
72/100. Selective Positive. Three pillars pass and two grade partial. The partials are still the two the valuation rides on, but they moved in opposite directions on November 3: Moat improved as Helios converted from systems in test to racks online at five named customers, and Free Cash Flow weakened as the ramp consumed $2.995B of inventory in a single quarter.
What would change the score. The score rises if the fourth quarter print shows free cash flow recovering toward $2.5B as the $11.463B inventory pile converts into shipped racks, and it falls if inventories build again beside another sub-$1B cash quarter, if a top anchor customer moves a chip generation to custom silicon, or if net cash turns to net debt.
| 72/100 | DalalBytes score |
| $483.90 | Reference price. November 3 2026 close |
| 3 of 5 | Pillars passing |
| $250 / $690 / $970 | Fiscal 2029 bear / base / bull |
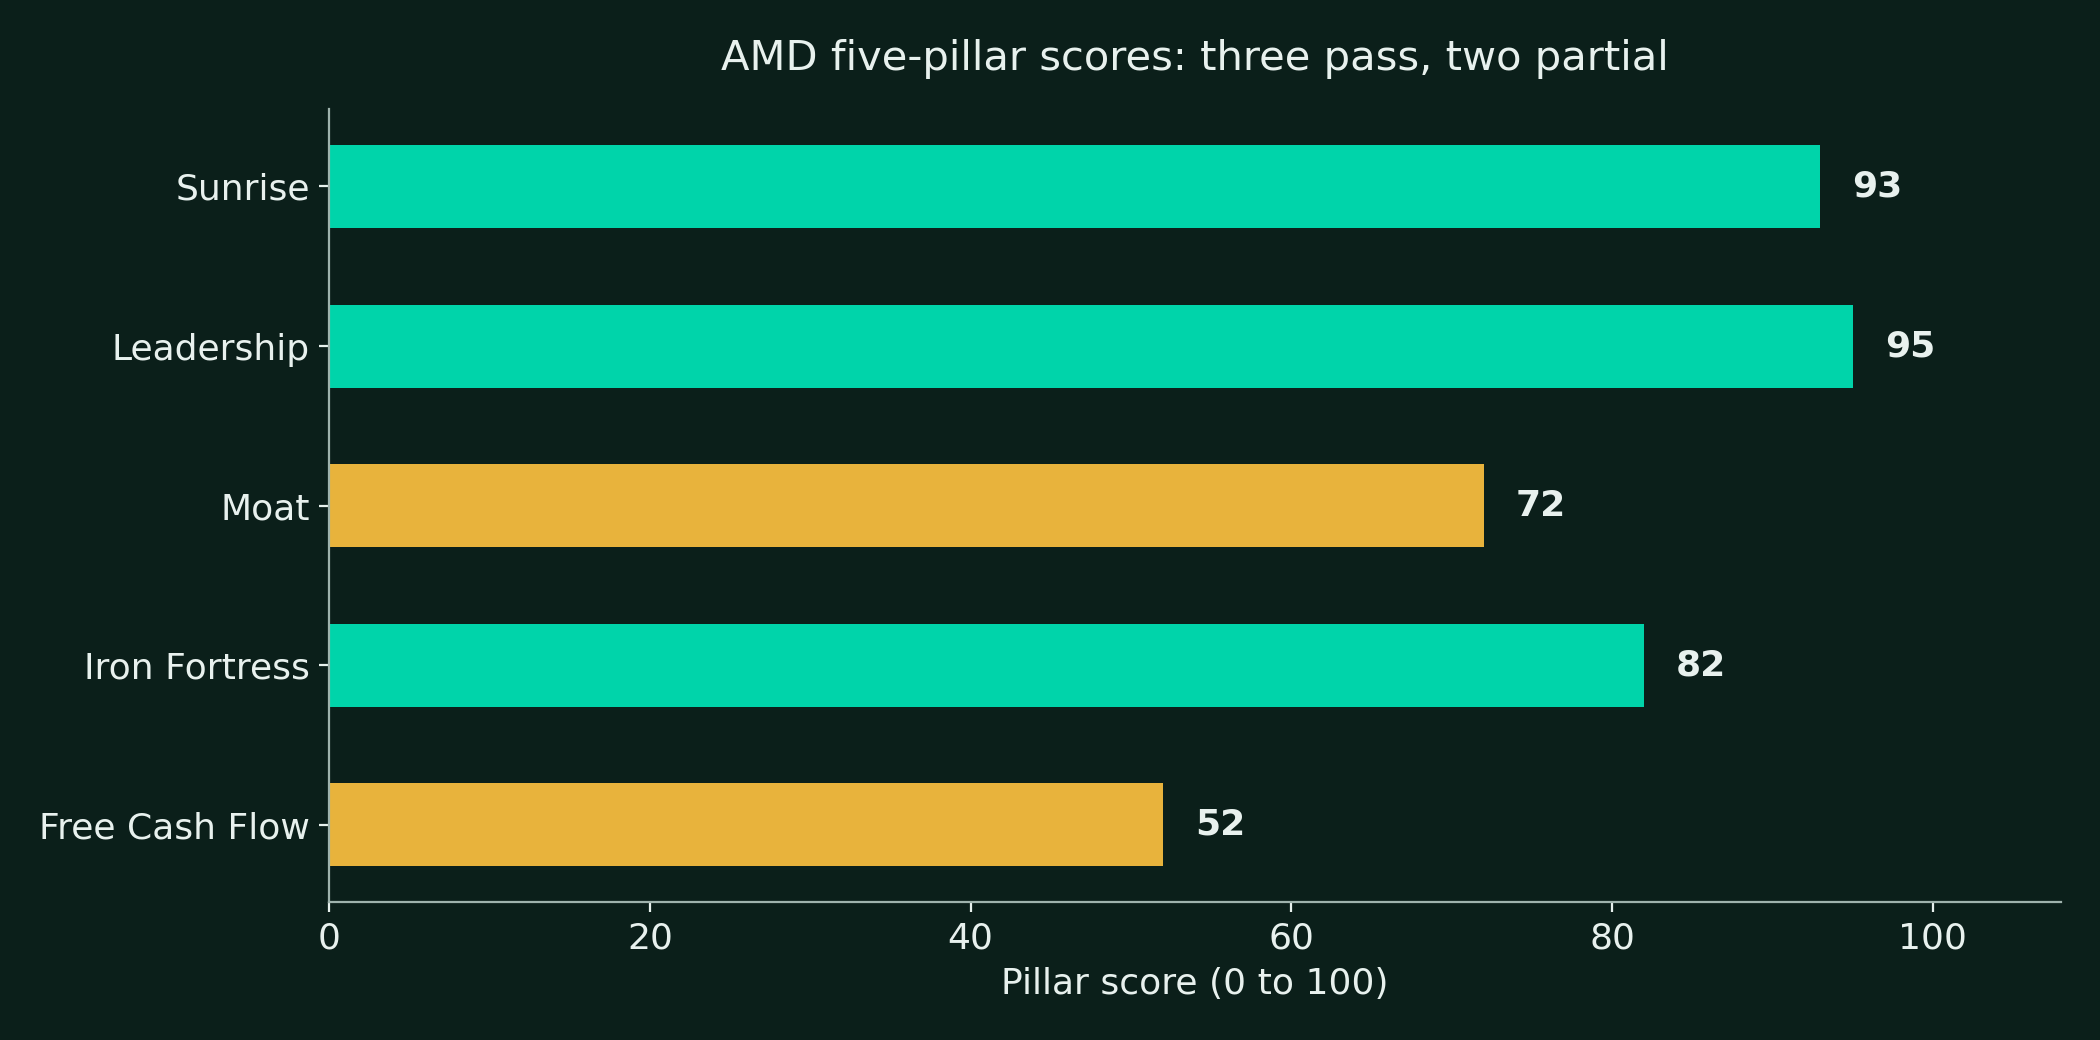
| Pillar | Grade | Score |
|---|---|---|
| 1. Sunrise | PASS | 93 |
| 2. Leadership | PASS | 95 |
| 3. Moat | PARTIAL | 72 |
| 4. Iron Fortress | PASS | 82 |
| 5. Free Cash Flow | PARTIAL | 52 |
| Total | 3 of 5 pass | 72 |
- The pillar scores grade business quality. The headline score then applies the price, which is why a company with this pillar profile scores 72 and not higher.
- The November 2, 2026 package scored the same business 68 at a $504.80 reference on Q2 2026 data. The companion report's verdict section explains what moved.
- Versus November 2 by pillar: Sunrise 90 to 93, Leadership 95 unchanged, Moat 68 to 72, Iron Fortress 80 to 82, Free Cash Flow 64 to 52.
- The score rose four points net: the roadmap conversion and the raised 2027 guide added more than the cash quarter and the warrant charge took away.
Pillar 1, Sunrise: why does it pass?
The sunrise question asks whether the industry is growing into the company's strengths, and November 3 strengthened the answer. Management now guides total revenue growth above 80% in 2027, more than double the growth rate in the long-term model set a year earlier, with Data Center passing 80% of revenue. The AI buildout needs exactly the two things AMD sells, host CPUs for every rack and a credible second source of accelerators, and for the first time the guide says the second source is the larger of the two.
- Data Center revenue grew 97% year over year in Q3 2026 to $8.546B, 64% of total revenue.
- Management guides 2027 revenue growth above 80%, with server revenue roughly doubling and data center AI revenue growing significantly more than double.
- Management guides data center AI revenue to pass server CPU revenue in Q4 2026 for the first time.
- Anchor commitments total up to 14 gigawatts across OpenAI, Meta, and Anthropic, and the first Helios systems are online at five named customers.
- Sovereign AI programs and neoclouds add demand beyond the four hyperscalers.
- Management said demand exceeds supply across wafers, substrates, advanced packaging, and memory, which caps this pillar below a perfect score rather than raising it.
- Downgrade trigger: a pause or cancellation wave in AI capex, or the gigawatt commitments converting at a small fraction of announced scale.
Pillar 2, Leadership: why does it pass?
This remains the strongest operator record in semiconductors, and Q3 2026 added the rarest item on it: a guide beaten and then raised in the same print. Lisa Su's team delivered revenue above the top of its own range, named the Helios ramps by customer instead of describing interest, quantified the 2027 outlook three ways, and explained the warrant accounting in plain terms on the call. The promises in the roadmap audit were set by the same team that kept the last ten, and the November promises are now the largest ones it has made.
- Revenue of $13,377M beat the top of the $12.7B to $13.3B guided range.
- The 2027 outlook was raised to revenue growth above 80%, from a long-term model that implied less than half that rate.
- Venice is shipping with more than 240 OEM and ODM platforms committed, about 20% more than Turin at the same stage.
- The board's March 2026 performance award for Su pays in full only if the stock reaches $600 by March 2031 with her in a full-time leadership role.
- The bench is named and stable: Forrest Norrod in data center, Jean Hu in finance, Mark Papermaster in technology.
- The Taalas and World Labs acquisitions, both guided to close by the end of 2026, add inference silicon and a chief scientist rather than revenue, which fits the pattern of buying capability ahead of need.
- Downgrade trigger: a Su departure, or a slipped Instinct generation that breaks the kept-promises record the pillar is grading.
Pillar 3, Moat: why only partial?
One half of this moat would pass on its own, and the other half moved without arriving. EPYC's position rests on process leadership, memory bandwidth, and an installed enterprise base that reorders by default, and it now shows up inside rivals' own platforms, with OpenAI hosting its first custom accelerator on Turin. Instinct crossed from promise to shipment in Q3: Helios racks online at five named customers, MI455X in mass shipment, and a guided Q4 where AI revenue passes CPU revenue. That is conversion. It is not yet lock-in, because AMD still publishes no Instinct dollar line, the anchor demand still carries warrants, and every anchor customer can still leave at a generation boundary.
- EPYC took 46.2% of x86 server CPU revenue in Q1 2026 on about a third of unit shipments.
- Venice pairs a 2nm process lead with 16 DDR5 memory channels. No Intel answer appears on a public roadmap through 2027.
- Helios systems are running models and workloads at Anthropic, Meta, Microsoft, OpenAI, and Oracle Cloud Infrastructure.
- Instinct's hardware counter is memory capacity: 432 GB of HBM4 per MI455X, 1.5 times the comparable NVIDIA Rubin figure AMD cites.
- The software counter is the inference abstraction layer in vLLM, SGLang, and Triton, which hides more of the CUDA difference each quarter, now with ROCm 10 shipped.
- The anchor deals were bought. OpenAI and Meta each hold warrants on 160M shares, and Anthropic holds a commitment of up to $5B of AMD capital.
- Two of the three anchor customers are building custom silicon programs of their own.
- Upgrade trigger: disclosed Instinct revenue showing conversion in dollars, or an independent frontier lab choosing ROCm as its first platform.
- Downgrade trigger: an anchor customer defecting to exclusivity elsewhere, or a chip generation moving to a customer's own silicon at an anchor account.
Pillar 4, Iron Fortress: why does it pass?
The fortress test is survival through a downturn, and AMD passes it with more room than the November package credited. The company closed the largest bond sale in its history in August 2026, repaid its 2026 notes in Q3, and still holds $15.776B of liquidity against $7.079B of debt, about $8.7B of net cash, with every maturity termed out from 2029 to 2036. The balance sheet funded a $2.995B inventory build in one quarter without borrowing a dollar of it short. The watch item remains direction: capital is flowing into customers, up to $5B for Anthropic and $1B into Meta's equity offering, and the warrant liabilities now remeasure through earnings each quarter.
- Cash, cash equivalents, and short-term investments were $15.776B at September 26, 2026, a record.
- Total debt at the same date was $7.079B, a net cash position of about $8.7B.
- The August 2026 notes run from 2029 to 2036 at coupons of 4.600% to 5.500%, and the $875M of 2026 notes were repaid in Q3.
- Interest expense of $62M in Q3 annualizes far below the CPU franchise's earnings power.
- Buyback authorization of roughly $10B is held largely unused, which is dry powder in a downturn.
- The warrant liabilities are non-cash until vesting, and management guides that dilution guidance follows in 2027.
- Downgrade trigger: net debt, or customer-financing commitments expanding from exceptions into a pattern.
Pillar 5, Free Cash Flow: why only partial?
This pillar fell twelve points in one quarter, and the numbers leave no softer reading. Free cash flow of $554M at a 4% margin, on record revenue of $13.377B, is the weakest conversion print of the AI run. Operating cash flow halved sequentially to $1.202B while inventories absorbed $2.995B and receivables $1.928B. Management's framing is coherent: the build funds a Q4 guide that steps Data Center revenue up about 50%, and payables funded part of it. A pillar framework grades conversion that has happened, though, and at roughly 119 times trailing free cash flow on the continuing basis, the price leaves no room for the build to miss its quarter.
- Trailing twelve-month free cash flow is about $6.76B on the continuing operations basis, down from $7.74B at June 2026.
- Fiscal 2025 free cash flow was $5.52B on the continuing basis against $1.12B in fiscal 2023.
- Q1 2026 set a quarterly record at $2.57B on the total company basis the November package headlined.
- Q3 2026 printed $554M, down from $1,558M in Q2 and $1,530M a year earlier.
- Inventories rose to $11.463B and accounts receivable to $9.209B in Q3 2026, while accounts payable rose to $7.756B.
- Capex fell sequentially to $648M from $808M, so the cash shortfall is a working capital story, not a capex story.
- Upgrade trigger: quarterly free cash flow back above $2.5B in a quarter where Helios revenue is visible.
- Downgrade trigger: another sequential free cash flow decline with inventories still building, which would move this pillar toward a fail.
Free cash flow basis
Free cash flow in this analysis is stated on a continuing operations basis. Trailing twelve-month free cash flow on that basis is about $6,760M and fiscal 2025 free cash flow was $5,519M. Total company figures include operating cash flow from the divested ZT Systems manufacturing business, reported in discontinued operations, and run higher. The November 2 analysis headlined the total company basis, and this analysis states the change of basis rather than blending the two.
What do the pillars miss?
The pillars grade the company. They do not grade reflexivity, and AMD's demand now carries it in the open. The OpenAI and Meta warrants vest partly on share-price thresholds, with the final Meta tranche tied to $600, and Q3 showed the mechanism working: a rising stock and rising vesting odds produced a $1.097B charge inside GAAP earnings on the best revenue quarter in company history. Success dilutes, and the dilution is largest exactly when the story works. The framework counts the warrants under Iron Fortress and capital structure. Their effect on the shape of the return, a governor on the upside rather than a threat to the downside, belongs in the scenario multiples, and it is one reason the base case exits at 30 times rather than higher.
The pillars also miss the calendar compression the 2027 guide created. A company guiding revenue growth above 80% with supply as the stated constraint is graded by a through-cycle framework as if the guide were a normal year. It is not. The Q4 2026 print now carries three dated tests at once: the 50% sequential Data Center step, the AI revenue crossover, and the conversion of an $11.463B inventory pile into cash. The headline score carries a wider error band than the pillar grades suggest, in both directions.
Frequently asked questions
Why did Free Cash Flow stay partial after a record revenue quarter?
Because the quarter converted profit into inventory instead of cash. Free cash flow was $554M at a 4% margin while inventories rose $2.995B to $11.463B and receivables rose $1.928B. The build funds the Helios ramp management guides to, but the pillar grades conversion that has happened, not conversion that is promised.
Why does Moat stay partial when Helios racks are online at five customers?
Because conversion is not yet lock-in. Helios systems running at Anthropic, Meta, Microsoft, OpenAI and Oracle prove AMD can ship racks, and Q4 should see AI revenue pass server CPU revenue. But AMD still discloses no Instinct dollar line, anchor demand still carries warrants, and customers can still leave at each generation boundary.
What single event moves this score the most from here?
The fourth quarter cash print. Data Center revenue near a 50% sequential jump is already guided and would confirm the ramp, but free cash flow recovering toward $2.5B as inventories convert would lift the weakest pillar and the score with it. Another sub-$1B cash quarter beside a bigger inventory pile cuts the score back toward the sixties.
Sources and disclosures
- Sources match the companion investment report: AMD Forms 10-K and 10-Q, the Q3 2026 results release of November 3, 2026, the Q3 2026 earnings call as transcribed in same-day coverage, the OpenAI, Meta, and Anthropic deal announcements, the August 2026 notes offering filings, Mercury Research share data, and Finnhub for the November 3, 2026 closing price.
- Pillar grades are DalalBytes judgments on the evidence in the companion report, not company disclosures.
- Disclosures: the author is long AMD. This analysis is research and opinion, not investment advice.