
What is the verdict on AMD?
72/100. Selective Positive. The score rises four points from the November 2 package because the pending half of the roadmap converted on November 3: Helios racks are online at five named customers, MI455X ships in volume, and the fourth quarter guide near $17B cleared the path the prior package required. The rise is capped at four points because free cash flow fell to $554M in the same quarter and a $1.097B warrant charge reached GAAP earnings.
What would change the score. The score rises if the fourth quarter print shows free cash flow recovering toward $2.5B as the $11.463B inventory pile converts into shipped racks, and it falls if inventories build again beside another sub-$1B cash quarter, if a top anchor customer moves a chip generation to custom silicon, or if net cash turns to net debt.
| 72/100 | DalalBytes score |
| $483.90 | Reference price. November 3 2026 close |
| $804B | Market cap at 1661M diluted shares |
| $250 / $690 / $970 | Fiscal 2029 bear / base / bull |
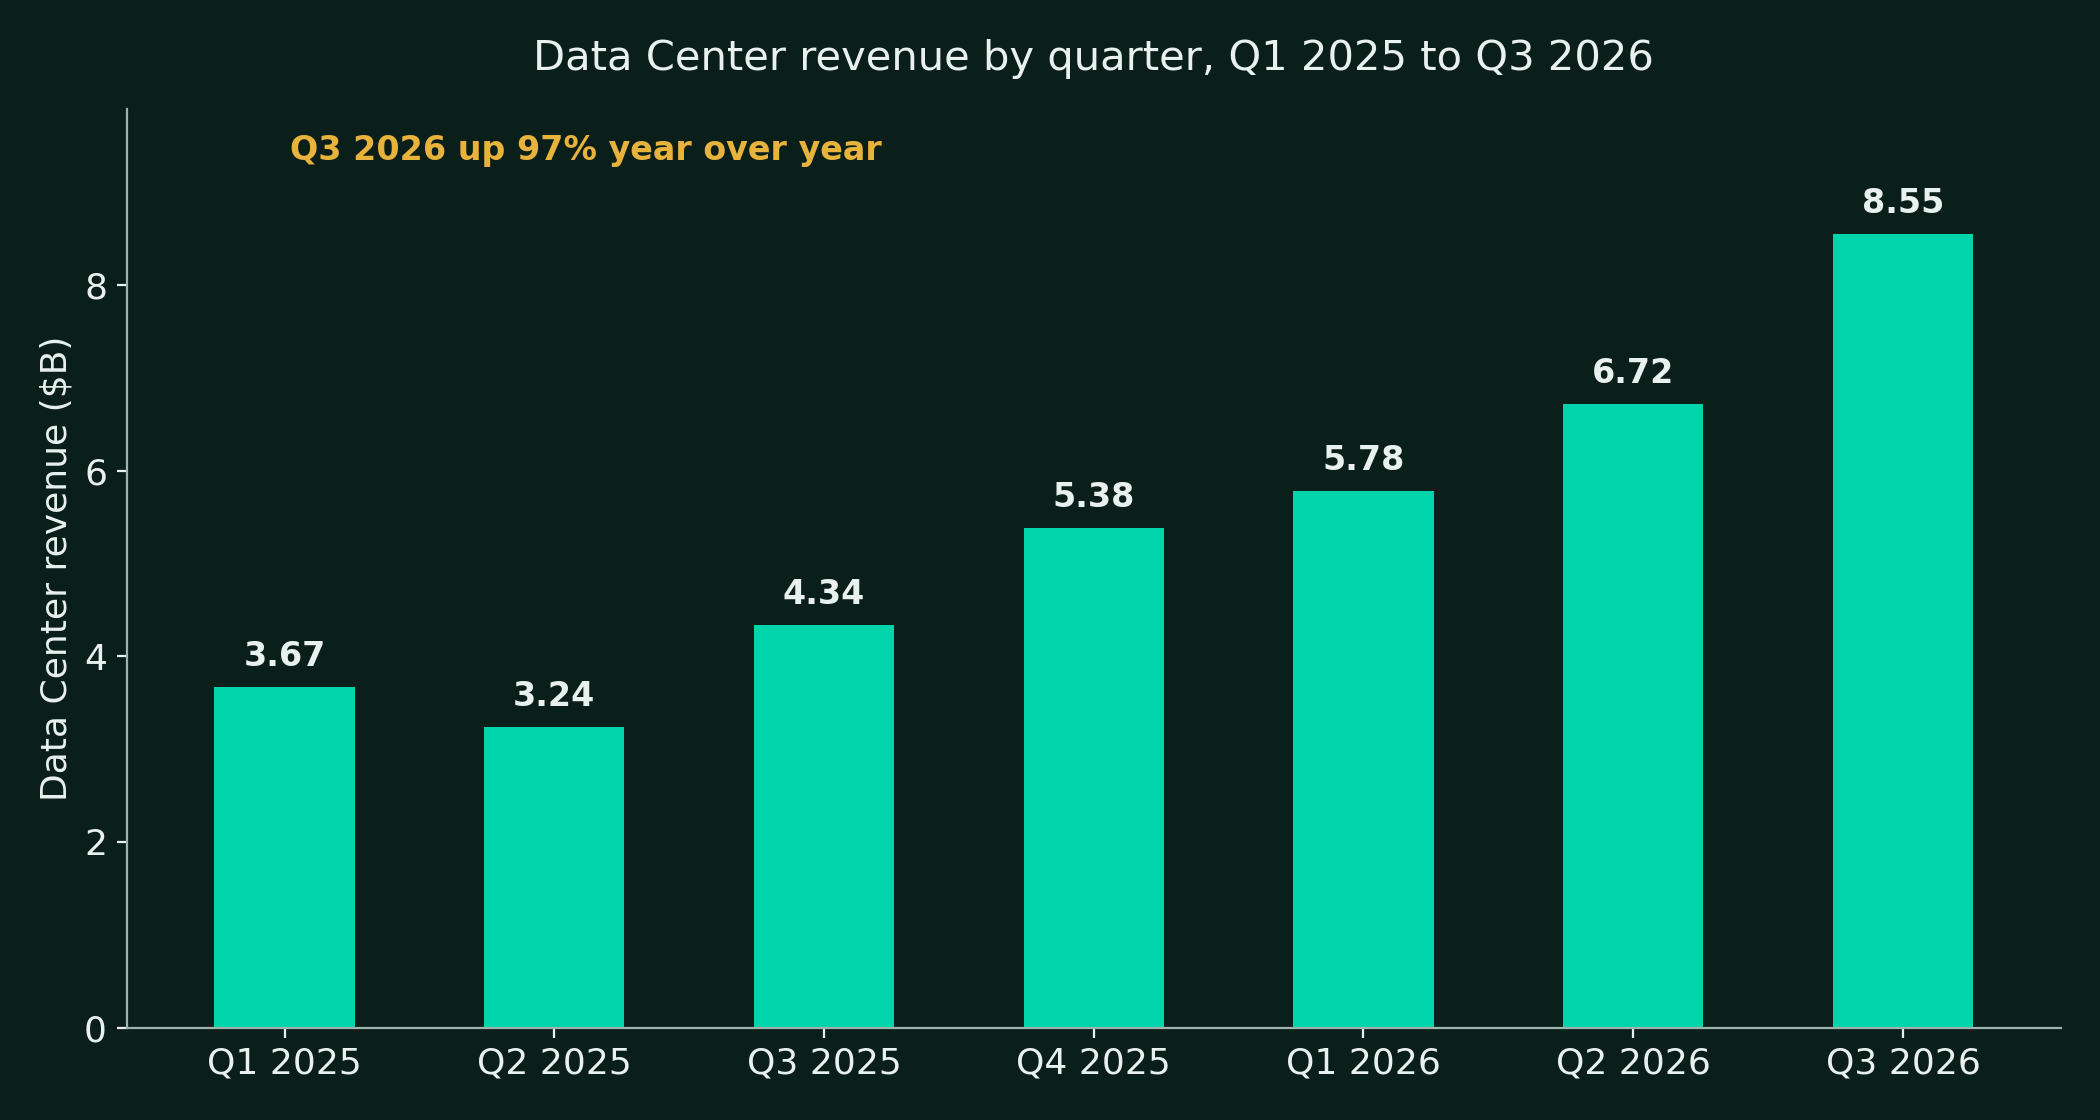
AMD is still two companies sharing one stock, but the second company changed character on November 3. The CPU franchise compounded again, with Data Center revenue up 97% year over year to $8.546B and segment operating margin widening to 33.7%. The accelerator challenger stopped being a promise and became a shipping system. Helios rackscale solutions are running models and workloads at Anthropic, Meta, Microsoft, OpenAI, and Oracle Cloud Infrastructure, HPE shipped the first Helios by HPE system through Vultr, and management guides fourth quarter Data Center revenue up about 50% sequentially with data center AI revenue passing server CPU revenue for the first time. A roadmap item that converts into named customers and a dated crossover is evidence, and the score pays for evidence.
What the score does not pay for is the way the quarter was financed inside the balance sheet. Inventories rose $2.995B in thirteen weeks to $11.463B, receivables rose $1.928B, and free cash flow printed $554M at a 4% margin on a record $13.377B of revenue. The warrant structure also stopped being theoretical. AMD remeasured its customer warrant liabilities and booked a $1.097B non-cash charge, $0.66 a share, which is why GAAP EPS of $1.46 trails non-GAAP EPS of $2.09 on the best revenue quarter in company history. At $483.90 the stock now prices a 2027 that management itself guides to more than 80% revenue growth. The guide can be believed and the price can still be full, and both are true here.
The price basis of this report
This report uses the Tuesday November 3, 2026 close of $483.90 throughout, sourced from Finnhub. The stock rose 3.65% in the regular session from the Monday close of $466.84 and rose further in after-hours trading once the release landed. This package is struck on Q3 2026 reported results, the November 3 earnings call, and the Q4 2026 and 2027 guidance issued with them. It supersedes the November 2, 2026 package, which scored AMD 68/100 at $504.80 on Q2 2026 data.
What changed versus November 2
Score 68 to 72. FY2029 scenarios rebuilt from $230 / $615 / $885 to $250 / $690 / $970 on the raised 2027 outlook. The Helios gate set by the November package, named ramps at named customers inside the Q4 guide, passed in full. The free cash flow gate in the same package, quarterly free cash flow back above $2.5B, failed in reverse, with Q3 printing $554M. Both facts are in the score.
What does AMD do?
Advanced Micro Devices is a fabless semiconductor company based in Santa Clara, California, founded in 1969 and listed on Nasdaq as AMD. Dr. Lisa Su has led the company since October 2014. AMD designs its chips and manufactures them at TSMC. It reports three segments: Data Center, Client and Gaming, and Embedded. The fiscal year is the calendar year, and the latest reported quarter is Q3 2026, which ended September 26, 2026.
| Metric | FY2024 | FY2025 | Q3 2026 |
|---|---|---|---|
| Total revenue ($M) | 25,785 | 34,639 | 13,377 |
| Data Center revenue ($M) | 12,579 | 16,635 | 8,546 |
| GAAP diluted EPS | $1.00 | $2.65 | $1.46 |
| Non-GAAP diluted EPS | $2.31 | $4.17 | $2.09 |
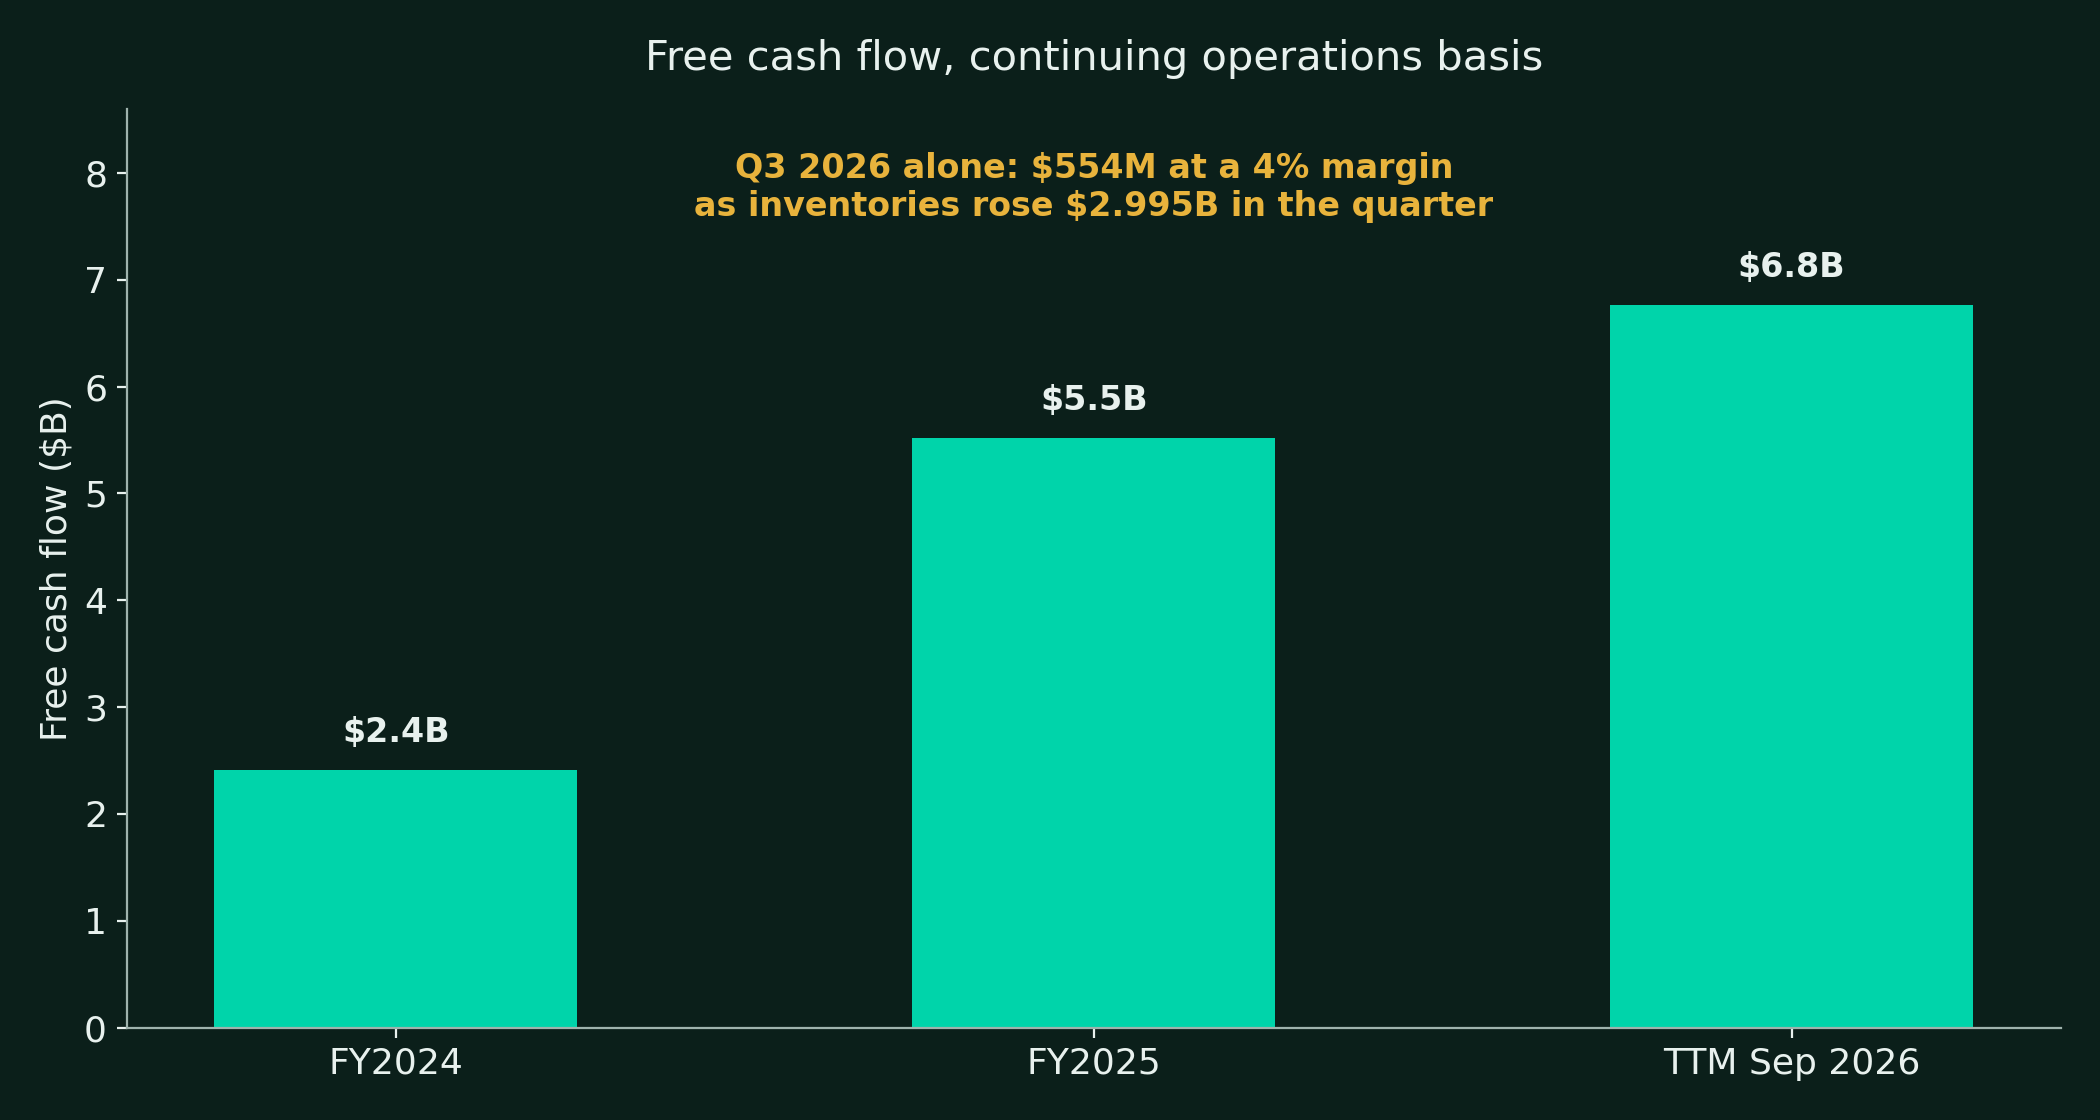
| Free cash flow ($M) | 2,405 | 5,519 | 554 |
Free cash flow basis
Free cash flow in this report is stated on a continuing operations basis unless a total company figure is named beside it. On that basis fiscal 2025 free cash flow was $5,519M. The November 2 package headlined total company figures that included $1,216M of discontinued operations cash flow from the divested ZT Systems manufacturing business. Trailing twelve-month free cash flow on the continuing basis is about $6.76B at September 26, 2026.
- Data Center was 29% of revenue in fiscal 2023 and 64% in Q3 2026.
- Diluted shares were 1661M in Q3 2026. Basic shares were 1632M at June 27, 2026.
- The company pays no dividend.
- AMD is the only merchant supplier fielding a full x86 CPU line, an AI GPU line, and data center networking in one portfolio.
- Every figure in this report traces to a filing, an earnings release, the earnings call, a deal announcement, or a named third-party source cited in section 17.
How is AMD's revenue built?
| Segment revenue ($M) | FY2023 | FY2024 | FY2025 | 9M 2026 |
|---|---|---|---|---|
| Data Center | 6,496 | 12,579 | 16,635 | 21,039 |
| Client | 4,651 | 7,054 | 10,640 | 8,896 |
| Gaming | 6,212 | 2,595 | 3,910 | 2,272 |
| Embedded | 5,321 | 3,557 | 3,454 | 2,959 |
| Total | 22,680 | 25,785 | 34,639 | 35,166 |
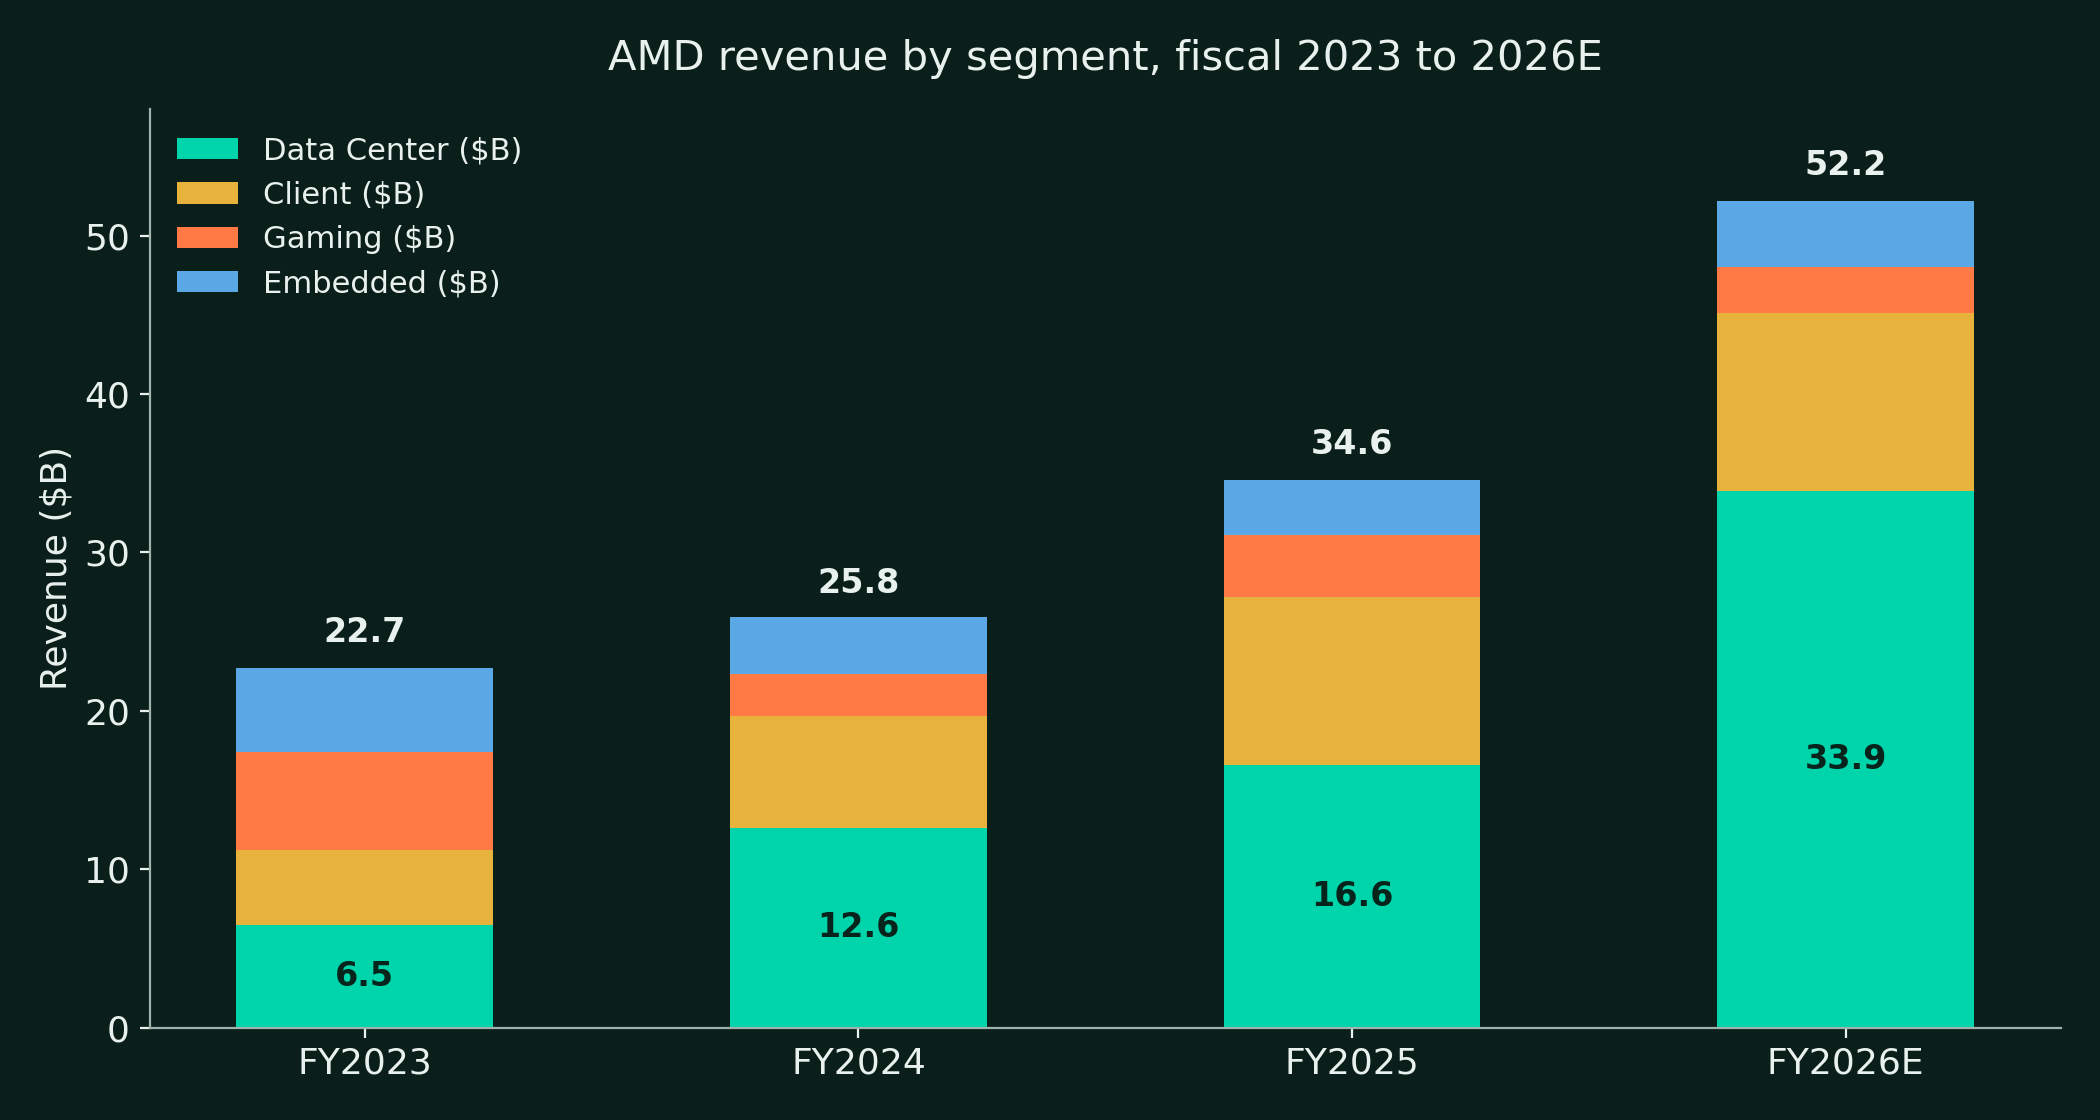
- Data Center revenue grew 94% in fiscal 2024 and 32% in fiscal 2025, then grew 97% year over year in Q3 2026 alone.
- Q3 2026 revenue of $13,377M beat the top of the company guide of $13.3B by $77M.
- Client revenue more than doubled from its fiscal 2023 trough of $4.7B to $10.6B in fiscal 2025, then grew 7% year over year in Q3 2026.
- Gaming revenue fell 40% year over year in Q3 2026 to $773M on lower semi-custom and graphics revenue.
- Embedded revenue rose 29% year over year in Q3 2026 to $1,109M, its fourth straight quarter of accelerating growth.
- The Q4 2026 guide is revenue of about $17B plus or minus 3% at a non-GAAP gross margin of about 55%.
- Management guides Data Center revenue up about 50% sequentially in Q4, Client and Gaming down more than 20%, and Embedded up double digits.
- On the November 3 call management guided 2027 revenue growth above 80%, with Data Center passing 80% of total revenue.
How do EPYC and Instinct compare inside Data Center?
EPYC server CPUs
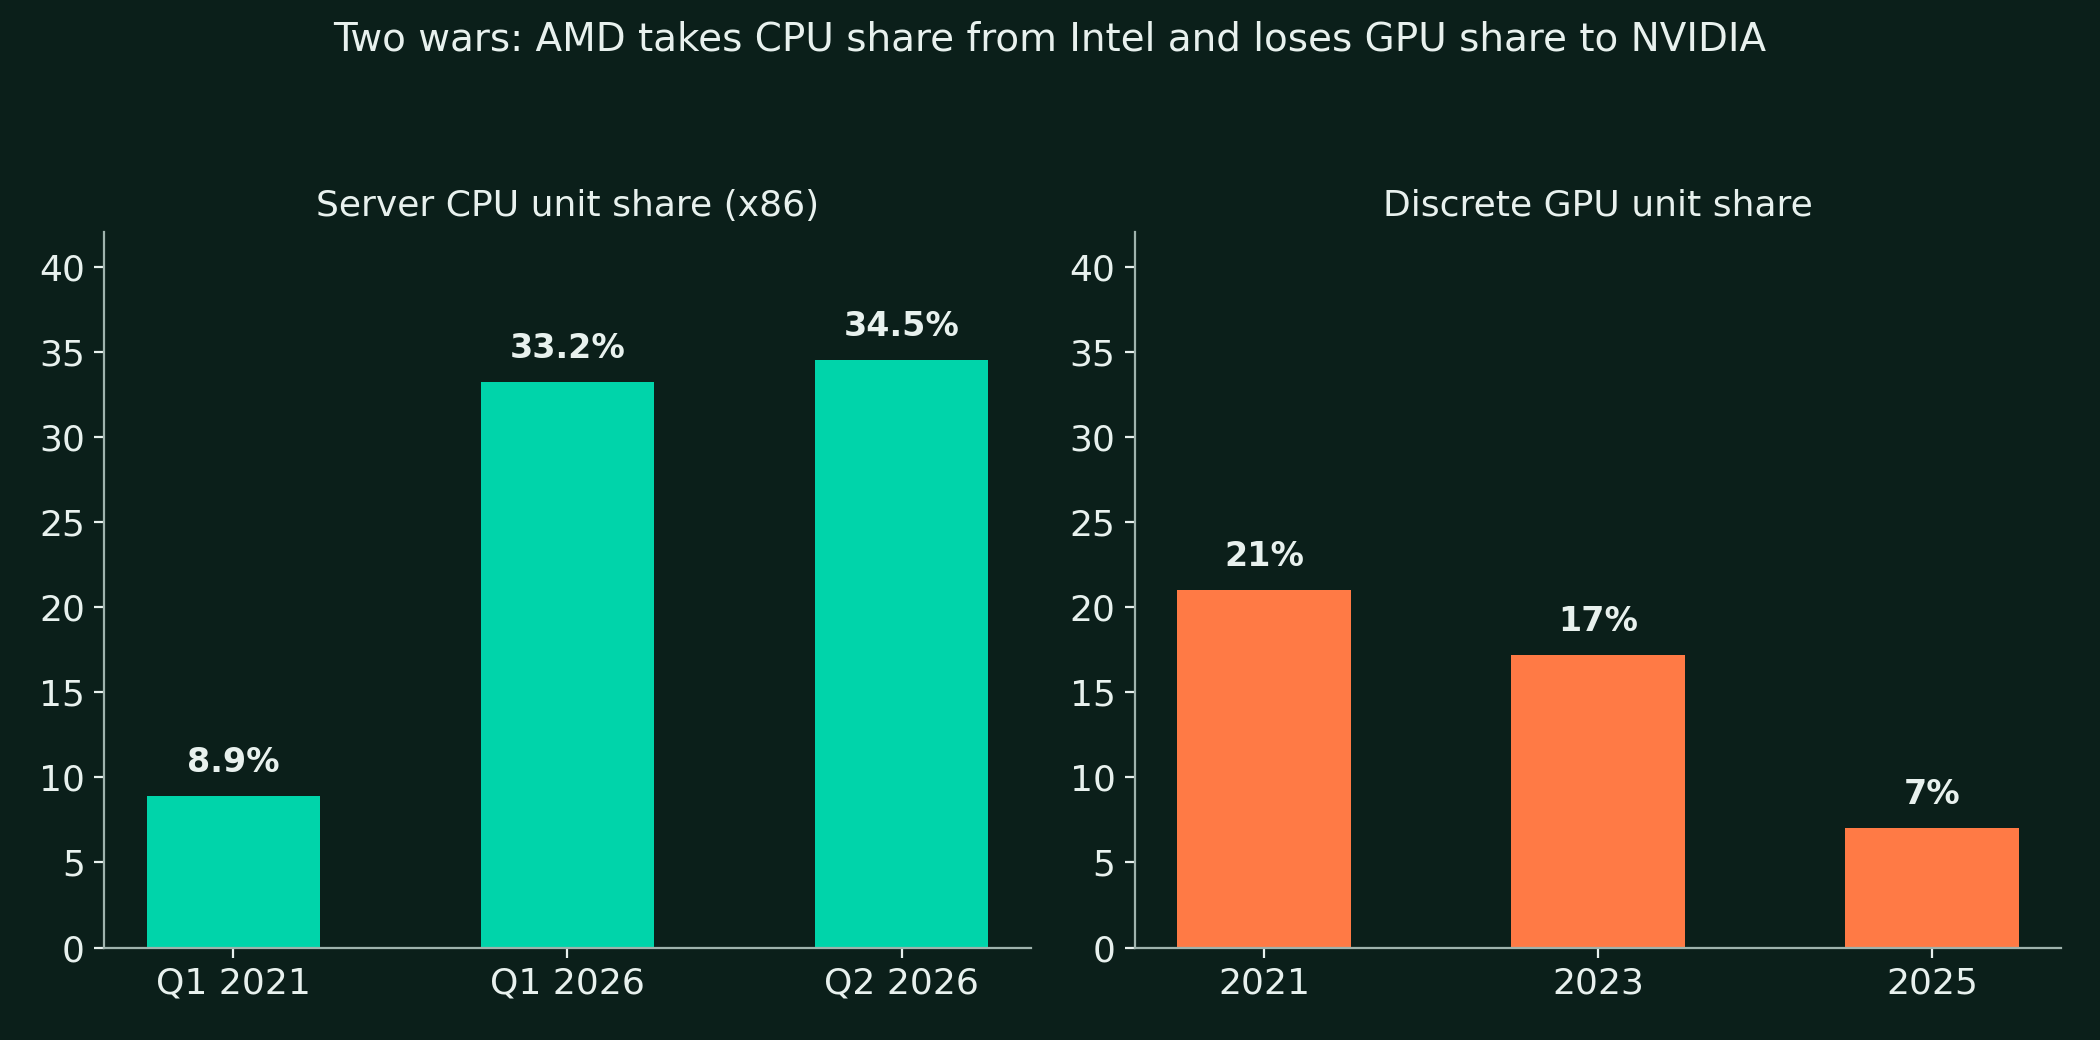
- Mercury Research put AMD at 34.5% of x86 server CPU units in Q2 2026, up from 27.3% a year earlier and 8.9% in Q1 2021.
- AMD took a record 46.2% of x86 server CPU revenue in Q1 2026.
- EPYC Turin has passed 540 public cloud instance types and is the most widely deployed EPYC generation, per the Q3 2026 call.
- OpenAI selected Turin as the host CPU for its first self-developed accelerator platform, per the Q3 2026 call.
- Venice, the sixth-generation EPYC on Zen 6, has begun shipping, with more than 240 OEM and ODM platforms committed, about 20% more than Turin at the same stage.
- AMD launched Venice on July 22, 2026 with up to 256 cores, 16 DDR5 memory channels at about 1.6 TB/s per socket, and PCIe Gen 6.
- The Helion rack reference design packs 144 Venice processors into a full CPU rack for agentic workloads, and AMD has contributed the design to the Open Compute Project.
- Management guides server revenue to roughly double year over year in 2027, on unit growth and higher core counts with a smaller ASP contribution.
- Agentic workloads are raising the CPU content of AI infrastructure, and Meta's Muse agent passing 10M users in six weeks is the demand example management cited.
Instinct AI accelerators
- The MI350X and MI355X (CDNA 4, TSMC 3nm) carry 288 GB of HBM3E at 8 TB/s and have shipped since mid-2025.
- AMD launched the MI400 family on July 22, 2026, led by the MI455X with 432 GB of HBM4 and the MI430X for HPC and sovereign AI.
- MI455X has begun mass shipments, and Q3 2026 was the first revenue quarter for MI455X and Helios racks, per the Q3 2026 call.
- Management guides data center AI revenue to pass server CPU revenue for the first time in Q4 2026, and to land far above it in dollar terms.
- Management guides data center AI revenue to grow significantly more than double in 2027.
- AMD has still never disclosed a separate Instinct revenue figure. The crossover guide is the first checkable AI revenue claim the company has made.
- Analyst estimates for AMD's 2026 AI GPU revenue ran from about $8B to $12B before the print (Cantor Fitzgerald and peers). These are analyst estimates, not company guidance.
- Data Center segment operating income was $2,882M in Q3 2026 at a 33.7% margin, up from $2,103M at 31.3% in Q2 and $1,074M at 25% a year earlier.
- EuroHPC selected MI430X systems for the LUMI-AI flagship supercomputer, expected online in the second half of 2027.
- AMD is developing the MI500 and MI600 generations in deep collaboration with frontier lab customers, per the Q3 2026 call.
What is Helios and why does it matter?
- AMD acquired ZT Systems for about $4.9B in a deal that closed in March 2025.
- AMD kept roughly 1000 system design and customer-enablement engineers and divested the manufacturing arm to Sanmina in Q4 2025, a divestiture confirmed by the discontinued operations line in AMD's 2026 filings.
- Helios is the product of that team: a liquid-cooled rack with 72 MI455X accelerators, Venice EPYC CPUs, and Pensando Vulcano networking.
- Company figures put one Helios rack at about 31 TB of HBM4 and about 2.9 exaFLOPS of FP4 compute.
- Helios networking is Ethernet end to end, with UALink-over-Ethernet for scale-up at launch and Vulcano at 800G for scale-out.
- Anthropic, Meta, Microsoft, OpenAI, and Oracle Cloud Infrastructure are running models and workloads on the first Helios rackscale solutions, per the Q3 2026 release.
- HPE's Vultr deployment is the first Helios by HPE system, per the graded DalalBytes scorecard of the release.
- On October 27, 2026, AMD announced that initial Helios systems are installed and being tested at Meta, with a broader deployment expected in the near future.
- The same October announcement said EPYC processors power Meta's Muse AI agent and that AMD will invest $1B in Meta's equity offering.
- OpenAI's first gigawatt of MI450 systems is scheduled to begin deployment in the second half of 2026.
- Meta's first gigawatt of shipments is scheduled to begin in the second half of 2026 on a custom MI450-based GPU.
- Management said on the Q3 call that it knows which data centers and locations the guided 2027 GPU deployments land in, after joint planning with customers.
Can ROCm close the gap with CUDA?
- ROCm is AMD's open software stack for GPU computing, and AMD released the ROCm 10 generation alongside the Q3 2026 print.
- PyTorch support is official, and the major open serving frameworks, vLLM and SGLang, treat AMD as a first-class target.
- Day-zero support for major open model releases is now routine on Instinct.
- Meta runs Instinct GPUs in production for training, ranking, and recommendation workloads, per the October 27, 2026 announcement.
- Anthropic's July 2026 partnership includes a multiyear collaboration to optimize Instinct GPUs and ROCm using Claude.
- Frontier labs are co-developing the MI500 and MI600 generations with AMD, which is the deepest software commitment the stack has carried.
- The counter-evidence is commercial rather than technical. AMD still discloses no Instinct revenue line, so software adoption cannot be verified in dollars.
- Frontier training at the largest labs still starts on CUDA by default, and AMD is the second port, not the first.
- The balanced read: ROCm has reached functional parity for mainstream inference serving, and the inference abstraction layer hides more of the CUDA difference every quarter. Training at hyperscale remains contested ground, and the Q4 AI crossover is the first revenue test of the parity claim.
How are Client, Gaming and Embedded doing?
Client
- Client revenue was $2,949M in Q3 2026, up 7% year over year on Ryzen mobile processor sales.
- Mercury Research put AMD at a record 30.3% of x86 client CPU units in Q2 2026 and 34.9% of desktop units.
- Ryzen AI parts carry the AI PC position, and Socket AM5 support now extends through 2029.
- Management guides Client and Gaming revenue down more than 20% sequentially in Q4 2026 on seasonal client weakness.
- Management plans for PC market unit shipments to fall by a double-digit percentage in 2027, as component price increases lift system prices, per the Q3 2026 call.
- The stated response is mix, not volume: enterprise, high-end consumer, and desktop channel segments, with supply flexed between PC and data center lines.
Gaming
- Gaming revenue was $773M in Q3 2026, down 40% year over year on lower semi-custom and graphics revenue.
- The current console generation is late cycle, and semi-custom revenue troughs before it recovers.
- Next-generation consoles are rumored to stay AMD-powered on Zen 6 and RDNA 5 with a 2027 launch window. Treat every part of that sentence as unconfirmed leaks.
- Radeon discrete GPU unit share fell from 21% in 2021 to 7% in 2025 (Jon Peddie Research), the one consumer market where AMD is losing.
Embedded
- Embedded revenue was $1,109M in Q3 2026, up 29% year over year.
- Segment operating income was $453M in Q3 2026 at a 40.8% margin, the richest margin AMD reports.
- Management guides Embedded revenue up double digits sequentially in Q4 2026, with significant growth across 2027 after normal first quarter seasonality.
- AMD cited more than $18B of new design wins on the Q2 2026 call.
- Versal Premium Gen 2, the Ryzen AI Embedded X100 series, and the Kria AI robotics platform all launched in 2026.
- The Xilinx acquisition price of $49B was full. The integration worked, and the segment now compounds quietly under the AI narrative.
Does AMD have a moat?
AMD's moat is still two different assets sharing a balance sheet, and November 3 moved only one of them. The EPYC moat is real and deepening. A 2nm process lead Intel cannot match on any public roadmap through 2027, 16 memory channels that make Venice the host CPU anchor of the AI rack, a record 46.2% of server CPU revenue on a third of the units, and a guide for server revenue to roughly double in 2027 are the signatures of a supplier with pricing power, not a challenger begging for sockets. OpenAI choosing Turin to host its own first accelerator platform is the moat showing up inside a rival's rack.
The Instinct position improved from a window to a beachhead, and a beachhead is still not a moat. Helios racks running at five named customers and a guided Q4 crossover where AI revenue passes CPU revenue prove AMD can ship systems at frontier scale, which the November package treated as an open question. What has not changed is the exit door. AMD still discloses no Instinct dollar line, the anchor relationships still carry warrants, and every anchor customer can still leave at a generation boundary, with two of the three building custom silicon of their own. The pillar grade stays partial, at a higher score, because conversion is now evidenced and lock-in is not.
Who competes with AMD, and by how much?
| Competitor | Where they meet AMD | The number that matters |
|---|---|---|
| NVIDIA | AI accelerators, networking, gaming GPUs | About 75% of AI accelerator revenue in 2026 estimates and 93% of discrete GPU units in 2025 |
| Intel | Server and client CPUs | Intel guided Q4 2026 revenue to $15.0B to $16.0B, below AMD's $17B guide midpoint for the same quarter |
| Broadcom | Custom AI silicon design | AI revenue of $16.7B in Q3 fiscal 2026 and a $73B AI backlog |
| Arm licensees | Server CPUs from above | Arm designs took 13.6% of server CPU shipments in Q2 2026 |
| Hyperscaler silicon | TPU, Trainium, MTIA, Maia | Custom ASIC units pass merchant GPU units in 2027 on JPMorgan shipment forecasts |
- NVIDIA's data center revenue share across the NVIDIA, AMD, and Intel peer set rose from 25% in Q1 2021 to 86% in Q4 2025 (Bloomberg via Visual Capitalist).
- AMD's share of that same set has held a 7% to 9% band since 2023, after a 17% peak in late 2022. The Q4 2026 crossover guide is the first company claim that can bend this line.
- AI accelerator revenue share tells the same story one level down: NVIDIA holds about 75% in 2026 estimates, custom ASIC holds about 13%, and AMD holds about 7% (DalalBytes Compute Share Wars).
- Intel's Q3 2026 print showed data center and AI revenue up 78% year over year, growth that rides on Xeon host CPUs inside other vendors' GPU racks, and its Q4 guide then repriced the CPU complex on October 30, 2026.
- If both Q4 guides land, AMD's quarterly revenue passes Intel's for the first time. Treat that as a guide comparison, not a reported result.
- Google now sells TPU capacity externally, with Anthropic committed to up to one million TPU chips. Every TPU gigawatt is a gigawatt no merchant vendor bids on.
- Meta's three-vendor structure is the template: its own MTIA silicon for the base load, AMD for a custom inference layer, and NVIDIA for the frontier.
- AMD's EPYC socket sits inside many custom-silicon racks as the host CPU, which keeps AMD in the tent even where its GPUs are not.
- Arm-based Graviton, Axion, and Cobalt instances cap x86 pricing from above, because the hyperscalers' own Arm chips set the price of a unit of CPU work inside their clouds.
What do AMD's financial statements say?
| GAAP results ($M) | FY2023 | FY2024 | FY2025 | Q2 2026 | Q3 2026 |
|---|---|---|---|---|---|
| Revenue | 22,680 | 25,785 | 34,639 | 11,536 | 13,377 |
| Gross profit | 10,460 | 12,725 | 17,152 | 6,203 | 7,224 |
| Gross margin | 46% | 49% | 50% | 54% | 54% |
| Operating income | 401 | 1,900 | 3,694 | 1,990 | 2,832 |
| Net income | 854 | 1,641 | 4,335 | 2,297 | 2,428 |
| Diluted EPS | $0.53 | $1.00 | $2.65 | $1.38 | $1.46 |
| Non-GAAP gross margin | 52% | 53% | 52% | 56% | 56% |
| Non-GAAP diluted EPS | $1.38 | $2.31 | $4.17 | $1.66 | $2.09 |
- Q3 2026 non-GAAP operating income was $3,923M at a 29% margin, up 75% year over year on the call's figures.
- The GAAP to non-GAAP bridge in Q3 carries a $1,097M charge for the change in fair value of the warrant liability, worth $0.66 a share.
- Other income and expense, net, swung to a $902M expense in Q3 from $598M of income in Q2, and the warrant remeasurement is the driver named in the release footnote.
- Segment operating income in Q3 2026: Data Center $2,882M, Client and Gaming $573M, Embedded $453M, with $1,076M of unallocated corporate and other expense.
- Inventories rose to $11,463M at September 26, 2026 from $8,468M at June 27, a build of $2,995M in one quarter. Accounts receivable rose to $9,209M and accounts payable to $7,756M.
- Operating cash flow on continuing operations was $1,202M in Q3 against capex of $648M, for free cash flow of $554M at a 4% margin.
- Q3 free cash flow fell from $1,558M in Q2 2026 and $1,530M in Q3 2025, and the release puts the difference in working capital, not in earnings.
- Inventory days on Q3 GAAP cost of sales run near 169 days, up from about 145 days in Q2. The build is a stated bet on data center demand.
- Free cash flow was $1.12B in fiscal 2023, $2.41B in fiscal 2024, and $5.52B in fiscal 2025 on the continuing operations basis.
- Trailing twelve-month free cash flow on the continuing basis is about $6.76B, down from $7.74B at June 2026.
Free cash flow basis
Free cash flow in this report is stated on a continuing operations basis. Fiscal 2025 free cash flow on that basis was $5,519M and trailing twelve-month free cash flow is about $6,760M. Total company figures that include the divested ZT Systems manufacturing business run higher, and the November 2 package headlined that basis. The two bases are never blended here.
Has AMD delivered on its roadmap?
| Promise | Set when | Status at November 4, 2026 |
|---|---|---|
| Annual Instinct cadence, MI350 then MI400 | Advancing AI 2025 | Delivered. The MI400 family launched July 22, 2026 |
| Venice EPYC on TSMC 2nm in 2026 | 2025 product disclosures | Delivered. Venice has begun shipping with more than 240 platforms committed |
| Helios rack systems shipping in Q3 2026 | 2025 OCP disclosure, repeated on the Q2 2026 call | Delivered. Q3 was the first Helios revenue quarter and racks are online at five named customers |
| OpenAI first gigawatt of MI450 in H2 2026 | October 6, 2025 | In progress. OpenAI is running workloads on the first Helios systems |
| Meta first gigawatt shipments begin in H2 2026 | February 24, 2026 | In progress. Meta is a named Helios operator after October systems entered test |
| Anthropic first gigawatt in H1 2027 | July 22, 2026 | Pending. Anthropic is running workloads on the first Helios systems |
| Data Center revenue more than doubles in 2027 | August 4, 2026 | Strengthened. Management now guides total 2027 revenue growth above 80% and Data Center above 80% of revenue |
| Server CPU revenue up more than 80% in H2 2026 | August 4, 2026 | On track. Q3 Data Center grew 97% year over year and Q4 Data Center is guided up about 50% sequentially |
| Data center AI revenue passes server CPU revenue | November 3, 2026 | Pending one quarter. Guided for Q4 2026, with AI landing far above CPU in dollars |
| ROCm parity for mainstream inference | Multi-year claim | Partially delivered. ROCm 10 shipped and serving parity is evidenced, frontier training is not |
| More than $20 of annual non-GAAP EPS in the long-term model | Financial Analyst Day, November 2025 | Pending. The base case in section 13 reaches it in fiscal 2029 |
The pattern across a decade of this audit held through November 3: AMD delivers silicon on the date it names, and its misses are commercial, not engineering misses. Venice is shipping, the MI400 family arrived on cadence, MI455X is in mass shipment, and Helios exists as operating systems at five named customers rather than as a slide. The November 2 package said the pending half of the roadmap carried the valuation and that the Q4 guide was the first scoring date. The guide scored. Helios volume appears in it by name, by customer, and by a sequential Data Center step of about 50% that arithmetic cannot reach on CPUs alone.
The audit's open items have narrowed to two kinds. The first is conversion in dollars: the gigawatt schedule still converts through customer construction and a sold-out memory chain, and AMD still gives no Instinct revenue line to check it against. The second is new: the 2027 guide is now so large, total revenue growth above 80% with supply guided as the constraint, that execution risk has moved from demand to wafers, substrates, advanced packaging, and HBM. Management said demand exceeds supply and pointed to multi-year joint planning with customers and the supply chain. That is a better class of risk than the one AMD carried into the print. It is still the risk the next four quarters grade.
What do the balance sheet and the warrants mean for holders?
- Cash, cash equivalents, and short-term investments were $15,776M at September 26, 2026, a record.
- Total debt was $7,079M at September 26, 2026. The balance sheet carried about $8.7B of net cash.
- On August 17, 2026, AMD closed a $4.75B senior notes offering, the largest bond deal in its history, and the Q3 balance sheet now carries it.
- The notes are $1.25B at 4.600% due 2029, $1.50B at 5.000% due 2031, $1.00B at 5.250% due 2033, and $1.00B at 5.500% due 2036.
- AMD repaid the $875M of 2026 notes in the quarter. The release balance sheet shows no current portion of long-term debt.
- Interest expense was $62M in Q3 2026, up from $37M in Q2, as the new notes landed.
- Buyback authorization stands at roughly $10B, including $6B added in May 2025. Program repurchases were $221M in the first half of 2026 with zero open-market repurchases in Q2, and growth funding continues to outrank shareholder return.
- The OpenAI warrant covers up to 160M shares at a $0.01 exercise price, vesting in tranches as deployments scale from 1 gigawatt to 6, with vesting also tied to AMD share-price targets and OpenAI technical and commercial milestones.
- The Meta warrant covers up to 160M shares at $0.01 on the same pattern, with stock-price thresholds that escalate to $600 and an exercise window running through February 2031.
- Together the two warrants cover 320M shares, about 19.6% of the 1632M basic share count, if every tranche vests.
- Q3 2026 is the first quarter the warrants reached the income statement: a $1,097M fair value charge, $0.66 a share, driven by the rising stock price and higher assessed vesting odds.
- Management said on the call that revenue guidance already nets the warrant deduction at grant-date fair value, that dilution occurs only after vesting and exercise conditions are met, and that clear dilution guidance comes in 2027.
- The Q4 2026 slide deck states the Q4 share count is not expected to be impacted by customer warrants, and guides about 1.67B diluted shares including the pending Taalas and World Labs acquisitions.
- AMD has committed up to $5B of equity investment in Anthropic, expected to fund through fiscal 2028 subject to contingencies.
- AMD will invest $1B in Meta's October 2026 equity offering, announced October 27, 2026.
- AMD announced agreements to acquire Taalas and World Labs on the Q3 print, both expected to close by the end of 2026. World Labs founder Fei-Fei Li joins AMD as Chief Scientist on completion.
- Unconditional purchase commitments were $30,276M at June 27, 2026. The Q3 Form 10-Q update to that figure was not yet on file in the sources read for this package, and the commitment stack should be rechecked against it.
What is AMD worth in fiscal 2029?
- Market cap at the reference price is about $804B on 1661M diluted shares.
- Trailing non-GAAP EPS is $6.65 across Q4 2025 to Q3 2026. The reference price pays about 73 times that figure.
- Fiscal 2026 revenue on nine-month actuals plus the Q4 guide midpoint is about $52.2B, above the $51.0B consensus carried into the print.
- Fiscal 2026 non-GAAP EPS on the same build runs near $8.10, with the Q4 guide implying roughly $2.95 for the quarter. Treat both as DalalBytes estimates from the guide, not company guidance.
- The 2027 guide of revenue growth above 80% implies fiscal 2027 revenue near $94B on the fiscal 2026 build. The scenarios below decelerate from that guided year rather than extrapolating it.
- Trailing free cash flow of about $6.76B on the continuing basis puts the price near 119 times free cash flow. The multiple on cash is the fullest one on this page, and section 10 shows why.
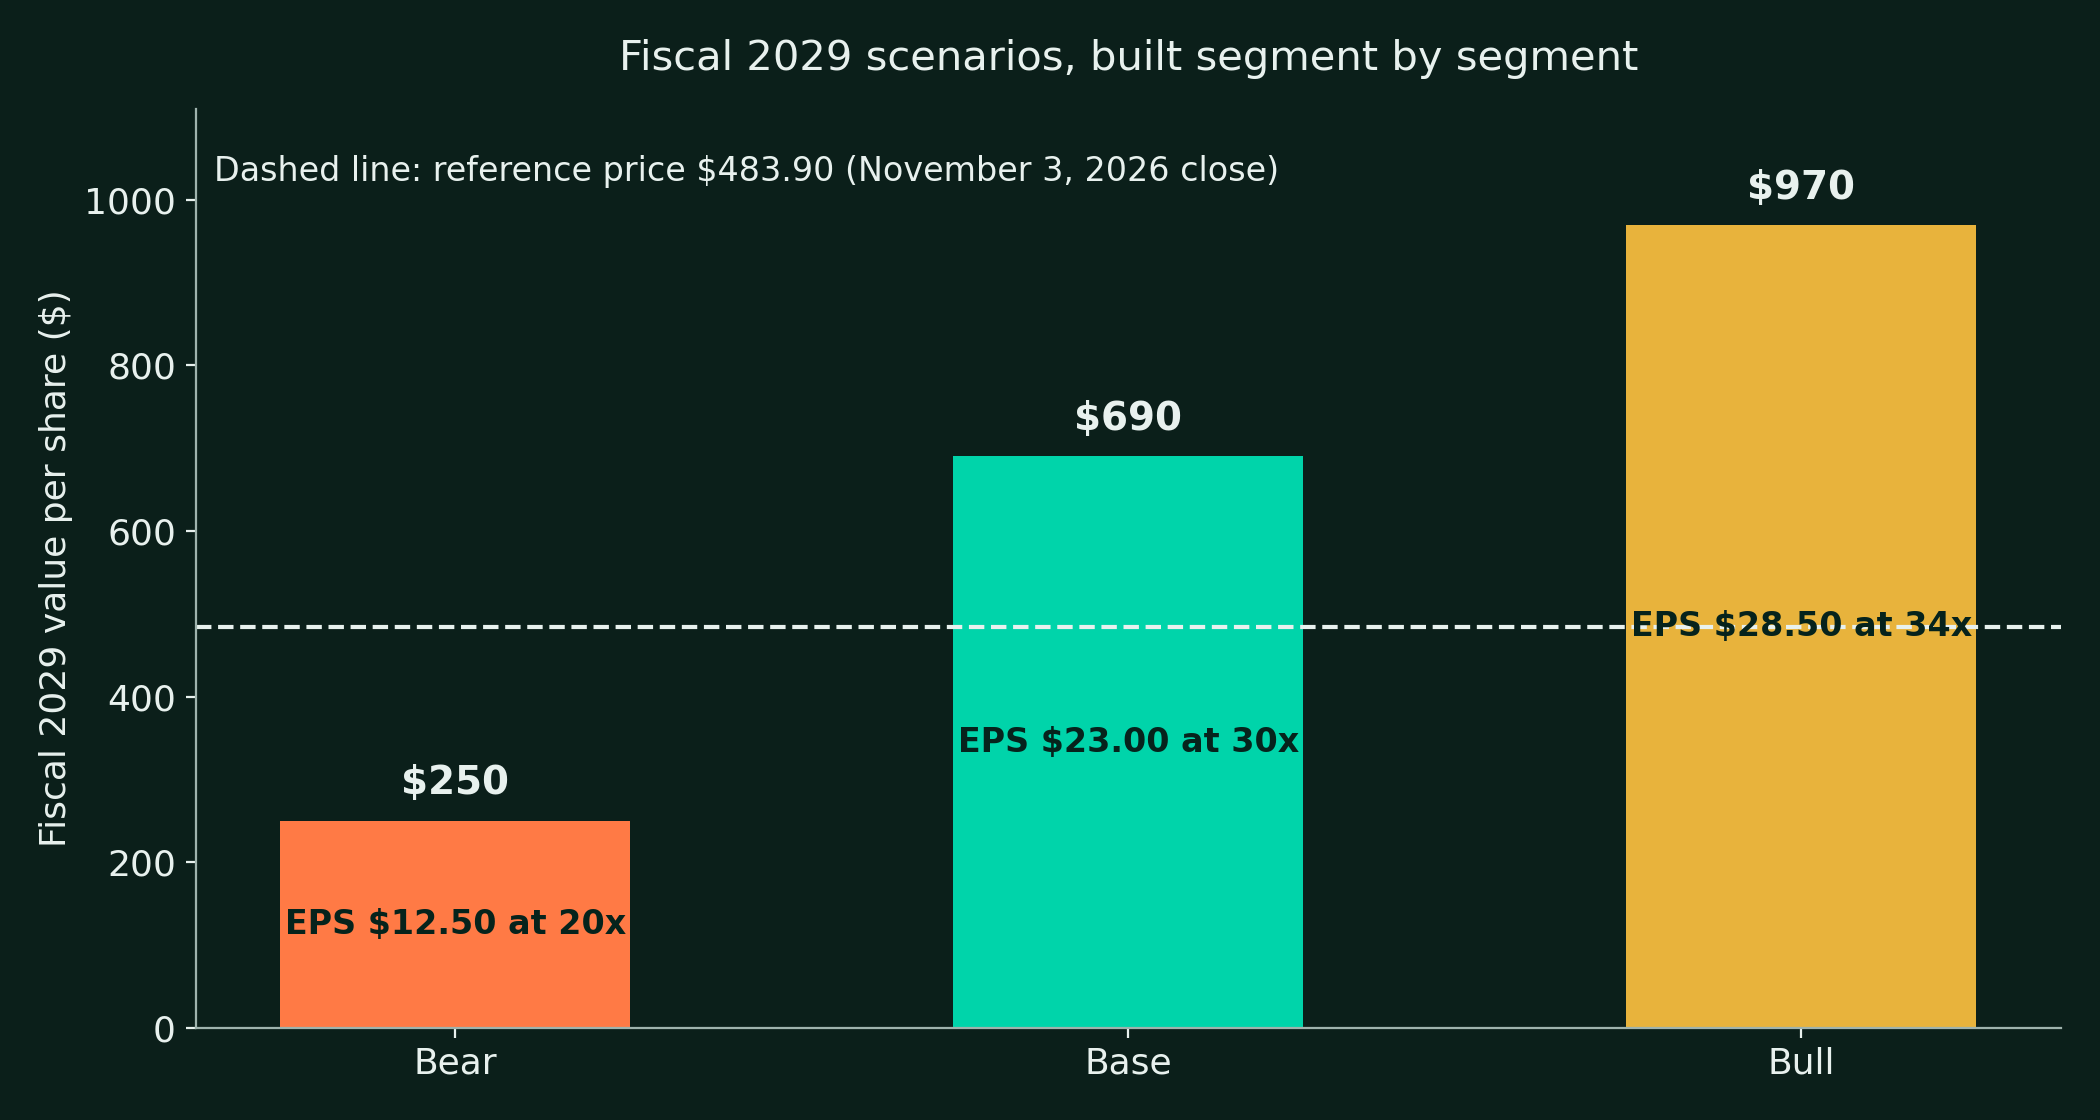
| Fiscal 2029 build ($B) | Bear | Base | Bull |
|---|---|---|---|
| Data Center, EPYC CPUs | 40 | 52 | 60 |
| Data Center, Instinct GPUs | 34 | 72 | 98 |
| Data Center, networking and other | 4 | 6 | 8 |
| Client | 11.0 | 14.0 | 17.0 |
| Gaming | 3.4 | 4.6 | 6.2 |
| Embedded | 5.4 | 7.0 | 8.6 |
| Total revenue | 98 | 156 | 198 |
| Non-GAAP EPS | $12.50 | $23.00 | $28.50 |
| Exit multiple | 20x | 30x | 34x |
| Value per share | $250 | $690 | $970 |
The skeptic case
The base case's hardest-working assumption is Instinct revenue reaching about $72B by fiscal 2029, from a 2026 base the company does not disclose and analysts estimated at $8B to $12B before the print. That path needs the 14 gigawatts of "up to" commitments to convert at high rates on schedule, HBM4 supply to hold through a single primary memory partner, the $11.463B inventory pile to convert into shipped racks rather than into charges, and rack mix not to dilute the gross margin line guided at 55% for Q4. The evidence that breaks it is specific: a Q4 2026 print where Data Center misses the guided 50% sequential step, inventories rise again beside it, or any anchor customer shifting a generation to its own custom silicon.
- The bear case is a conversion failure, not a demand collapse. EPYC still compounds, the gigawatts arrive at a fraction of announced scale, the inventory build charges back, and the multiple compresses to 20 times on $12.50 of earnings.
- The base case pays the 2027 guide in full, then decelerates hard: revenue growth above 80% in 2027 stepping down toward the mid-teens by 2029. It lands above management's long-term EPS ambition of more than $20.
- The bull case requires AMD to bend the accelerator share line up out of its 7% to 9% band toward the low teens, with warrant dilution already inside the share count.
- One discipline runs through all three cases. The 56% gross margin is treated as a cycle-peak print that mix must defend, not a floor that price will raise, consistent with the DalalBytes Compute Price Reset analysis of where this cycle sits.
- Versus November 2: the base case rose from $615 to $690 because the guided 2027 base year is now roughly $94B of revenue instead of an extrapolation, and the exit multiple stayed at 30 times. The bear case rose from $230 to $250 on the same base effect, partly offset by the inventory and warrant evidence.
What are the main risks to the AMD thesis?
The first risk is now working capital, and Q3 made it concrete. A $2.995B inventory build in one quarter, to $11.463B and roughly 169 days of cost of sales, is a bet that the Q4 guide's 50% Data Center step lands on time. The Q2 2025 precedent shows the other side of that bet in the company's own history: about $800M of MI308 inventory and related charges when China licenses stopped. If Helios conversion slips a quarter, the same pile that funded the ramp becomes the charge, and free cash flow, already at a 4% margin, has no second cushion.
The second risk is that the demand is partly purchased, and the purchase price now prints in the P&L. Two customers anchor the forward Instinct story, and both were paid in warrants that dilute existing holders by up to a fifth of the company if every tranche vests. Q3 booked $1.097B of that cost in a single quarter, before one warrant share was issued. Add up to $5B committed to Anthropic's equity, $1B into Meta's offering, and a reported guarantee behind a neocloud's chip loan, and the pattern the industry shares with NVIDIA and Broadcom is AMD's pattern too: suppliers financing the demand they report. None of this makes the deployments fake. The racks are physically running at five named customers. It does mean the quality of AMD's forward demand is lower than the quality of its forward supply, and the gap is where a repricing would start.
The third risk is physical, and the 2027 guide enlarged it. Every MI455X carries 432 GB of HBM4 into a memory market that is sold out industry-wide, and AMD has named Samsung as its primary HBM4 partner under a 2026 memorandum, which puts the flagship on the memory supplier that has trailed SK hynix on HBM qualification. Management said it is negotiating with customers to share rising component costs, which concedes the cost pressure is real. A guide for revenue growth above 80% is, in the end, a wafer, substrate, packaging, and memory allocation schedule, and TSMC packaging capacity is contested by NVIDIA's Rubin ramp and Broadcom's XPU programs at the same time.
The fourth risk is the consumer flank. Gaming fell 40% in Q3, Client and Gaming are guided down more than 20% sequentially in Q4, and management plans for PC shipments to fall by a double-digit percentage in 2027. The CPU engine that funds the accelerator build is partly a PC engine, and a shrinking PC market raises the share AMD must take from Intel merely to hold Client revenue. China and the policy stack sit behind it: China has historically been roughly a fifth of AMD's revenue, the MI308 episode produced about $800M of charges, and the MI450 class remains restricted. At about 73 times trailing non-GAAP earnings, none of these risks needs to be fatal to cost the stock. A merely good outcome, delivered one quarter late, meets a multiple with further to fall than the earnings do, and key-person concentration sits underneath all of it, with the strategy and the roadmap credibility substantially one person's record.
What is the AMD story?
In October 2014 AMD was worth about $2B and was a plausible bankruptcy candidate. Lisa Su's response was a sequence of unfashionable decisions executed in order: rebuild the CPU core and accept years of low share while it matured, sell the company's manufacturing past and go all-in on TSMC, buy Xilinx for the embedded cash flows the AI story would later need, and decline to chase NVIDIA's training fortress head-on while building the one portfolio, CPU plus GPU plus networking plus rack integration, that a buyer could substitute as a system. The Zen architecture compounded quietly for five years before the market repriced it. By September 2026 the company was worth $1T, the fourth US chipmaker to reach the mark.
The story's second act turned a page on November 3, 2026. The first act was a technology recovery, graded on products. The second is a capacity and credibility buildout, graded on gigawatts, and its first graded quarter delivered: record revenue, racks online at five named customers, a Q4 guide that implies AMD's quarterly revenue passing Intel's for the first time, and a 2027 outlook raised to growth above 80% in a single print. The designated role, the second source whose existence disciplines NVIDIA's pricing, is being played at a scale the script did not assume. What the second act has not yet produced is cash at the rate the first act's ending promised, and the $11.463B of inventory on the balance sheet is the physical form of that gap. The next four quarters grade whether the buildout converts inventory into revenue and revenue into cash, or whether the genre changes again.
What price basis does this report use?
- Reference price $483.90, the Tuesday November 3, 2026 Nasdaq close, sourced from Finnhub.
- The stock rose 3.65% in the November 3 regular session from $466.84, the Monday November 2 close, and rose further after hours on the print, with secondary coverage putting the after-hours gain at about 7% to 9%.
- The October decline was 17.5% for the month, against a record close of $649.42 on October 6, 2026. The reference price sits about 25% below that record.
- AMD reported Q3 2026 on Tuesday November 3, 2026 after the close, with a call at 5:00 PM ET. The company had announced the date.
- The Q3 bar was the company's own guide: revenue of about $13.0B plus or minus $300M and a non-GAAP gross margin of about 56%. AMD delivered $13,377M and 56%.
- The DalalBytes preview scorecard graded the print five passes and one near miss (Client at $2,949M against a $3.0B pass line), with the Q4 Helios gate passed on named ramps at named customers.
- This package supersedes the November 2, 2026 DalalBytes package, which scored AMD 68/100 at a $504.80 reference price on Q2 2026 data, and the September 28, 2026 package before it at 72/100 and $630.63.
- The next scoring date is the Q4 2026 print, graded on the guided 50% sequential Data Center step, the AI revenue crossover, and free cash flow conversion of the Q3 inventory build.
Frequently asked questions
What changed versus the November 2 score of 68?
The score rose four points because the pending half of the roadmap converted. Helios racks are online at five named customers, MI455X ships in volume, and the Q4 guide near $17B beat the path the November package required. Free cash flow of $554M and a $1.097B warrant charge capped the rise.
Why did GAAP EPS of $1.46 trail non-GAAP EPS of $2.09?
The gap is mostly one line. AMD remeasured its customer warrant liabilities in the quarter and booked a $1.097B non-cash charge worth $0.66 a share, driven by its own rising stock price and higher vesting odds. Success dilutes on this structure, and the mark reached the income statement before any warrant share was issued.
What would turn the 2027 guide into proven revenue?
Three proofs in order. Fourth quarter Data Center revenue landing near the guided 50% sequential jump with AI revenue above server CPU revenue. A disclosed Instinct dollar line or segment detail that ends the estimate era. And free cash flow recovering toward $2.5B a quarter as the $11.463B inventory pile converts into shipped racks.
Sources and disclosures
- AMD Form 10-K for fiscal 2025 and Form 10-Q for Q2 2026, including segment results, balance sheet detail, and the warrant classification note.
- AMD results releases: Q4 and full year 2025 (February 3, 2026), Q2 2026 (August 4, 2026), and Q3 2026 (November 3, 2026, Form 8-K accession 0000002488-26-000188), including the GAAP to non-GAAP reconciliations and the Q4 2026 outlook.
- AMD Q3 2026 earnings call, November 3, 2026, as transcribed in same-day call coverage: the 2027 outlook (revenue growth above 80%, server revenue roughly doubling, data center AI growth significantly more than doubling, Data Center above 80% of revenue), the Q4 segment guides, the warrant accounting explanation, and the supply discussion.
- AMD deal announcements: OpenAI partnership (October 6, 2025), Meta expanded partnership (February 24, 2026), Anthropic partnership (July 22, 2026), and Helios systems at Meta (October 27, 2026).
- AMD Form 8-K and prospectus supplement for the $4.75B senior notes offering (August 2026).
- Mercury Research server and client CPU share for Q1 and Q2 2026, as reported in trade press.
- Jon Peddie Research discrete GPU unit share, and Bloomberg data via Visual Capitalist for data center revenue share, both as compiled in the DalalBytes Compute Share Wars article.
- Finnhub for the November 3, 2026 closing price of $483.90 and the November 2, 2026 close of $466.84.
- DalalBytes Compute Price Reset (November 1, 2026) for the cycle and margin framing, the DalalBytes AMD Q3 2026 earnings preview scorecard for the November 3 bar, and the DalalBytes graded scorecard of November 3, 2026 for the release-level grading.
- Disclosures: the author is long AMD. This report is research and opinion, not investment advice.