|
DALALBYTES
The Weekly Close
October 30, 2026 · What moved, what mattered, what's next
|
|
|
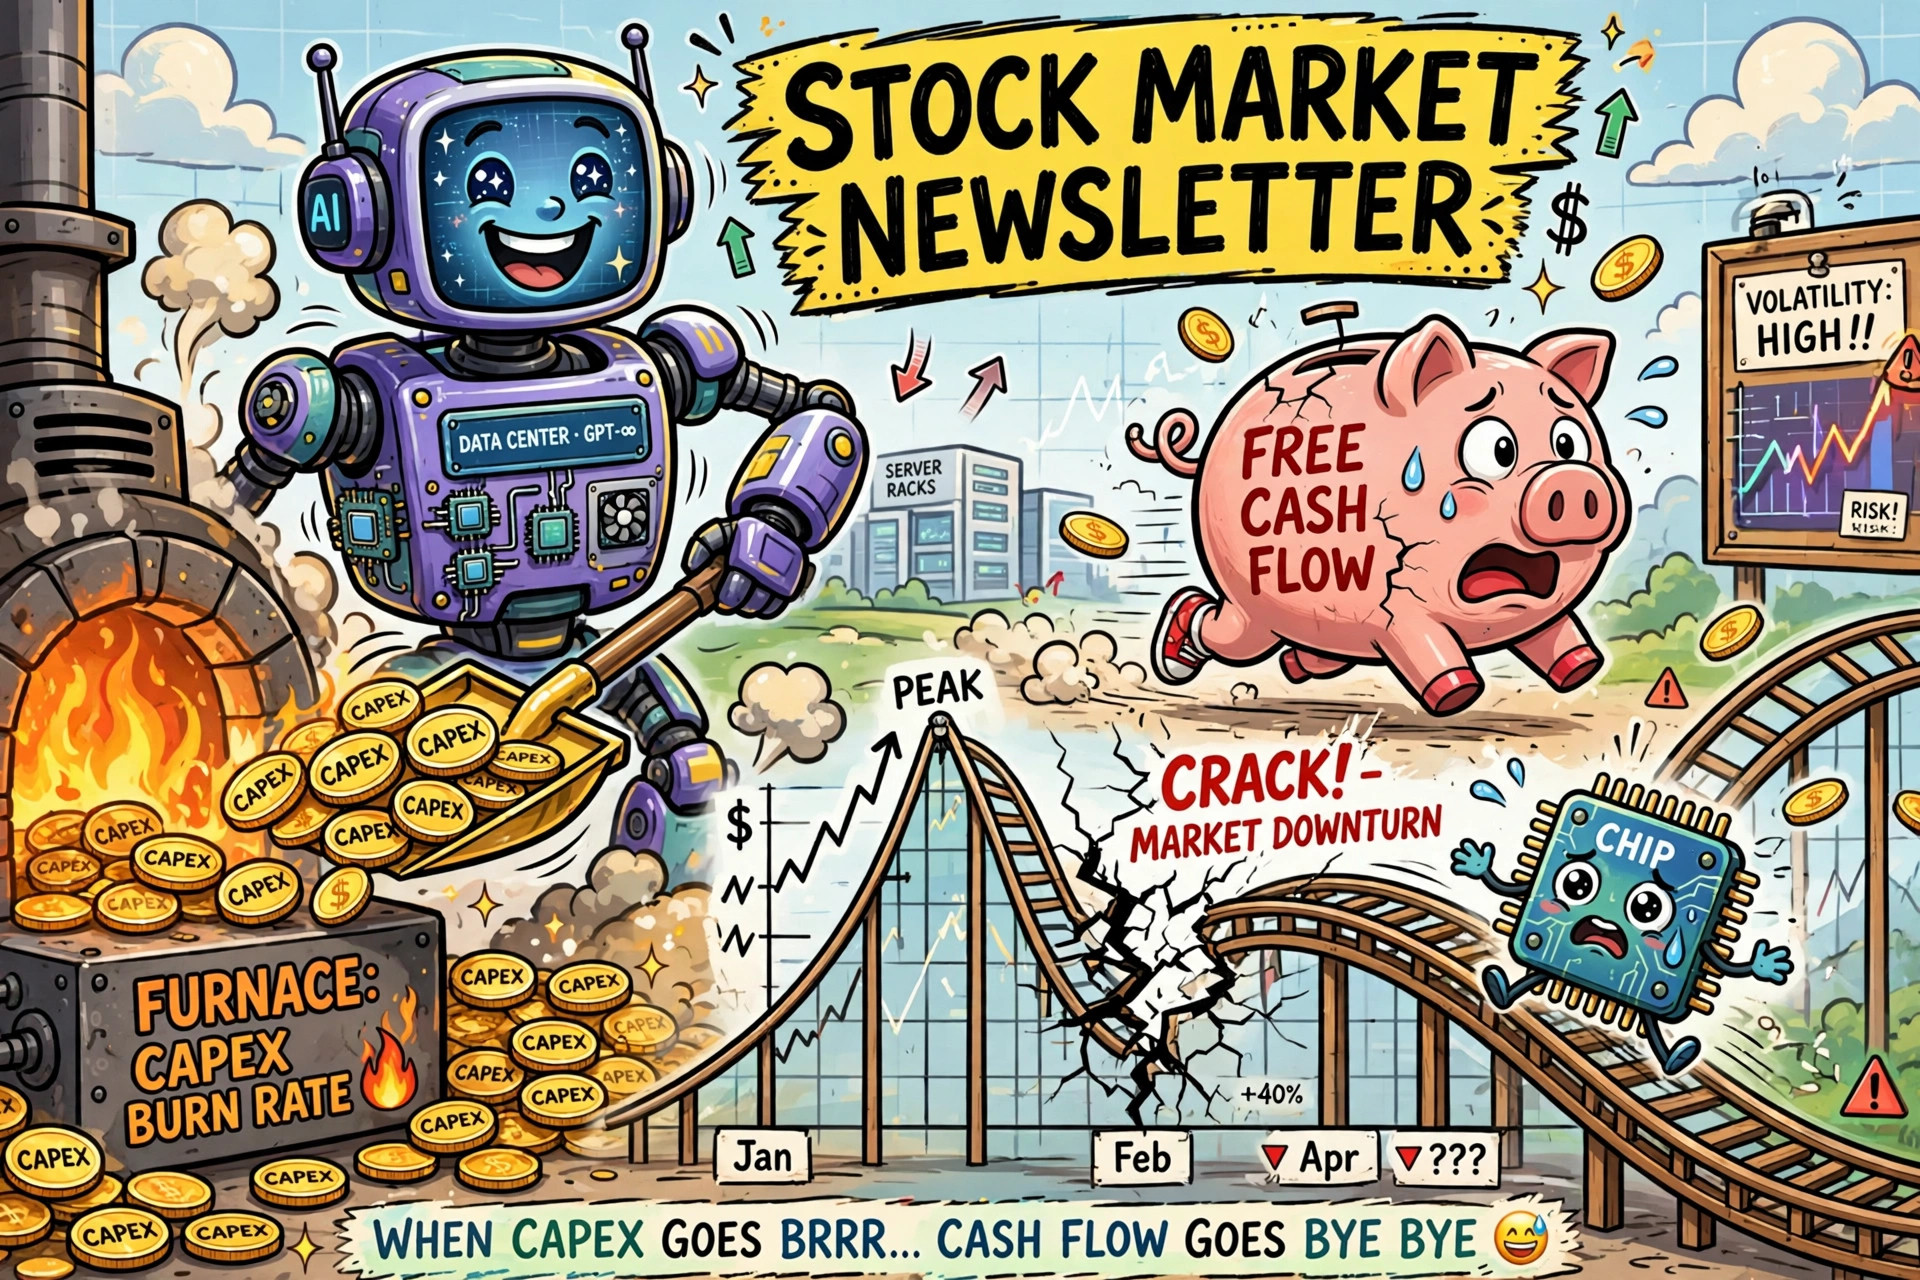
The week in one line: the AI trade cracked on its bill, not its demand. Alphabet's cloud doubled and its stock fell 12.6% in a day, Intel plunged on Friday, and India quietly rose almost 2% while the US argued about capex.
|
|
MARKET RECAP
The scorecard
|
S&P 500
-1.3%
week, approx.
|
|
NASDAQ
-3.0%
week, approx.
|
|
SENSEX
+1.8%
week
|
Monday to Thursday, the US market was fine. The S&P 500 rose 1.27% to 7,720.39 and the Nasdaq rose 0.88% to 26,184.72, the Fed held rates steady, Q3 GDP grew at a 3.4% annual rate, and September PCE inflation printed 3.6%. About 80% of S&P 500 stocks rose on Thursday even as the index fell. The damage was concentrated in a handful of very large AI spenders.
Thursday set the theme. Alphabet fell 12.64%, its worst day on record in our reading of the print: revenue grew 25% to $127.6B and Google Cloud grew 103% to $30.7B, but search growth slowed to 12% from 17%, capex reached $51.4B in the quarter, and free cash flow printed negative $9.1B for a second straight quarter. Amazon followed after the close: revenue up 12% to $201.9B, AWS up 39.3% to $46B, operating income up 61% to $28.1B, and trailing free cash flow at negative $42.4B, with 2026 cash capex guided near $220B and 2027 guided higher. Alphabet insight → Amazon insight →
Friday turned the theme into a selloff. The Nasdaq fell more than 3.8% and the S&P 500 fell 2.5%, each its worst day since June, the Dow fell about 1.5%, and Intel plunged more than 30% after its weak Q4 guide. Weekly US figures above combine the Monday to Thursday closes with Friday's reported index falls, so treat them as close approximations at send time. Our technical map of the damage, name by name, is here: The Capex Crack →
India did the opposite. The Sensex rose 308.49 points on Friday to 74,459.53, up 1.8% on the week from 73,123.83, and the Nifty rose 2.0% to 23,053.10, reclaiming 23,000 for the first time in eight sessions. IT rose 2.3% on Friday and pharma 1.8%, Trent jumped after a 25% profit rise, and the benchmarks closed October higher after two down months. The limits were visible too: mid-caps and small-caps fell on Friday, and Brent crude near $117 a barrel remains India's tax.
Next week: US midterm elections, October payrolls and September job openings, a Bank of England decision on Thursday, and earnings from Apple, AMD, and Palantir.
|
|
US DEEP DIVES
United States: fresh from the research desk
Netflix (NFLX)
Streaming and advertising · US |
72/100 |
Verdict: Positive. The best cash machine in media, at about half its October 2025 record close. Q3 revenue grew 11.8% to $12.87B at a 34.6% operating margin, buybacks set a record at $4.8B, and the failed Warner Bros. deal left Netflix with a $2.8B termination fee and its balance sheet untouched. The deduction is advertising: the 2026 guide fell to about $2.7B. FY2029 targets: $46 bear, $85 base, $118 bull (ref $62.05).
Full report →
·
Five-pillar analysis →
|
Robinhood (HOOD)
Retail finance platform · US |
66/100 |
Verdict: Selective Positive. The most complete retail financial platform ever built in the US, priced as if its newest business has already won in court. Fourteen business lines now clear $100M in annualized revenue, Q3 revenue reached $1,424M with adjusted EBITDA of $808M, and platform assets stand at $396B. Event contracts are the fastest growing line and the largest legal risk, with 21 states contesting the perimeter. FY2029 targets: $46 bear, $110 base, $158 bull (ref $94.56). Built as the companion to the SoFi report at 68/100, with the checkpoint box reading MIXED beside SoFi's POSITIVE.
Full report →
·
Five-pillar analysis →
·
SoFi vs Robinhood →
|
Oracle (ORCL)
Database and cloud infrastructure · US |
62/100 |
Verdict: Selective Positive. The fastest growth in big cloud, funded by the balance sheet. Cloud infrastructure revenue rose 121%, remaining performance obligations stand at $664B, and free cash flow was negative $23.7B in FY2026, with borrowings of $125.3B against $36.4B of cash and a BBB minus rating one notch above junk. At the October 28 investor day, management capped new funding at $20B more through FY2030. FY2029 targets: $102 bear, $230 base, $330 bull (ref $130.53).
Full report →
·
Five-pillar analysis →
|
Research desk roundup, US
Arm Holdings (ARM), 54/100, Neutral. The best seat in the AI CPU transition, priced for the fiscal 2031 plan today: fiscal 2026 revenue $4,920M, data center royalties more than doubled again, and the stock trades at 243 times trailing earnings with a float of only about 13%. FY2029 targets: $91 bear, $207 base, $319 bull (ref $235.90). Report → Five pillars →
Bloom Energy (BE), 54/100, Neutral. The fastest growth in on-site power: Q3 revenue $1,235.8M, up 138.1%, guidance raised for the third time this year to $4.4B to $4.6B, and free cash flow still negative $180.6M in the quarter. FY2029 targets: $47 bear, $133 base, $275 bull (ref $222.30). Report → Five pillars →
Intel (INTC), 47/100, Negative. The turnaround evidence is real and the funding model is dilution: Q3 revenue rose 21%, data center revenue rose 78%, foundry still lost $1,853M, and the Q4 guide cut the stock by about a quarter after hours before Friday's fall. FY2029 targets: $24 bear, $72 base, $143 bull (ref $92.07). Report → Five pillars →
|
|
INDIA DEEP DIVES
India: fresh from the research desk
Polycab (POLYCAB)
Wires and cables · India |
73/100 |
Verdict: Selective Positive. India's wires and cables champion: FY26 revenue Rs 28,884 crore, up 29%, PAT Rs 2,708 crore, up 32%, organised market share up to 30 to 31%, H1 FY27 revenue up 46%, and net cash of Rs 4,520 crore. The cautions are copper flattering the growth, volume growth in low to mid single digits in Q1, and UltraTech entering with a Rs 1,800 crore plan. FY2029 targets: Rs 5,900 bear, Rs 11,300 base, Rs 14,800 bull (ref Rs 7,662).
Full report →
·
Five-pillar analysis →
|
IndiaMART (INDIAMART)
B2B marketplace · India |
71/100 |
Verdict: Selective Positive. The toll booth losing its entry lane: a fortress cash machine with a shrinking funnel. FY26 revenue Rs 1,569 crore, up 13%, free cash flow Rs 687 crore, and cash and investments of Rs 3,234 crore against borrowings of Rs 20 crore. Against that, paying suppliers fell 2% to 217,000 and unique business enquiries fell 14% to 27 million, while revenue per paying supplier rose 10% to about Rs 72,000. FY2029 targets: Rs 1,350 bear, Rs 2,350 base, Rs 3,400 bull.
Full report →
·
Five-pillar analysis →
|
Jenburkt Pharmaceuticals (JENBURPH)
Pharmaceuticals · India |
65/100 |
Verdict: Selective Positive. A debt free small pharma name at 11.5 times earnings: FY26 PAT of Rs 34.74 crore on sales of Rs 169 crore, cash of Rs 53.11 crore, promoters at 46.62% with zero pledging, and five straight years of dividend rises. The caution is Q1 FY27, when operating margin fell to 17%. FY2029 targets: Rs 710 bear, Rs 1,320 base, Rs 1,820 bull (ref Rs 853.60).
Full report →
·
Five-pillar analysis →
|
Research desk roundup, India
Asian Paints (ASIANPAINT), 65/100, Selective Positive. The fortress under siege: FY26 revenue Rs 35,584 crore, record free cash flow of Rs 5,604 crore, decorative share eased from about 59% to about 52% as Birla Opus built capacity, and Q2 FY27 margin fell to 15.6%. FY2029 targets: Rs 1,450 bear, Rs 2,600 base, Rs 3,800 bull. Report →
Saksoft (SAKSOFT), 66/100, Selective Positive. FY26 revenue crossed Rs 1,000 crore with PAT up 22.5% to Rs 133 crore and free cash flow of Rs 167 crore at 12.6 times earnings, against a flat Q1 and a FY30 target that needs about 33% compound growth. FY2029 targets: Rs 95 bear, Rs 185 base, Rs 260 bull. Report →
Ingersoll Rand India (INGERRAND), 68/100, Selective Positive. The oil free cash machine: FY26 ROE of 42.1%, ROCE of 56.3%, zero debt, and free cash flow positive in each of the last five years, priced at about 44 to 46 times earnings. FY2029 targets: Rs 2,575 bear, Rs 4,600 base, Rs 6,850 bull. Report →
|
|
SPECIAL SECTION
The displacement clock
|
Verdict first: Intel missed where its legacy lives and beat where its future is contested. The Q3 miss did not come from hyperscalers designing Intel out this quarter. It sat in PCs and in a fab accident.
Client computing revenue fell 5% to $8.1B. An explosion at the Kiryat Gat fab cut about $300M from fourth quarter revenue. In the same print, Data Center and AI revenue grew 78% to $7.3B.
The slower clock is still ticking. Arm claims about 50% of CPU compute at the top hyperscalers. That is a share shift inside a fast growing market, which is why it can be true at the same time as Intel's data center boom.
The design decisions point the same way. Google's eighth-generation TPU runs only on its own Axion hosts. Meta signed a multibillion-dollar deal for tens of millions of Graviton5 cores.
For the hyperscalers, in-house silicon improves unit costs first. The reported margin payoff arrives after the capex wall, not instead of it. That timing is the whole story of this week in one mechanism.
Read The Displacement Clock →
|
|
|
ONE MARKET THOUGHT
The capex crack
|
Verdict: the market is no longer pricing AI as one trade. It is sorting the spenders, company by company, on whether the spending comes with cash attached.
That sorting is why the index looked calm while the AI complex cracked. Through Thursday the broad index sat close to its high, most stocks rose, and the Fed, GDP, and inflation prints all landed without drama. The names that fell were the ones whose capex rose faster than the cash story beside it. Alphabet printed negative free cash flow for a second straight quarter. Amazon guided capex higher again. Oracle carries the same question in debt form.
The investor takeaway: demand is not the debate anymore. The debate is the bill, and who funds it. In this phase, the cash flow statement is the scoreboard, and a great growth number without one is only half a print.
|
|
|
FROM THE 101 LESSONS
Lesson 35: Price must match growth
|
"Never pay a hypergrowth multiple for slowing revenue. The multiple is a promise. Make sure the growth can keep it."
This week was that lesson at index scale. Alphabet's search growth slowed from 17% to 12% while its multiple still assumed the old pace, and one print repriced it. Netflix shows the other side: growth near 12%, a price already halved, and a cash machine underneath. Same growth neighbourhood, opposite promises embedded in the price.
Read all 101 thoughts on work, life, and investing →
|
|
 |
THE BOOK BEHIND THE RESEARCH NOW LIVE
From Bagholder to Multibagger
The five-pillar system behind this research, with the losses left in.
Buy on Amazon
|
|
|
|
See you after the close,
Prakash
|
|
For educational purposes only. Not investment advice. DalalBytes research reflects the author's personal analysis and opinions.
© 2026 DalalBytes · dalalbytes.com
|
|