
Frequently asked questions
Is NINtec Systems a buy at current prices?
DalalBytes rates NINtec Systems Neutral at 58/100. At Rs 899.85 the stock trades at 46.1x trailing earnings and 52.2x FY26 earnings, against 9x to 19x for listed peers. The business is strong, with FY26 PAT of Rs 32.01 cr, net cash of Rs 98.9 cr and zero promoter pledging, but sales growth has slowed from 68.3% in FY25 to 16.8% in H1 FY27.
What are NINtec Systems FY2029 price targets?
DalalBytes FY2029 targets for NINtec Systems are bear Rs 455, base Rs 800 and bull Rs 1,280, from a Rs 899.85 reference price. Bear: 10% sales CAGR to Rs 227 cr, PAT of Rs 39 cr, EPS of Rs 20.7 at 22x. Base: 18% CAGR to Rs 280 cr, PAT of Rs 53 cr, EPS of Rs 28.6 at 28x. Bull: 26% CAGR to Rs 340 cr, PAT of Rs 68 cr, EPS of Rs 36.7 at 35x.
Who is Tecthink B.V., the largest shareholder of NINtec Systems?
Tecthink B.V. is a Netherlands company that holds 47,25,000 shares, or 25.44% of NINtec Systems, classified in the public category as an overseas corporate body. It has held exactly 25.44% for years and took its pro-rata share of the 2023 bonus issue. No source found for this report names its beneficial owners, and the report prints the question rather than an answer.
What is the verdict on NINtec Systems?
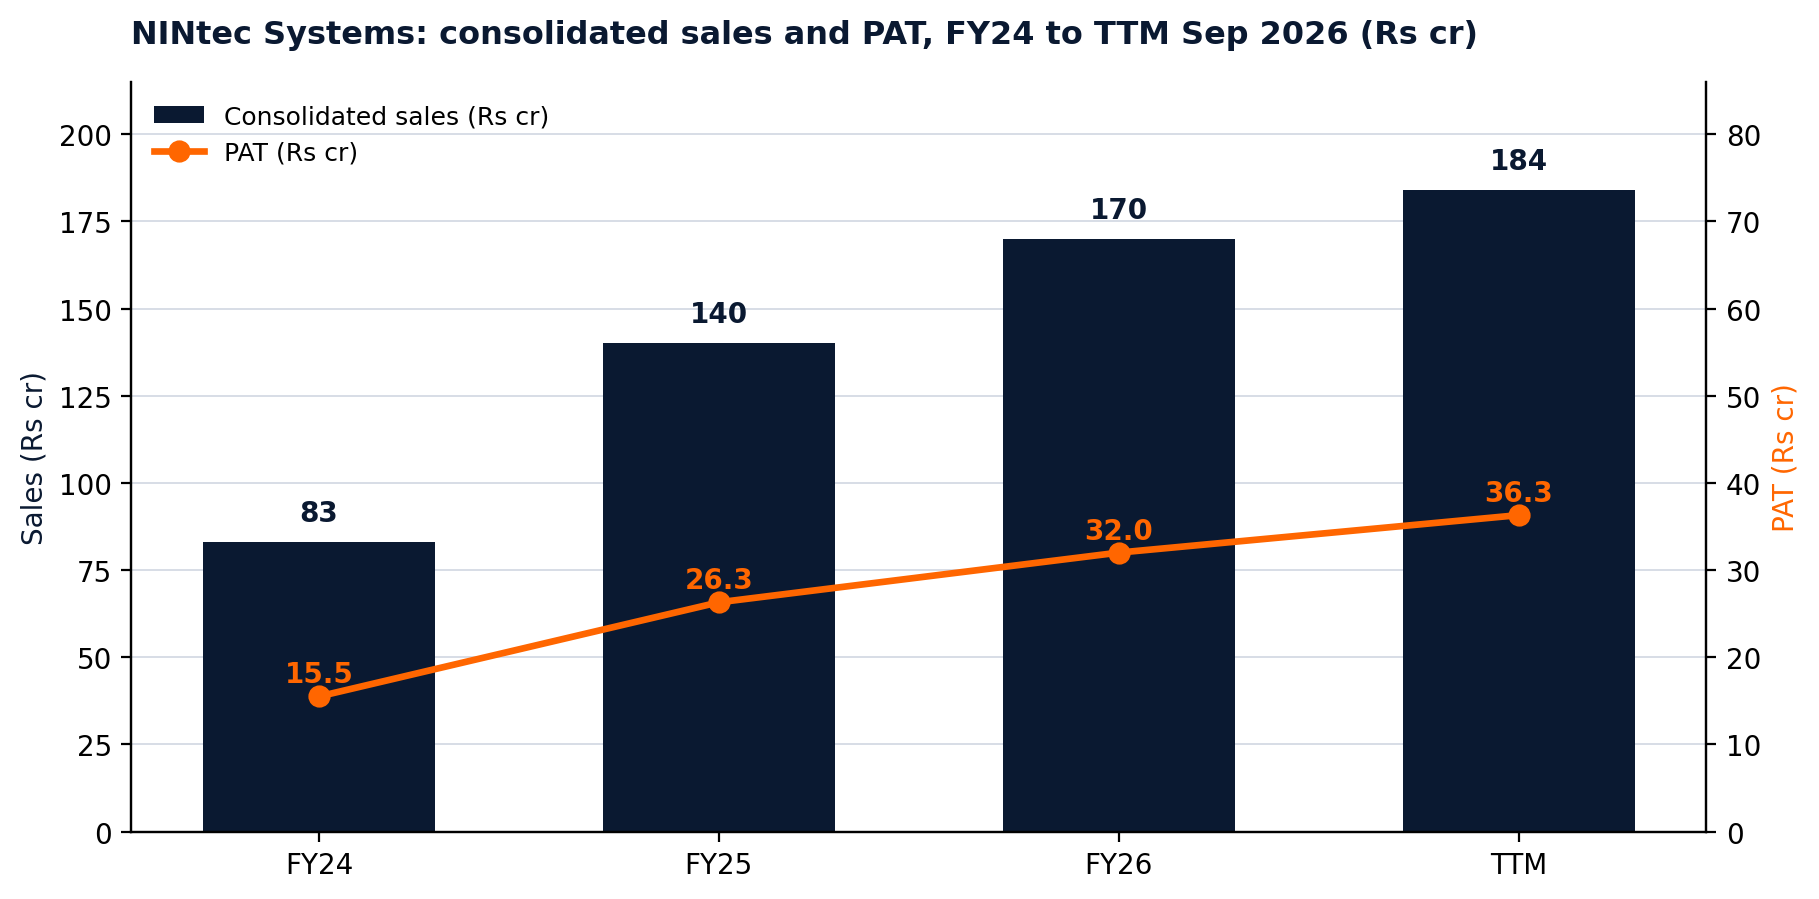
NINtec Systems is a genuinely good small IT services business. Consolidated sales rose from Rs 83 cr in FY24 to Rs 170 cr in FY26, and PAT rose from Rs 15.51 cr to Rs 32.01 cr. The company carries net cash of Rs 98.9 cr, earns a 41.9% return on equity, and has never pledged a promoter share. The stock is the problem: at Rs 899.85 the market pays 46.1x trailing earnings and 52.2x FY26 earnings, against 9x to 19x for peers, while sales growth slows from 68.3% to 21.7% to 16.8%. The largest shareholder, Tecthink B.V. at 25.44%, sits in the public category with no named beneficial owner. Neutral.
How did NINtec Systems start, and what is the Gateway Group?
The listed company is young and the business is not. NINtec Systems was incorporated in Ahmedabad on August 4, 2015. Its promoter Niraj Chhaganraj Gemawat had founded The Gateway Group in 1997, a Netherlands centred software group based at Zoetermeer. NINtec filed a BSE SME IPO eight months after incorporation, raising Rs 1.88 cr at Rs 10 a share, because the clients and the Netherlands front end already existed inside the group. The shares migrated to the BSE and NSE mainboards on February 21, 2023. Two bonus issues followed: 1:2 in June 2022 and 4:5 in August 2023.
What does the business actually do?
NINtec reports one segment, software services. Its filed families are Business Analytics, Cloud Services, Application Engineering and Testing Services, with AI and machine learning work across all four. The current pitch is AI first engineering: Anthropic Claude as the primary co-pilot and Windsurf standard for all engineers, formalised in 2024 and 2025, with Claude Partner Network certification disclosed on October 2, 2026. The shipped work is concrete: in July 2026 it delivered an AI platform for a European automotive marketplace in the DACH region, with seven AI components covering pricing intelligence, image moderation, damage detection, voice automation and dealer matching. The filed verticals are Automotive, Print Media and Publishing, BFSI, and Transportation and Logistics, with group platforms AutoFacets, DiLX and FinFacets mapped to them.
Where does the revenue come from?
The Netherlands subsidiary books about 40% of group revenue and keeps very little of the profit. Standalone sales of the Indian parent were Rs 101.70 cr in FY26 against consolidated sales of Rs 170.17 cr. In Q2 FY27 the subsidiary reported total revenue of Rs 21.30 cr and PAT of Rs 1.05 cr, a margin near 5%, while the group earned Rs 10.57 cr. The Dutch company is a contracting front end and India is the profit engine. Exports were 96.6% of FY26 revenue. The company discloses no split by service, vertical or client.
What do the financials show?
Consolidated sales went Rs 83.05 cr, Rs 139.80 cr and Rs 170.17 cr across FY24 to FY26, with operating margin of 24%, 24% and 26%, and PAT of Rs 15.51 cr, Rs 26.32 cr and Rs 32.01 cr. The standalone arc is longer: sales of Rs 19.81 cr in FY22 to Rs 101.70 cr in FY26, with standalone operating margin reaching 38%. The deceleration is the fact to hold: sales growth ran at 68.3% in FY25, then 21.7% in FY26, then 16.8% in H1 FY27, while PAT growth held up on margin. In Q1 FY27 employee cost fell 4.8% year on year while revenue grew 18.1%, the first checkable sign that AI tooling is lifting delivery leverage.
How strong is the balance sheet and cash flow?
Net worth was Rs 91.63 cr at March 2026 and Rs 113 cr by September 2026. Borrowings were Rs 2.5 cr in September, and net cash was Rs 98.9 cr. Operating cash flow was Rs 26.46 cr in FY26 and free cash flow was Rs 25.9 cr, about 81% of PAT, with capex of only Rs 0.59 cr. Other income was only Rs 1.97 cr against PBT of Rs 42.81 cr, so reported profit is operating profit. The watch item is receivables: Rs 49.14 cr at March 2026, about 29% of sales, with debtor days of 105, improved from 128 in FY25 because receivables stayed flat while sales grew.
Who owns NINtec Systems, and who is Tecthink B.V.?
Promoters hold 47.63% at September 2026, in a 47.2% to 47.6% band held for a decade, with pledging at 0.00% in every quarter. Niraj Gemawat holds 18.44%, Rachana Gemawat held 13.85% and bought 16,829 more shares on November 9 and 11, 2026 to reach 13.94%, VIN IT Solutions LLP holds 9.77%, and Chairman Indrajeet Mitra holds 4.69%. The single largest holder is Tecthink B.V. with 47,25,000 shares, 25.44%, classified as public. No source found names its beneficial owners. If it is group affiliated in substance, true promoter economics are near 73%. If it is independent, one outside holder outranks the Managing Director. FII holding is 0.00% and DII holding is 0.01%.
What is NINtec Systems worth versus peers?
At Rs 899.85: P/E 46.1x trailing on EPS of Rs 19.52 and 52.2x on FY26 EPS of Rs 17.23, P/B 14.76x on book value of Rs 60.97, P/S 9.1x on trailing sales. InfoBeans trades at about 19x with FY26 sales of Rs 514 cr and PAT of Rs 86.7 cr. Ksolves trades at 13.7x on sales of Rs 163 cr, Saksoft at 13.4x on sales of Rs 1,007 cr, Expleo at 9.4x and Kellton at 7.3x. In March 2026 the same business traded near 23x FY26 earnings. Earnings grew about a fifth since and the multiple doubled. FY2029 scenarios: bear Rs 455, base Rs 800, bull Rs 1,280.
What are the key risks?
First, valuation: at 46.1x trailing earnings the stock prices in roughly a decade of clean compounding, and it fell about 11% in the four sessions after its November high. Second, the register: an unnamed 25.44% holder, promoters below a majority, the top 20 holders at about 89.5%, and NSE volume of 44,900 shares on November 11. Third, undisclosed concentration: 96.6% export revenue, about 40% of revenue through one small Dutch subsidiary at a margin near 5%, no client concentration or order book disclosure, and debtor days of 105. Fourth, governance catching up with the valuation: no earnings call since June 2024, a February 2026 board reset that put first time directors into the audit and remuneration chairs, the MD's spouse on the remuneration committee, and a quantum practice marketed with no revenue behind it.
© 2026 DalalBytes Research · For educational purposes only. Not investment advice.